Since April 6, 2026, U.S. Section 232 duties on steel derivatives are charged on the full customs value of the product, and imported steel fasteners under HTS 7318.11 through 7318.29 generally face a 50% rate.
What Changed in the US Tariff Calculation
Section 232 duties have applied to steel derivatives at the full customs value since April 6, 2026, rather than only against the metal content of the product [S1].
Procurement teams therefore need to model both the Section 232 metals duty and any applicable Section 301 China duty instead of treating the US tariff exposure as a single percentage [S1] [S2].
Fastener Categories and Classification Boundaries
Heading 7318 covers screws, bolts, nuts, rivets and washers, while heading 7317 covers nails and similar articles [S4]. Harmonized classifications identify fasteners by product type and material rather than by the industry using them, so gas, LNG or automotive procurement data cannot be isolated as a dedicated tariff line [S4].
This control matters because different summaries can describe tariff tiers differently, while fastener treatment also depends on whether the product qualifies for a special origin regime [S1].
A practical bill-of-materials review can use the method in Map Tariff Exposure by Bill of Materials Line, separating metal content from coating, packaging and other non-fastener charges before calculating landed cost.
Section 232 Compared with Section 301
Section 232 is the metals-duty layer, and its rate is based on the full customs value of qualifying steel derivatives. Section 301 is a separate China-specific authority used by USTR after investigations into unfair or discriminatory trade practices [S2].
Imported steel fasteners under HTS 7318.11 through 7318.29 generally face a 50% Section 232 rate.
The economic comparison is straightforward. A 50% Section 232 duty applies to the customs value of the fastener, whereas a Section 301 charge applies as an additional ad valorem layer to covered Chinese goods [S1] [S2]. For a procurement team, the combined bill can therefore exceed either headline rate, and a classification or origin error can produce an incorrect bid model.
Which Fasteners Carry the Greatest Budget Impact
Standard carbon steel fasteners such as Grade 5 and Grade 8 hex bolts, nuts and flat washers carry material exposure, but their purchase volumes can spread the cost across a large number of units [S5]. Specialty items present a harsher problem because they have lower margins, fewer qualified sources and smaller order quantities [S5].
Fastener pricing has not moved in step with feedstock costs. U.S. producer prices for bolts, nuts, screws, rivets and washers fell 3.1% year over year in September 2026, preliminary, while steel mill product prices rose 27.6% [S1]. This divergence gives buyers a reason to demand item-level cost breakdowns rather than accepting a broad claim that fastener prices have risen by the same percentage as steel [S1].
Demand Sectors Do Not Remove Tariff Risk
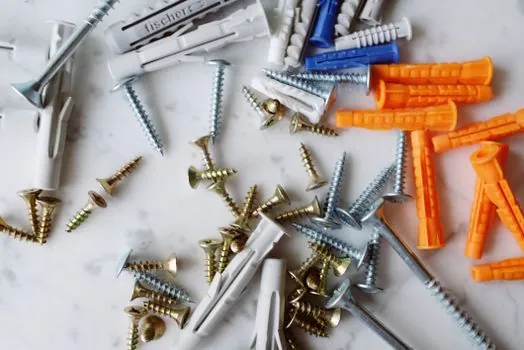
The 2026 outlook for U.S. oil and gas fasteners appears selectively favorable rather than uniformly strong, with LNG export terminals identified as a fastener application. Supporting products include bolts, studs, nuts, washers, anchors and threaded rod for structural steel, pipe supports, valves, cryogenic equipment and rotating machinery [S4].
The latest EIA outlook projects U.S. crude oil production at 13.5 million barrels per day in 2026, while marketed natural gas production is expected to rise 2%.
LNG and oil and gas orders can still be exposed to U.S. duties when bolts, flanges, valves or other purchased equipment contain imported steel or fasteners. Contracts should allocate tariff liability at the purchase-order level instead of treating a project as immune because its end market is domestic [S1] [S4].
Contract, Inventory and Supplier Controls
Tariff clauses should state whether the importer of record pays the duty, which party owns classification and origin risk, and how costs are handled if a rate changes after quotation [S2]. Fixed-price agreements without pass-through language turn a regulatory change into an immediate margin event, particularly for machined or coated fasteners with few alternative mills [S2] [S5].
Domestic-only manufacturing lowers direct tariff exposure but can increase price and reduce flexibility, while multi-region sourcing moderates exposure at the cost of qualification work and internal overhead [S2]. For routine fasteners, qualification can be managed through approved grades, dimensions, coatings and testing. For pressure-critical, high-strength or corrosion-resistant parts, changing material origin or production route can invalidate documentation and engineering assumptions.
Specialty fasteners can also connect directly to the material-selection decisions described for industrial rubber, industrial coating and industrial lubricant, because elastomers, coatings and lubricants must remain compatible with the bolt grade and service condition after the sourcing route changes.
European and Canadian Measures Add More Variables
The EU Carbon Border Adjustment Mechanism entered its definitive phase on January 1, 2026, with certificate purchases for 2026 imports due by February 1, 2027 [S1]. A U.S. fastener supplier serving European plants may therefore face both U.S. export-side tariff friction and EU carbon-accounting requirements, depending on production and shipment routing [S1].
Canada imposed counter-tariffs of up to 50% on USD 27.6 billion of selected U.S.-origin goods, including iron and steel, effective September 8, 2026 [S6]. For a North American OEM, the practical exposure map must therefore include the country of manufacture, the country of origin, the destination and the tariff authority applied to each shipment [S1] [S6].
The strongest sourcing strategy is not a single replacement country. It is a controlled set of qualified origins with current HTS data, documented melt criteria, traceable coating and testing records, and contract language that assigns classification and tariff responsibility. For more detail on shipment disruption outside the tariff calculation, see Fastener Feedstock Cost Snapshot: Wire Rod Pricing Across Four Regions, Q1–September 2026.
The next procurement review should extract every fastener line, confirm its 10-digit HTS code and metal origin, calculate stacked Section 232 and Section 301 exposure, and compare the result with available U.K., U.S., Taiwanese or other qualified source options before issuing a fixed-price award.