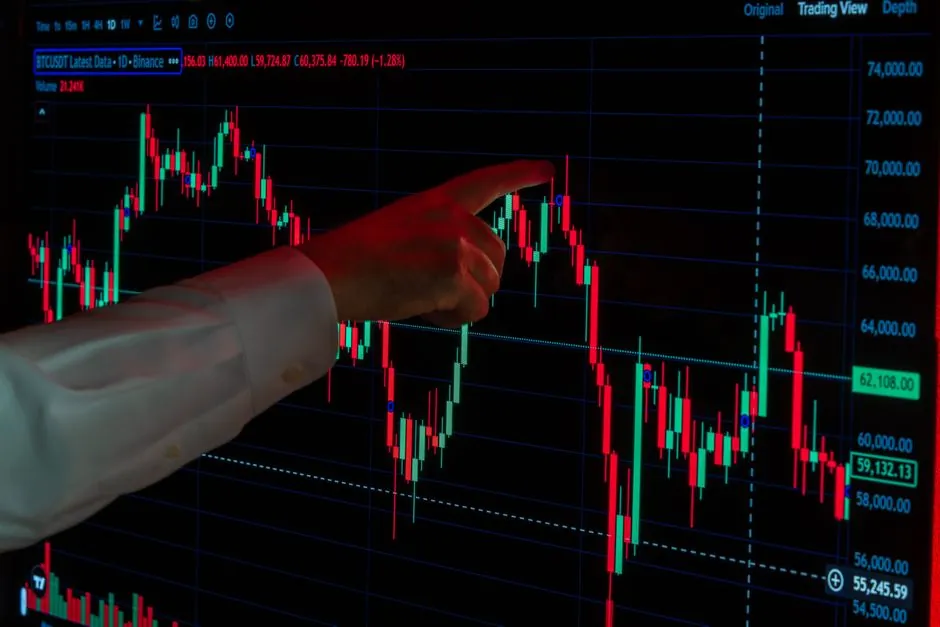
Rebar sits inside the long steel family in every major commodity price index, and the U.S. Producer Price Index for the WPU1074051 cell (Fabricated Structural Metal Bar Joists and Concrete Reinforcing Bars) closed August 2026 at 385.370, a series record, up from 354.964 in May 2026 and 373.472 in July 2026 [S2][S5].
Long products, rebar included, account for approximately 40-45% of global steel production, and the broader WPU101 (Iron and steel) line advanced from 329.774 in January 2026 to a preliminary 378.128 in August 2026, a 14.7% year-to-date gain inside the same PPI family [S1][S3].
Where rebar sits in the BLS PPI hierarchy
The U.S. Bureau of Labor Statistics nests rebar under commodity code WPU1074051, "Fabricated Structural Metal Bar Joists and Concrete Reinforcing Bars," which rolls up into WPU1017 (Steel mill products, 381.162 preliminary, August 2026) and then WPU101 (Iron and steel, 378.128 preliminary, August 2026) [S1][S2].
Reclassification risk is real for procurement teams. The WPU1074051 cell bundles rebar with fabricated bar joists, so a joist-side distortion, say a spike in data-center or warehouse construction, can mask pure rebar deflation. For rebar-only tracking, buyers should pair the BLS cell with private indices like the U.S. Steel Rebar Price Index, which printed roughly USD 958.00/MT in the third quarter of 2026, up 2.06% quarter-over-quarter [S8].
Long-product classification and what it implies for specs
Rebar qualifies as a long product on three measurable criteria: it is hot-rolled from billet, finished as a discrete length (typically 6-12 m), and used predominantly in concrete reinforcement, distinguishing it from flat-rolled sheet, plate, and pipe products [S3]. Global production of rebar alone exceeds 200 million tonnes annually, with diameters spanning 6-50 mm and construction-grade sizes concentrated in the 8-32 mm range [S3].
Long products account for roughly 40-45% of global steel output and span rebar, wire rod, structural sections, and rail; rebar is the highest-volume subcategory, with EAF mini-mills producing approximately 70% of global supply thanks to scrap-based economics and forgiving chemistry windows [S3]. Standard specifications, including BS 4449, ASTM A615, and EN 10080, define deformation patterns with transverse ribs at 45-70 degrees from the bar axis and rib heights of 5-15% of nominal diameter, the same mechanical-interlock geometry that lets rebar trade as a fungible commodity [S3]. For deeper specification detail, see the rebar reference page and the steel rebar overview.
Cost drivers: scrap, energy, and Chinese export floors
Rebar pricing decomposes into three primary cost drivers, in order of leverage: ferrous scrap (the EAF feedstock), electricity and graphite electrode costs, and Chinese domestic export pricing that acts as a global floor [S3][S4]. Turkish rebar exports to the Middle East and Asian material into Southeast Asia typically transact at USD 450-530/tonne CFR, with mill margins occasionally compressing below USD 30-40/tonne when Chinese mills push export tonnage into a soft market [S3].
The Northeast Asia spot benchmark printed at USD 0.48/kg in September 2026, up 2.1% month-over-month, mirroring the BLS PPI acceleration in the same window [S6]. MarketsandMarkets sizes the global rebar market at USD 202.27 billion in 2026, expanding to USD 250.38 billion by 2031 at a 4.4% CAGR, while market.us projects a slightly steeper USD 212.5 billion (2024) to USD 330.0 billion (2034) trajectory at 4.5% CAGR [S4][S7]. The 100-200 basis-point spread between the two CAGR estimates is typical: rebar demand is sensitive to infrastructure-spend assumptions, and small shifts in Chinese property completions move the global growth line.
Regional and end-use mix, where the tonnage goes
Asia Pacific held a 74.1% share of the global rebar market by value in 2025, a concentration that mirrors Chinese and Indian construction cycles and explains why the BLS WPU1074051 index is now an import-sensitive read on Section 232 and anti-dumping duty flows [S4]. By end-use sector, infrastructure leads, followed by housing and industrial; by bar size, the #4 (1/2-inch, 13 mm) size is forecast to command the largest revenue share through 2031, consistent with the 8-32 mm diameter sweet spot for slabs, beams, and light foundations [S3][S4].
By process route, basic oxygen steelmaking (BOS) is forecast to lead the market by value, even though EAF dominates tonnage, a distinction worth flagging: BOS rebar carries higher embedded carbon and trades at a small premium in low-emission procurement contracts, while EAF rebar captures the recycled-content, LEED-aligned specification niche [S3][S4]. Plain carbon (uncoated) rebar dominates the coating mix, with galvanized and epoxy-coated variants reserved for marine, bridge-deck, and high-chloride applications.
Procurement, hedging, and signal nodes to track
For cost-driven procurement, three verifiable signal nodes are worth wiring into a monthly review. First, the BLS WPU1074051 release on the 15th of each month, with the next print on October 15, 2026 covering September 2026 data [S2]. Second, the LME and CME rebar futures complex, where SRW and HRC futures curve movements telegraph scrap and energy cost shifts 60-90 days out [S9]. Third, the Chinese domestic rebar price on the Shanghai Futures Exchange, which historically sets the global floor when Chinese mills swing between domestic inventory build and export push [S3].
For buyers weighing long contracts versus spot, the August 2026 PPI surge of 1.91% month-over-month in WPU1074051, against a 14.7% year-to-date rise in WPU101, argues for fixing 60-70% of 2027 H1 needs now and leaving the remainder on indexed or spot terms [S1][S2]. Working with a rebar bender and rebar cutter supplier on bundled pricing can also lock fabrication yield, typically 98-99% on standard stock lengths, against a backdrop where mill margins are already compressed to USD 30-40/tonne on export tonnage [S3].
Related analysis: Scalloped vs Straight-Sided vs Link-Type Disc Packs: Selection Guide.