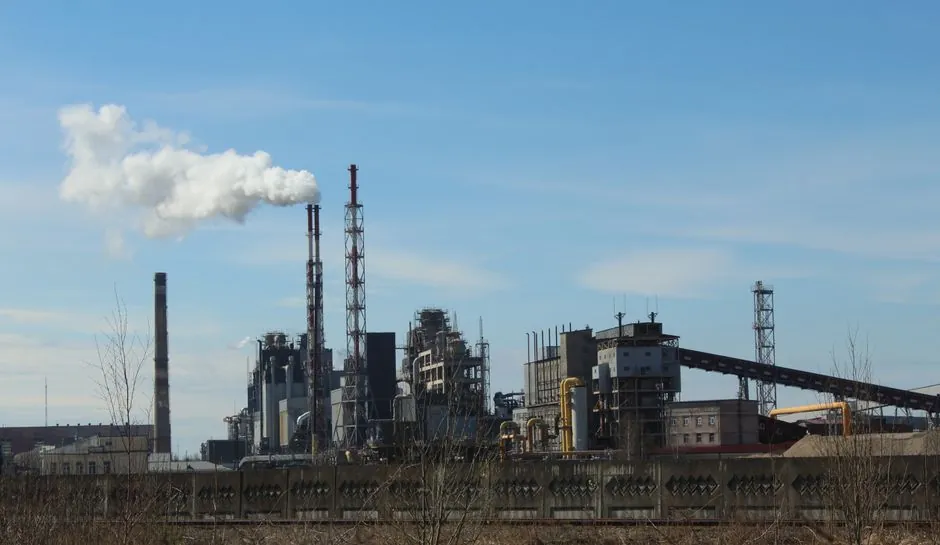
US industrial production reached 103.95 in September 2026, marking 2.2% year-over-year growth and a 2.4% increase through the first nine months of 2026 [S1][S3][S5].
The Federal Reserve’s seasonally adjusted total index uses a 2017=100 base, while one market forecast places the 2026 index at 102.5 with full-year growth of 1.2% [S1][S2].
What the September 2026 Index Shows
The headline reading confirms that industrial output remained above its prior-year level: the total index rose from 101.67 in September 2025 to 103.95 in September 2026, a 2.2% increase [S3][S5].
Momentum improved from August to September, with annual growth accelerating from 1.6% to 2.2% [S3]. The six-month average matters more for trend analysis: it was running sideways in March 2026, and production had not then exceeded the manufacturing peak recorded in September 2025 [S4].
The distinction between the headline index and the manufacturing trend is important. Total industrial production includes manufacturing, mining, and utilities, while the manufacturing component provides a cleaner signal for factory-based demand [S1][S4].
Monthly Volatility Masks the 2026 Trend
March 2026 production fell 0.5%, against an expected increase of 0.1%, after gains of 0.6% in January and 0.4% in February [S4]. The March result also included net downward revisions to earlier months [S4].
Utilities and mining contributed to that weakness. Utility output declined 2.3%, mining activity fell 1.2%, and manufacturing output decreased 0.1% in March [S4]. Weather effects can materially disturb utility production, which weakens the usefulness of one month for judging underlying industrial demand [S4].
Manufacturing breadth was nearly balanced in March, with 11 industries increasing output and nine reducing production [S4]. Automotive output fell 3.7%, while furniture, textiles, apparel, and printing each declined by more than 1.0%; manufacturing output excluding autos still increased 0.1% [S4].
Manufacturing Capacity Signals a Muted Recovery
The six-month moving average provides a more stable test than any single monthly observation. It was moving sideways in March, and the manufacturing index had not recovered its September 2025 peak [S4].
For equipment planners, that combination argues against reading September’s 2.2% year-over-year total-index growth as evidence of a broad factory expansion. The more cautious interpretation is improving annual output alongside a manufacturing trend that had not clearly broken above its prior peak [S3][S4].
Comparing the Main Production Measures
Total industrial production provides the broadest view: 103.95 in September 2026, 2.2% above the prior year, with a 2017=100 base [S1][S3]. Manufacturing output offers a narrower factory measure, and its six-month average was still sideways in March [S4].
Those three measures answer different questions. The total index tracks combined industrial output, the manufacturing average filters short-term volatility, and capacity utilization indicates how intensively manufacturers use available production capacity [S1][S4].
The available annual forecast is more restrained than the September growth rate: it projects a 2026 index of 102.5 and 1.2% annual expansion, with the index growing at a compound annual rate of 0.6% since 2021 [S2]. Historical monthly growth data extend from January 1920 through September 2026, spanning a minimum of -33.7% in February 1946 and a maximum of 62.0% in July 1933 [S3].
Where the 2026 Recovery Is Not Broad
The early-year sequence did not establish a strong slope. January and February produced gains of 0.6% and 0.4%, respectively, but those increases followed a weak fourth quarter, while March then fell 0.5% [S4].
Manufacturing also remained below the September 2025 peak through the portion of 2026 covered by the March analysis [S4]. A sideways six-month average is the relevant warning: one strong month does not override the broader manufacturing signal when plant orders, capacity use, and the moving average have not aligned [S4].
Industrial output does not translate one-for-one into demand for every category of process equipment. A broad production index can rise while individual sectors contract, as the March data demonstrated with automotive output down 3.7% and four additional manufacturing groups each down more than 1.0% [S4].
Applying the Trend to Industrial Procurement
Production growth supports procurement from suppliers whose order books track manufacturing output, but the decision should be tied to utilization and the six-month average rather than one headline print. March manufacturing output dipped 0.1%, while 11 manufacturing industries expanded and nine contracted [S4].
Material and maintenance planning should distinguish output-sensitive categories from condition-sensitive categories. Production-linked demand can follow the total and manufacturing indexes, while replacement demand for industrial lubricants, industrial adhesives, and industrial coatings also depends on asset age, maintenance intervals, and operating severity.
For electrical and automation projects, production direction remains relevant, but installed capacity and utilization provide a more useful sizing basis. The 2026 industrial automation comparison covering PLC, DCS, and drives can help connect macro production evidence with equipment-level architecture and procurement criteria.
Engineering teams should also track whether rising output translates into higher utilization rather than merely longer operating hours at existing capacity. March’s 75.2% rate remained below the 75.4% 2025 average, so inventory, labor, and energy constraints cannot be inferred from the September headline alone [S4].
The next trackable signals are the October and November 2026 monthly index releases, revisions to September’s 103.95 reading, and whether the manufacturing six-month average turns upward rather than remaining sideways [S1][S4].