
Leading Indicators for the Semiconductor Cycle in 2026
Track semiconductor cycles in 2026 with a dashboard combining inventories, memory prices, foundry utilization, equipment spending, and end-market demand.
Read →Industry News · Category
Track semiconductor cycles in 2026 with a dashboard combining inventories, memory prices, foundry utilization, equipment spending, and end-market demand.
Read →
Lead-free brass adoption is expanding in potable-water products, driven by a 0.25% lead threshold in U.S. law and tighter European material rules.
Lead-acid batteries are forecast to grow in 2026, not decline: market estimates range from USD 51.80 billion to USD 56.12 billion.
LCD TV panel prices diverged by size in 2026: 55-inch UHD open-cell panels averaged $123 in October, while 65- and 75-inch panels rose to about $171 and $232 in February.
Laser marking demand is expanding as manufacturers require permanent part-level IDs, serial numbers, 2D codes, and verified traceability records.

AWS leads global hyperscale capacity in 2026, followed by Microsoft, Google, Meta, Oracle, and Alibaba, as operators target 1,360 live sites.
Large-format additive manufacturing builds meter-scale tooling from thermoplastic pellets, cutting lead times while raising material, geometry and certification constraints.
Large-block colocation ranks by live capacity and delivery, not brand alone. Equinix, Digital Realty, CyrusOne, QTS and Vantage lead U.S. scale, but 1% vacancy leaves few blocks.
Wind turbine and industrial gearbox markets are expanding, with wind demand driven by larger rotor diameters, higher rated capacities, and replacement needs through 2035.
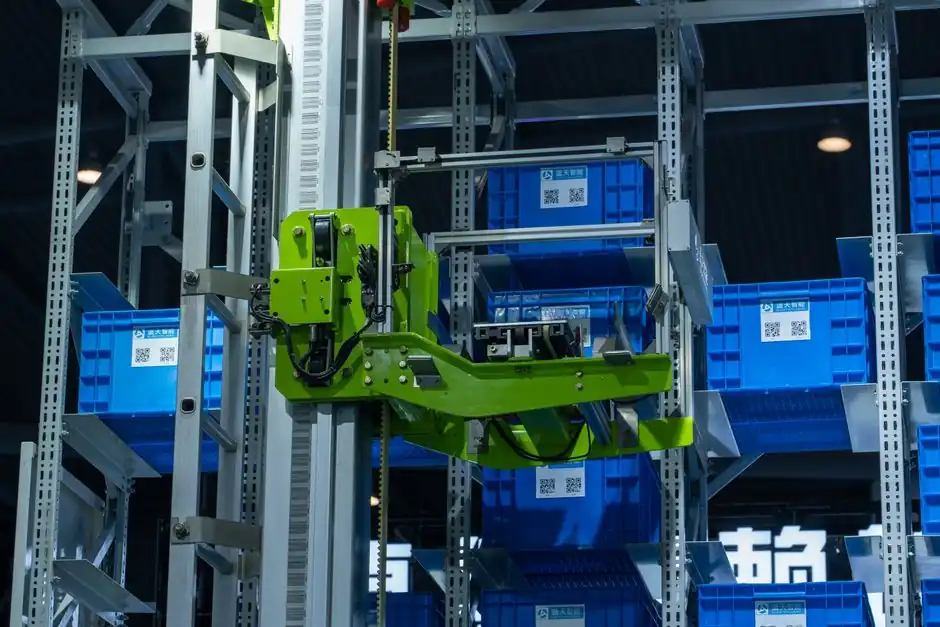
Warehouse automation spending is recovering, with a 2026 market estimate of $34.17B.
Evidence points to a fragmented commodity upswing in 2026, not a uniform supercycle: energy, strategic metals and gold are advancing on different drivers.
Lithium carbonate fell 25.09% in the month to November 6, 2026, but evidence of sustained market-bottoming remains insufficient.
Global display shipments are projected to fall 4.7% in 2026, even as IT panel volumes recover and industrial DDIC demand stabilizes.

Industrial conditions showed selective early-cycle improvement in 2026, supported by low customer inventories, improving orders relative to inventories, strengthening core capital goods orders, and extended steel lead times rather than evidence of broad consumption growth.
Sodium-ion is a credible LFP competitor in stationary storage, but LFP still leads on cost, efficiency, cycle life, and bankability in the 2026 Q2 comparison.
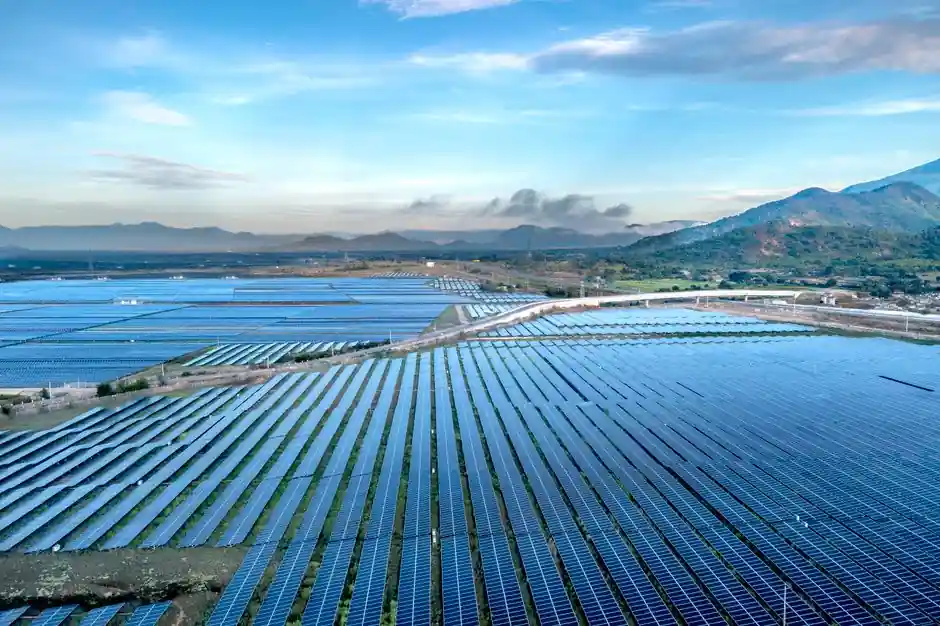
The U.S. agrivoltaics market includes nearly 700 installations covering 85,000 acres and producing around 14 gigawatts of power.
Farm machinery demand is nearing a bottom, but 2026 recovery is uneven, with replacement, livestock and medium-power equipment outperforming large tractors.

The injection molding machine market is projected to expand at a 4.6% CAGR from 2026 to 2035, reaching USD 17.26 billion by 2035.

Industrial weighing equipment is valued at $5.8B in 2026, with load cells and checkweighers serving distinct high-value measurement roles.
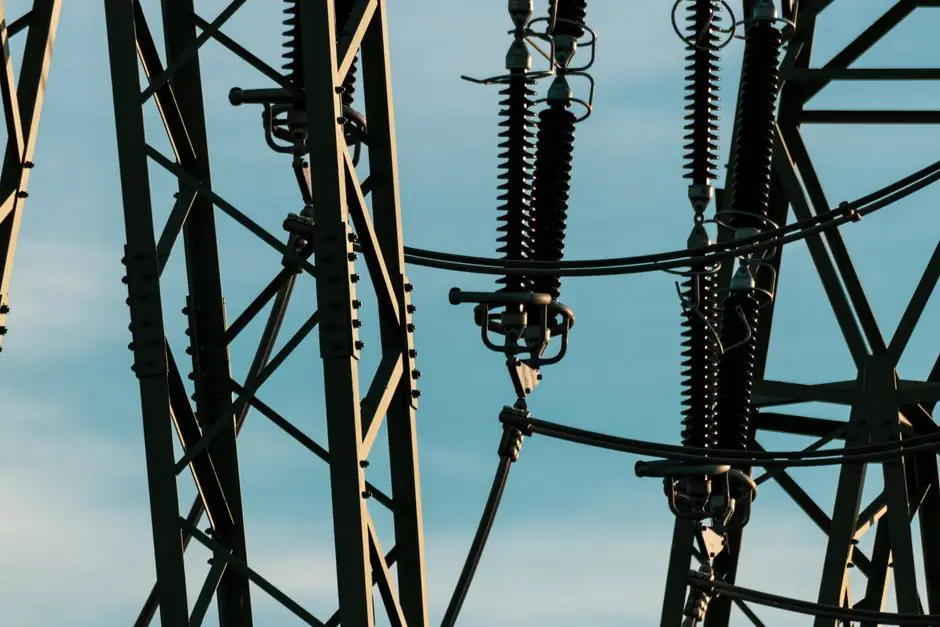
Residential solar inverters cost $0.10–$0.25/W installed, while utility-scale inverter pricing is set within $0.90–$1.30/W total plant budgets.
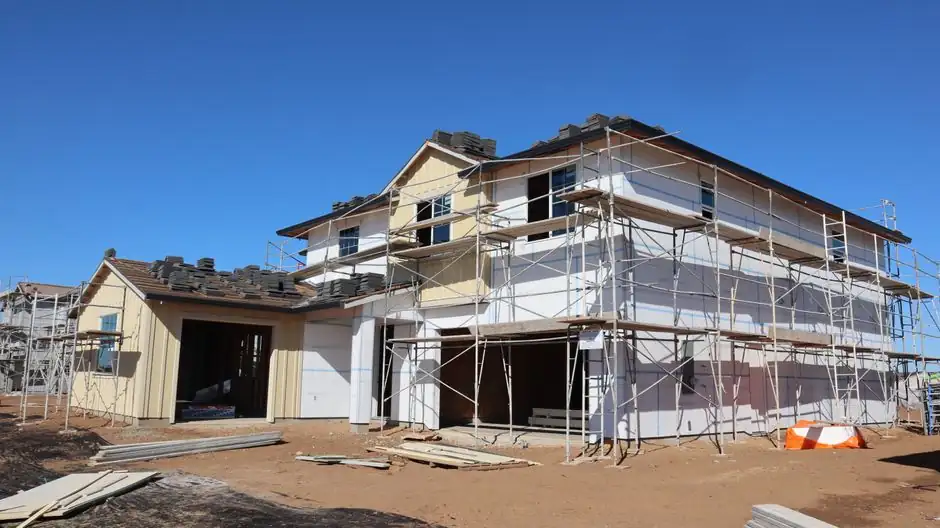
Mineral wool led building thermal insulation with a 50.51% share in 2026, while EPS, XPS and PIR compete on thickness, fire performance and installed cost.
Industrial software M&A reached 123 deals in H1 2026, led by MES, enabling software, and engineering platforms as AI and simulation became strategic buying criteria.
Industrial sensor ASPs face continued erosion as unit growth outpaces revenue, but qualified sensing products retain value through integration, accuracy, and service.

Industrial semiconductor demand is recovering selectively: WSTS projects 8–9% growth for 2026, led by AI and automotive, while lead times and component availability remain constrained.

Global chip sales are projected above $1.5 trillion in 2026, with industrial automation and renewable energy adding steady semiconductor demand beyond AI.
Global safety light curtain demand is valued at USD 1.39–1.97 billion for 2026, with Type 4, finger protection and connected diagnostics shaping specifications.
North American industrial robot orders reached 10,989 units in Q3 2026, up 24.8% year over year as semiconductor, automotive and plastics demand expanded.
US industrial production reached 103.95 in September 2026, up 2.2% year over year and 2.4% for 2026 through September.
Choose continuous inkjet for variable codes on moving, non-contact production lines; choose laser for permanent, high-contrast marks on compatible rigid components.
EU industrial electricity prices remained above twice US levels in 2025, while Germany's approved relief for eligible industrial electricity consumption in 2026–2028 includes a price floor of 5 ct/kWh and is capped at 50% of the wholesale electricity price.
Industrial motor demand is shifting toward IE4 and IE5 efficiency classes, driven by regulation, automation, and data-center expansion across global markets.
Bentonite, silica and kaolin face firmer 2026 demand, with growth tied to construction, paper, coatings, rubber, ceramics and drilling fluids.
Industrial heat pump prices run near €1,000/kW installed for a 5 MW system, but total cost depends on heat lift, capacity, utilization, and electricity price.
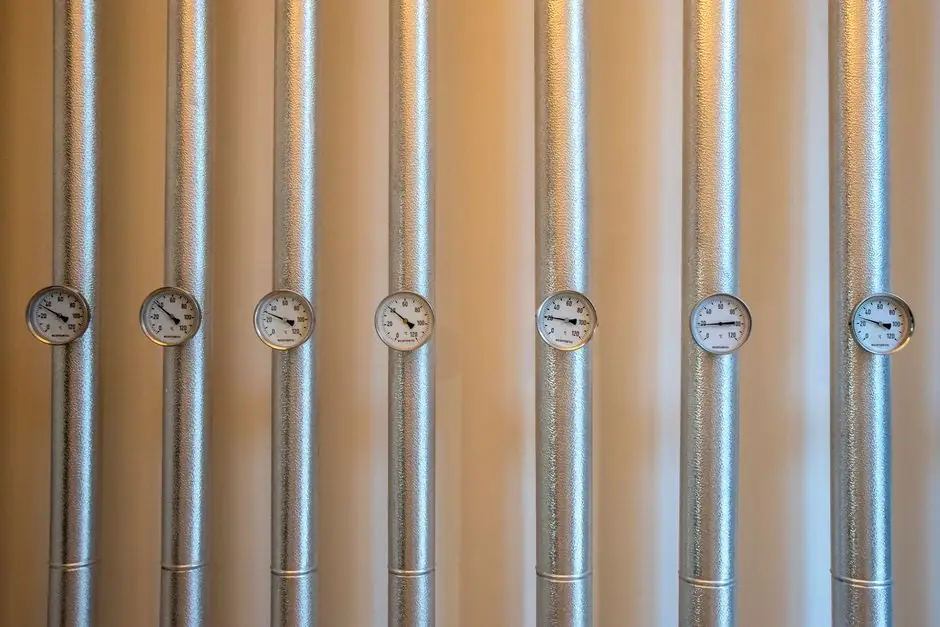
Industrial heat pumps can replace boiler-generated steam, but deployment depends on source heat, temperature lift, electricity cost, and plant integration.

Industrial filtration reached an estimated USD 39.65 billion in 2026, with semiconductor and pharmaceutical demand driving high-purity liquid and air systems.

North American industrial fastener demand is projected to reach USD 22.29 billion in 2026, with demand shifting toward lighter, higher-performance products for electric vehicles and next-generation aircraft.
Industrial Ethernet accounted for 79% of newly installed industrial network nodes worldwide in the 2026 study, up from 76% in 2025.
Metals and energy costs diverged sharply in 2026: BLS metals PPI reached 391.993 by September, while the World Bank projected Brent at $86 per barrel for 2026.

Industrial catalyst demand reaches USD 34.0 billion by 2034, with refining, petrochemicals, and emissions control forming the main growth markets.

Canada’s 2026 nominal capital spending is forecast to rise 3.7%, with private investment up 2.8% and public spending up 5.1%, led by infrastructure and utilities.

Hyperscaler capex guidance reached US$720–745 billion for 2026, with increases outweighing Microsoft’s US$5 billion cut.

Industrial boiler and burner demand in 2026 is shifting toward enforceable NOx controls, with U.S. rules targeting about 70,000 tons of ozone-season NOx reductions.

The industrial battery market reaches USD 41.93 billion in 2026, with lithium-ion holding 51.26% and motive power serving forklifts, AGVs, and telecom.

Industrial backlog coverage is incomplete, but available 2026 data show construction at 8.8 months and AECOM growth, with sector ratios requiring normalization by revenue.
The 2026 industrial automation market spans USD 251.06 billion, with PLCs, DCS and drives chosen by control scope, process duty and lifecycle needs.
Industrial automation M&A reached 92 year-to-date deals in 2026, above the five-year average of 84, while strategic buyers captured 69.6% of volume.
Indium reached 4,950 CNY/kg on October 28, 2026, while ITO remained the largest demand outlet and solar demand stayed uneven.
The EV hub-motor market is estimated at US$37.5 billion in 2026, with two-wheelers holding 41.8% and dual hub motors emerging as the fastest-growing layout.
Imported Chinese aluminum extrusions entered the United States in 2026 with company-specific duties layered over the base price, metal conversion cost, freight, and Section 232 charges.
Immersion cooling trails direct-to-chip in 2026 because retrofit cost, infrastructure changes, and training outweigh its thermal advantages for most AI racks.
Liquid immersion is moving from transformers and data centers into high-frequency power electronics, using dielectric fluids to remove heat and support compact, high-voltage designs.
The 2026 IIoT platform market is consolidating around fewer, application-led stacks, with platform revenue projected at $14.63 billion and deployment value shifting toward edge, data, and analytics.
The 2026 IGBT and super junction MOSFET market spans US$13.84–20.82 billion across published estimates, with growth tied to EVs, renewables, storage, and drives.
ABF leads 2026 IC substrate demand with USD 7.19B market value, while BT offers a mature, lower-complexity alternative for CSP, BGA, and memory packages.
US hyperscalers are on track for $800 billion of 2026 capex, with about 75% directed to AI infrastructure.
Hyperscale campuses deliver scale and efficiency, while colocation offers faster deployment and tenant flexibility; 2026 growth favors both models.
Hyperscale colocation leasing remains a major 2026 growth channel, with deals beginning at 4 MW and commonly running 10 to 15 years, but no verified 2026 leasing total is published.
Hydrogen-based DRI plants remain technically proven but commercially constrained, with 2026 schedules shifting toward 2027 and beyond.
Global electrolyzer shipments are moving into gigawatt scale in 2026, with China’s 2025 tenders reaching 3.02 GW and major projects advancing from design to commissioning.
Hydrogen blending is moving into infrastructure trials, with blends up to 20% operating through existing networks and 23% assessed in Romanian grid studies.
Mobile hydraulics held 56.48% of the hydraulics market in 2026, leading industrial applications on scale while differing sharply in cost, weight, and service life.
Hybrid bonding is advancing toward HBM and logic production, but 2026 adoption remains constrained by thermal budgets, alignment, yield, and equipment.
Hybrid additive-subtractive machines reached an estimated $2.80 billion market in 2026, targeting $5.45 billion by 2030 at an 18.1% CAGR.
Europe’s HVDC pipeline exceeds 111 GW by 2035, while U.S. projects advance through 2028 on 525 kV, multi-gigawatt designs.
The HVDC transmission market was worth US$15.50 billion in 2026, with converters leading and offshore wind accelerating VSC demand.
Commercial HVAC demand leads 2026 growth as replacement and modernization outweigh weaker residential spending across North America.
Global humanoid robot shipments exceeded 22,000 units in H1 2026, nearly 300% above H1 2025, while industrial and commercial deployments passed 70% of shipments.
Published humanoid robot prices span $4,900 to $90,000, with $20,000–$30,000 emerging as the scale-production target for capable industrial units.
HTLS conductor demand was forecast at USD 1.4 billion for 2026, with ACCC holding an estimated 38% product share in 2025 and transmission accounting for 68%.
New LNG capacity of roughly 93–150 mtpa could lower benchmark gas prices, but geopolitical disruptions can override the new supply advantage.
2 nm chips can cut chip and rack power losses, but 800 V DC distribution and backside power are needed to realize the gain.
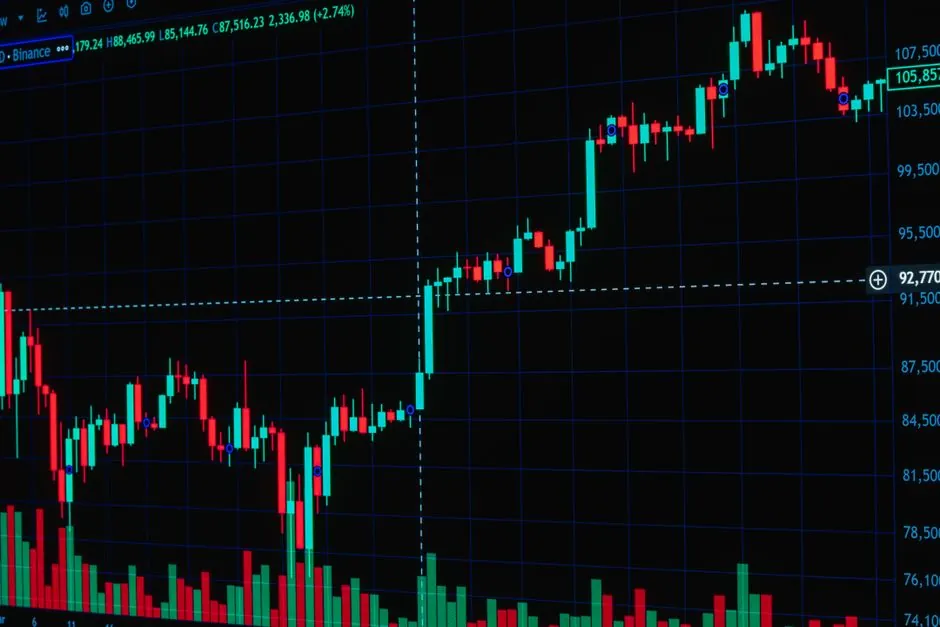
Dysprosium and terbium oxide prices are roughly 3.7x and 17x the NdPr price floor in 2026, and show far larger multi-year swings, with dysprosium up 377% YTD and terbium up 150% in Q3 alone. The data profile for DyTb is not a sharper version of NdPr volatility, it is a structurally different market.

Transformer demand planning must distinguish equipment revenue, unit orders and electricity consumption. The IEA's 2026-2030 electricity outlook informs the regional context, but does not supply equivalent transformer shipment growth rates or delivery commitments.

Country comparisons require comparable manufacturing-output data. Installed network ratings, investment announcements and supplier delivery slots measure different things. The sources here support a verification framework, not national production totals or a country ranking.
The global copper market in October 2026 is tighter than 2025 in price terms but looser in physical balance: LME cash above $14,500/t, ICSG tracking a +96 kt 2026 refined surplus, and tightness concentrated in China, not the world.
Industrial buyers should budget raw materials using a 3-scenario model built on a 2.4% PCE inflation baseline and 3.4% federal funds rate, lock prices through forward contracts, and add 8-15% contingency above quoted unit cost to absorb tariff shifts, energy surcharges, and freight spikes documented
A single humanoid carries 2-4.5 kg of sintered NdFeB magnets across roughly 30 joint motors, so a 1 million robot/year production run adds 2,000-4,500 tonnes of NdFeB and 35-79 g of dysprosium per unit, equal to 7-15% of today's EV magnet demand.
U.S. refinery capacity is on track to drop by roughly 402,476 bpd in 2026, pushing total throughput below the 2023 level of 18.06 million bpd, with California alone shedding 17.5% of in-state capacity by April 2026 from two major closures.
U.S. data centers consumed about 4.7% of national electricity in 2024 (192 TWh), with 2026 share projections ranging 5.3-7.2% of total demand and 5.3% of peak summer load, driven by AI workloads averaging 60% of facility consumption.
Flagship AI accelerators in Q4 2026 draw 1,400 W to 2,500 W per board, with full rack systems rated up to 132 kW; total facility power is now the binding constraint on frontier deployments.
2.5D interposer and fan-out-on-substrate solutions held 45.72% of the 2.5D and 3D semiconductor packaging market in 2025, with the combined segment valued at USD 12.73 billion in 2026 and growing at 13.69% CAGR to 2031.

AI-related chips generate roughly half of global semiconductor revenue in 2026, about US$500 billion, while occupying less than 0.2% of total unit volume, per Deloitte and Gartner forecasts.
For a 1 GW AI hyperscale data center, servers swallow 60% of annualized total cost of ownership ($5.0 B/yr on $8.5 B), with chips plus networking near 80% of lifetime cost; facility shell, power and cooling combined sit under 25%.
About 80 nuclear reactors were under construction worldwide as of September 2026, with roughly 78 GW of combined capacity across 15 countries; China alone accounts for 36-38 units (49-50% of the global build), with India, Russia, Turkey, Bangladesh, South Korea and Egypt contributing the rest[S
Per-chip memory bandwidth across AI accelerators has compounded at roughly 4.1x per year, reaching about 70 million TB/s in aggregate by Q4 2025, driven by the shift from compute-bound training to memory-bandwidth-bound decode.
Top lithium producers disclosed first-half 2026 results showing a divergent volume picture: Rio Tinto posted 12,700 MT LCE in Q1 with 33% sales growth, while PLS Group produced ~879,500 dry tonnes of spodumene for full FY2026 and approved a A$1.9B expansion.
The global data center construction pipeline is on track for roughly $3 trillion in cumulative investment by 2030, with about 16 GW of capacity slated to come online in 2026, though 30–50% of that 2026 pipeline may slip past year-end.
Battery-grade lithium carbonate sits near USD 14,845 per tonne on Shanghai Metals Market and USD 19,750 per tonne CIF Asia on Benchmark Mineral Intelligence as of early September 2026, with August domestic China exw prices averaging about RMB 140,000 per tonne after a 10.3% monthly drop.
Large power transformer unit prices have climbed 77% since 2019, with distribution units up 78% to 95% and lead times for power units reaching 128 weeks as of Q2 2025, per industry sourcing data. Extreme spot cases show 400% to 900% jumps on small pad-mount units, driven by grain-oriented electrical
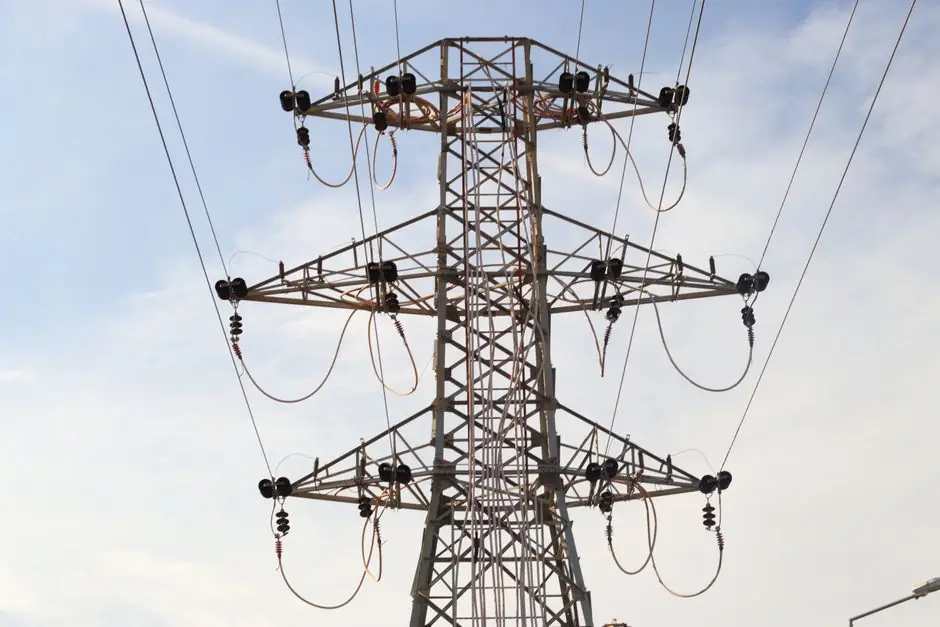
Grid-equipment cost inflation has added tens of billions to U.S. utility capex since 2020, with key transformer and switchgear prices outpacing both PPI and CPI. Distribution investment alone nearly doubled to $104B in 2025, while lead times stretched from under 12 months to 3–4 years on critical eq
Battery-grade lithium carbonate closed Q3 2026 at US$19,025/t (RMB127,750/t) on an EXW China basis, a 20.8% quarter-over-quarter drop and 36.7% below the May 12 two-year high of US$30,032/t (RMB201,000/t).
Connecting new U.S. data centers needs an estimated $3 trillion to $8 trillion in cumulative capital through 2030, with grid-side upgrades alone rivaling IT capex as interconnection queues, transformer lead times, and behind-the-meter generation all collide.
IE5 motors cut motor losses by 30-40% versus IE3, translating to roughly 10% lower energy use on a typical pump load profile and up to 20% on quadratic-torque loads like fans and centrifugal pumps. Payback typically falls in the 1-3 year range for continuous-duty industrial applications.
An AI training server such as the Nvidia DGX H100 carries roughly 2 TB of DDR5 DRAM per system, about double the ~1 TB found in a high-volume general-purpose CPU server, while a 480 GB HBM stack rides alongside the eight GPUs on the same board, pushing total addressable memory past 5 TB per node.
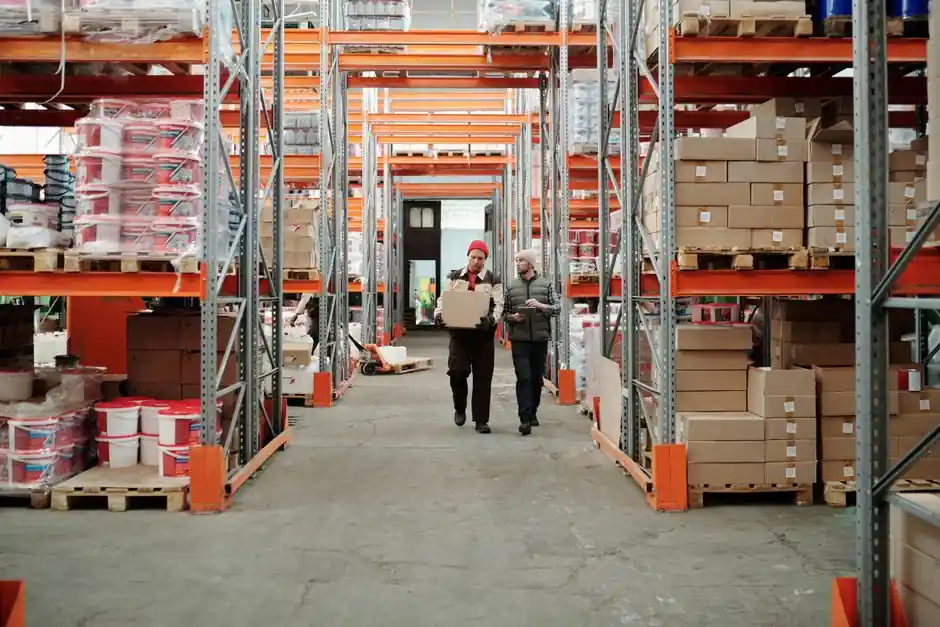
Warehouse automation costs span from $50,000 for a single vertical lift module to $5–15 million for a highly automated facility, with most mid-sized projects landing between $500,000 and $5 million. The cost per square foot typically sits in the low double digits to roughly $150 depending on equipme
The global shipbuilding orderbook reached 7,802 vessels representing 501,265,487 DWT at the end of August 2026, with merchant orderbook-to-fleet ratios ranging from roughly 30% for bulkers to over 70% for large tankers. On the naval side, the U.S. fleet counts 230 active ships with 80 more on order,
Approximately 2,017 exabytes of nearline HDD capacity will ship in 2026, with nearline drives accounting for around 96% of all HDD exabytes shipped, driven by AI hyperscaler demand that has pushed nearline supply to a fully allocated state through 2026.
AI is now compressing battery and alloy discovery timelines from years to months, with the AI in Materials Discovery market valued at USD 536.4 million in 2024 and projected to reach USD 5,584.2 million by 2034 at a 26.4% CAGR. Specialized LLMs, ML screening of candidate chemistries, and high-throug
Lab-grown diamond retail prices fell about 88% from January 2020 to early 2026, with a one-carat round brilliant dropping from roughly $3,410 to about $409 at direct-to-consumer pricing. That collapse has dragged natural 1-carat prices down ~26% from 2022 and pushed industrial-grade polycr
Global utility grid spending is set to reach about $550 billion in 2026, up nearly 20% year on year per the IEA, while U.S. investor-owned utilities plan a record $240 billion in 2026 capex, with sector spend projected to rise at a low- to mid-teens annual rate through 2030.
Gate-all-around (GAA) transistor revenue reached USD 764.04 million in 2026, up from USD 677.10 million in 2025, and is projected to USD 2,008.25 million by 2034 at a 12.84% CAGR, with nanosheet architectures holding 55% of 2024 share and 3nm/2nm nodes at 40%.
U.S. import tariffs imposed since January 2025, including a universal 10% baseline, 50% on steel and aluminium, and 25% on autos, are pushing manufacturers to reshore, nearshore to Mexico and Canada, or reroute through tariff-quota partners such as the EU, Japan, and the UK, with cost passed to impo
High Bandwidth Memory (HBM) captured roughly 50% of SK Hynix's HBM-segment revenue share in Q2 2026, down from 64% a year earlier, as Samsung's HBM3E/HBM4 ramp pushed its share to 33% and Micron held 18%. With 2026 HBM revenue tracked near US$54.6–60 billion on AI accelerator demand, HBM is the fast
HBM4 contract pricing clears $36/GB while 32GB DDR5 kits trade at $429-$650 in October 2026, putting HBM at roughly 2-3x DDR5 per gigabyte on a factory-gate basis, with HBM3E renewing at $13-$18/GB and HBM4 expected to roughly double to $36.11/GB into 2027 supply.
Specialty chemicals destocking in the US and Europe is effectively over by Q2 2026, with inventories rebalanced and ACC tracking 2026 specialty output as essentially flat rather than contracting. The cycle has shifted from withdrawal to a narrow band of stability driven by cost discipline, selective
The global ground improvement equipment market was valued at US$241 million in 2025 with a 2032 forecast of US$301 million, while adjacent service and technology markets show CAGRs of 6.3-6.8% through 2033-2034.
Grid-scale transformer market 2026: total $65.7B growing to $96.8B by 2033 at 5.7% CAGR, with high-voltage power transformers at $25.69B (6.6% CAGR), medium-voltage at $22.58B (6.97% CAGR), and large power units above 500 MVA dominating GSU demand. Asia-Pacific holds 47–48.9% of global revenue, whil
UHP grade graphite electrode 600mm prices in Q1 2026 ranged from 2026 USD/MT in China to 4139 USD/MT in the USA, with the UHP grade commanding 70.11% of the 2025 market and forecast expansion supported by EAF steel growth. Cost drivers in 2026 are needle coke supply, energy, and freight, with landed
The 2026 GPU value chain is bifurcating: TSMC CoWoS advanced packaging is fully allocated through mid-2027 with a 1.4–1.6 demand-to-supply ratio, while secondary-market RTX 3090 cards and structured residual-value underwriting are absorbing demand the primary market cannot deliver, against a US$102.
On-demand H100 80GB cloud rentals ranged $1.71 to $10.98 per GPU-hour across 52 tracked providers as of October 2026, with the cheapest listing at Gcore and a market median near $3.23. Last-released GPUs (B200/B300/MI300X/RTX 5090) saw median prices climb from $2.12 to $4.72 per GPU-hour between Oct
Electronics gold demand rose 4% y/y to 68.3t in Q2 2026, the strongest two-quarter run since 2021, driven by AI infrastructure. AI-linked high-end chips, WiFi 7, EV lighting, and PCB demand more than offset consumer-electronics weakness.
Grid-scale turnkey BESS prices in 2026 cluster around $117/kWh global average, with 4-hour LFP systems ranging $90–$334/kWh by region and chemistry, while China sits at $73/kWh versus $219/kWh in the US.
Grid-forming inverter adoption accelerated in 2026 as US grid codes formalized interconnection requirements and utility-scale battery storage pilots expanded in ERCOT and CAISO. Market estimates range from USD 790M to USD 1,850M in 2025, with US growth forecast above 22% CAGR through 2035.
The grid-enhancing technologies (GETs) market is projected to grow from USD 3.77 billion in 2026 to USD 14.30 billion by 2035 at a 15.97% CAGR, with dynamic line rating (DLR) and advanced power flow control (APFC) leading deployment on congested U.S. transmission corridors under FERC Order 881.
Global gas turbine orders reached a record 38 GW in Q2 2026, with combined OEM backlogs of roughly 220 GW (GE Vernova 116 GW, Siemens Energy 69 GW, Mitsubishi 35 GW) running 1.6–1.8 years ahead of 60–70 GW of annual factory output, pushing new-unit lead times to five years and prices toward $600/kW
US investor-owned and cooperative utilities are on track for roughly $1.3T of grid capital expenditure over 2026-2030, with distribution absorbing $104B in 2025 alone, 87% concentrated in poles, conductors, transformers and station equipment. Lead times on transformers, breakers and switchg
The global green steel pipeline sits at roughly 46 Mt/year of announced primary capacity by 2050 (28 Mt green steel + 18 Mt green iron) versus 270,000 t/yr of green iron and 60,000 t/yr of green steel actually operating, per LeadIT (Feb 2026). Even adding GEM's 846 Mtpa of developing steelmaking cap
Green methanol offtake contracts in 2026 are clearing at roughly 70 to 150 USD per tonne above VLSFO parity, layered on bio-methanol production costs of about 900 to 1,400 USD per tonne and e-methanol at 1,600 to 2,400 USD per tonne, with FuelEU Maritime and EU ETS penalties driving the premium floo
Unsubsidized green hydrogen averaged $2.50–$7.00/kg globally in 2026 against grey hydrogen at $1.20–$2.50/kg, so the green premium remains 2–4x even after IRA tax credits up to $3/kg and the EU Hydrogen Bank. Spot indices in Europe printed USD 7.67/kg in September 2026, well above the $1/kg DOE Hydr
Synthetic graphite anode prices have dropped roughly 20% year-on-year, tipping below natural graphite for the first time in over three years and flipping the cost logic for cell makers. The synthetic-vs-natural decision in October 2026 is no longer a one-line cost call; it now hinges on tariff expos
Glass substrates for advanced packaging entered pilot-line qualification in 2026, with Intel targeting launch readiness between 2026 and 2030 and the addressable market forecast to grow from USD 2.2B to USD 4.7B by 2035 at an 8.9% CAGR.
Float glass in 2026 is split: China averaged USD 1,190/MT EXW in July 2026 (USD 1,306/MT September), Germany USD 800/MT EXW August, USA USD 1,000/MT. Solar-grade low-iron float is the fastest-growing slice at 8.01% CAGR. Buyers should treat regional basis, energy pass-through, and
Container glass demand is on track from US$ 67.1 B in 2025 to US$ 103.3 B by 2036 at a 4.0% CAGR, while flat glass output climbs from 83.17 Mt (2025) to 86.48 Mt in 2026 toward 105.14 Mt by 2031, with specialty glazing and electric/hybrid melting reshaping capacity decisions through 2026.
North American glass fiber prices rose 13.27% quarter-over-quarter in Q2 2026 on feedstock and logistics pressure, with the Fiberglass Roving market valued at USD 11.11B in 2026, projected to USD 15.51B by 2030 at an 8.7% CAGR.
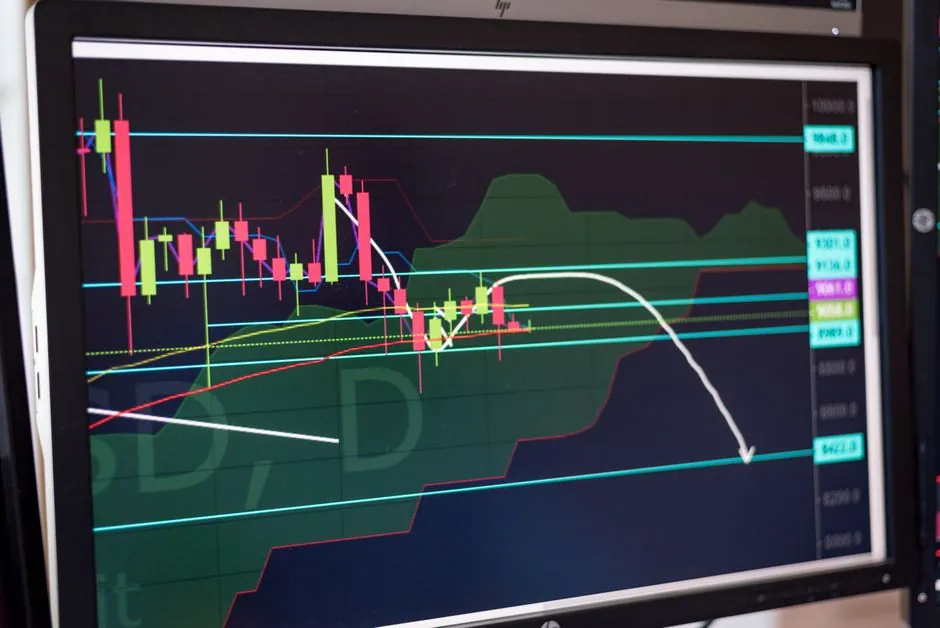
Germanium prices reached roughly $9,866 per kg on October 9, 2026, up 69.70% year-to-date, with a Q2 2026 CIF Hamburg jump near 30.60% and a S&P Global forecast of a 177 t supply gap for 2026, driven by Chinese export licensing and tight ex-China refining capacity.
U.S. geothermal nameplate capacity hit 3,969 MWe in 2024, an 8% rise over 2020, while the first U.S. commercial enhanced geothermal system (EGS) plant is scheduled to come online in June 2026 and global market value is projected to climb to USD 21.22 billion by 2035 at a 9.7% CAGR.
The global material handling equipment market is projected to reach US$280.5 billion in 2026 and US$424.6 billion by 2033 at a 6.1% CAGR, with conveyor systems and AMR/AGV fleets anchoring gearmotor demand for conveyor and material handling applications.
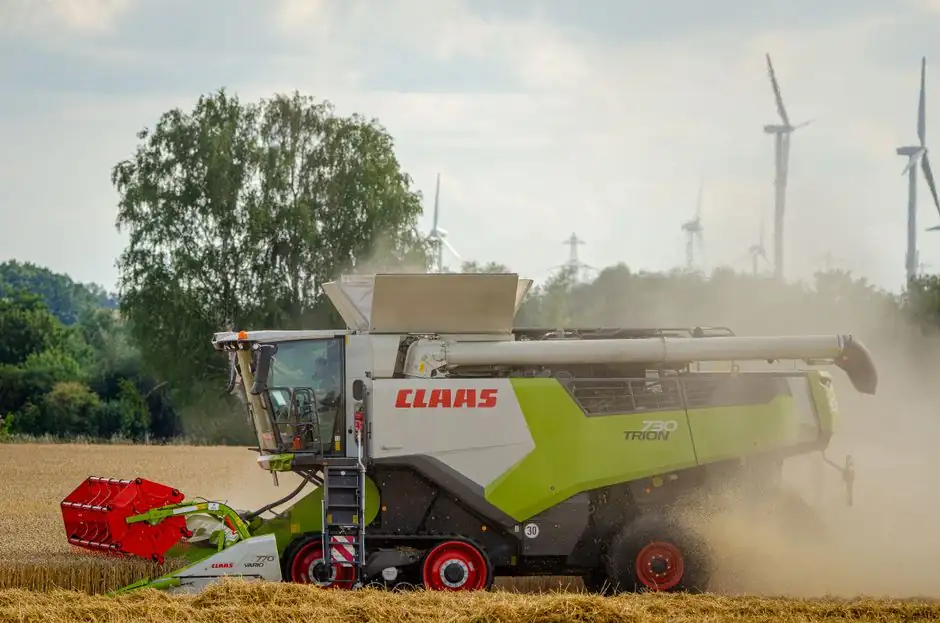
Aeroderivative gas turbines currently price at roughly $1,000 to $1,200 per kW installed for the equipment, against heavy-duty frame units at $700 to $1,100 per kW for full 250 MW+ EPC scope. Aeroderivatives cost more but deliver 34 to 42 percent simple-cycle efficiency and faster start profiles.
Fixed gas detection held a 64.4% share of the gas detection equipment market in 2025, while portable units captured the rest and are forecast to grow at 7.8% CAGR through 2030. Specifiers choose fixed systems for continuous area coverage at known hazard points and portables for personnel protection,
Power GaN devices are projected to grow at a 35% CAGR to USD 3.5bn by 2031, with AI data centers, EV onboard chargers, and 48V automotive architectures leading demand beyond legacy consumer fast-charger sockets.
Galvanized coil landed prices in 2026 sit around $1,050–$1,300/t in the U.S., $850–$980/t FOB China, and €1,150–€1,350/t in the EU, with zinc coating adding roughly $80–$120/t on top of HRC. Drivers are LME/SHFE zinc, HRC substrate, Section 232 duties, and a new Indonesia anti-dumping probe on Chine
China's US-targeted gallium export ban is suspended until 27 November 2026, yet spot prices diverge sharply: Chinese domestic SMM benchmark sits near $229/kg while retail-grade material trades above $2,800/kg, a 60%+ YTD rise. Sourcing engineers should plan for 12-24 month price volatility.
Fusion crossed from lab to procurement in 2026: the U.S. NRC proposed a dedicated byproduct-material framework, the EU strategy landed in H2, and an inaugural Fusion Industry Association supply-chain trade show ran in June 2026, drawing cross-sector industrial suppliers.
Functional safety spending in 2026 is anchored by IEC 61508 and ISO 26262, with multiple research houses valuing the market between USD 5.18B and USD 8.73B and projecting 6.1–11.7% CAGRs, driven by oil & gas shutdown systems, EV/ADAS software, and Industry 4.0 retrofits.
Global fuel cell vehicle sales reached 16,011 passenger cars in 2025, up 24.4% year-on-year, with commercial trucks and heavy-duty applications driving forecasts of USD 5.5–19.24 billion in 2026 market value. Asia-Pacific, led by China and South Korea, accounts for over half of deployments, while hy
FRP panel price in 2026 spans $0.90 to $10+ per square foot, with retail wall panels at $0.90–$2.00/sq.ft. and chemical-resistant vinyl ester grades climbing to $5–$10+/sq.ft., driven chiefly by resin system, thickness, and order volume.
TSMC and Samsung raised advanced-node foundry prices 3-15% across 2026, with 2nm wafers tracking near $30,000 and mature 8-inch utilization climbing to 85-90%, reshaping chip cost models for AI and industrial buyers.
Foundry coke prices in 2026 are anchored to FOB metallurgical-coke quotes of $294.81–$362.01/MT by region, with the global foundry-coke segment projected to add $13.16 billion in revenue by 2030 at a 4.73% CAGR.
Electric forklifts now exceed 70% of new truck sales across Europe, and lithium-ion is on track to overtake lead-acid inside this decade as cost-per-cycle flips: lead-acid averages ~1,500 cycles, while Li-ion packs deliver 3-shift uptime on a 1 to 2 hour fast charge. Multi-shift fleets running 24/7
Global food processing equipment spend reaches USD 132.7 Bn in 2026 and is on track for USD 200.9 Bn by 2033 at a 6.1% CAGR, with meat, dairy, and bakery lines driving the bulk of order activity as processors retool for FSMA compliance and ready-to-eat growth.
U.S. food and beverage manufacturers announced $6.75B in Q2 2026 project construction starts, with capex tilting from greenfield to modernization. Renovation and equipment upgrades drove roughly half of March 2026 capital investment, per Industrial SalesLeads data.
PTFE, PVDF, and FKM prices in 2026 sit inside a US$11.8B global fluoropolymer market, with FKM up roughly 5% in Q1 2026 and supply tightening as the EU REACH PFAS restriction, covering PTFE, PVDF, ETFE, FEP, PFA, and FKM/FFKM (93% of EU fluoropolymer use), edges toward decision. PTFE still dominates
The 2026 global flow meter market is sized between USD 9.0 billion and USD 12.14 billion across published reports, with magnetic/electromagnetic technology holding 24–32% share, Coriolis generating roughly USD 1.55 billion (around 22%), and ultrasonic tracking the fastest CAGR at 7.3% through 2035.
Global floating solar capacity is scaling fast in 2026, with the market valued at USD 11.23 billion and forecast to reach USD 86.51 billion by 2035 at a 25.86% CAGR, led by Asia-Pacific and increasingly North American utility-scale builds. Annual additions remain dominated by conventional utility PV
Floating offshore wind entered a delivery-focused commercialization phase in 2026, with conference programmes pivoting from demonstration to serial production, port-based manufacturing and CAPEX/OPEX reduction, while market forecasts range from USD 8.87B to USD 25.4B by 2030-2031 at 34.1% CAGR[
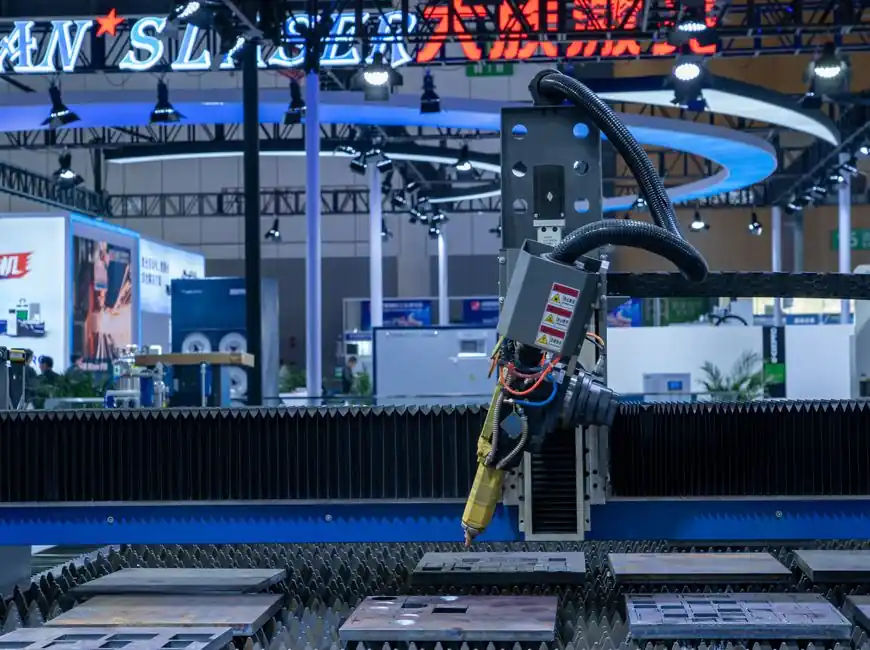
In 2026, fiber laser cutting machine prices run roughly $15,000–$50,000 for 1–3 kW entry systems, $50,000–$200,000 for 3–6 kW mid-range, and $150,000–$600,000+ for 12–30 kW automated cells, with laser power adding about $8,000–$12,000 per kW and total ownership cost adding 20–40% per year on top of
Global plastic extrusion line demand was valued at USD 8.28 billion in 2025 and is projected to reach USD 14.11 billion by 2034 at a 5.9% CAGR, with Asia Pacific holding 42% share. Pipe, profile, and film extrusion lines dominate the build pipeline, driven by PVC regulation shifts, multilayer packag
BEV share of global EV sales dropped from 90% to roughly 80% as PHEV sales climbed sharply through 2026, with Europe posting record BEV growth (36% YoY in Q1) while China contracted 20% on BEVs and 31% on PHEVs. In the U.S. post-credit, hybrids now outsell plug-ins by more than 2:1 at retail.
ASML targets 60+ Low-NA EUV shipments and roughly 10 High-NA EXE:5200 systems in 2026, with each High-NA tool priced near $380–400 million. By September 8, 2026, Intel had run over 1 million 300 mm wafers through High-NA scanners, anchoring select Panther Lake layers, while TSMC deferred High-NA to
Epoxy resin prices in 2026 split sharply by region, with India at USD 1.97/kg, Northeast Asia at USD 2.21/kg, North America at USD 3.71/kg, and Europe at USD 4.68/kg, while wind energy and electronics drive 5.0% global CAGR growth to USD 18.07 billion by 2033.
On-premises AI infrastructure in 2026 reaches breakeven against cloud APIs in 4–12 weeks at sustained >20% GPU utilization, delivering 10–18× lower cost per million tokens; cloud wins on speed-to-first-inference, hybrid routing wins on TCO.

By 2030 the global semiconductor industry will need more than 1 million additional skilled workers, while combined engineer and technician shortfalls in the US alone are projected at 59,000–146,000 by 2029, reshaping how power, fab, and ATP capacity gets built. Power and clean-energy firms are expos
End-of-line (EOL) packaging automation demand is expanding on three independent tracks in 2026: equipment USD 7.02 B, machinery USD 5.92 B, and total EOL USD 55.65 B. Labour shortages and EU PPWR 2025/40 are turning palletising, case packing, and stretch wrapping from optional upgrades into baseline
The global continuous emission monitoring systems (CEMS) market is sized at USD 1,613.25 million in 2026, projected to reach USD 2,376.83 million by 2035, with CEMS holding USD 3.17 billion of the USD 3.9 billion emission monitoring system (EMS) total in 2023.
The 2026 global elevator and escalator market is sized between USD 107.1 billion and USD 136.3 billion across major forecasts, while the modernization sub-segment is expanding at roughly 7-8% CAGR, the fastest of any business line.
Alkaline electrolyser CAPEX sits at $600–$1,000/kW from Chinese suppliers and $1,800–$2,300/kW for Western systems, while PEM ranges $900–$1,500/kW (China) to $2,000–$2,550/kW (Western), per 2026 industry data. The DOE 2026 PEM target is $250/kW uninstalled, $2/kg H2.
800V SiC inverters and axial flux motors are converging in 2026 electrified powertrains, with axial flux machines delivering higher torque density and a pancake form factor while SiC enables fast charging and 40%+ thermal-efficiency DHEs in NEV/REEV platforms.
US retail electricity prices are forecast to rise 3–5% year-on-year in 2026 on tight supply, hyperscaler data-center load, and electrification, while global demand growth accelerates to 3.6% in 2026 and 3.8% in 2027. Industrial demand response, automated load-shed and behind-the-meter ass
GOES trades at US$4.29/kg in North America and US$1.63/kg in Europe as of September 2026, while NGOES remains under USITC five-year review from China, Germany, Japan, South Korea, Sweden, and Taiwan initiated 1 December 2025. Transformers, motors, and EV traction drive diverging price paths; the two
U.S. switchgear producer prices rose 13.8% year-on-year to August 2026, power transformer costs are up roughly 77% since 2019, and power-line cable costs have roughly doubled in the same window. Medium-voltage switchgear is quoting 52 to 80 weeks and substation transformers 75 to 110 weeks, pushing
US electrical equipment PPI hit 254.92 in August 2026, a record high on the Dec 2003=100 index, running ahead of general goods PPI inflation of about 2.8% year over year. Energy-driven input pressure and motor/generator price jumps explain most of the spread over headline producer prices.
Hyperscaler M&A in 2026 is pivoting from buying compute to buying grid assets: Google acquired Intersect Power, KKR and ECP announced a $50B data-center-plus-generation partnership, and Bring-Your-Own-Power sites are listing at 200 MW scale, with U.S. data-center demand projected at 35-45 GW by 2030
North American EMS book-to-bill hit 1.36 in April 2026 with shipments up 3.1% year-over-year, while capital goods overall sits at 1.3x with power electronics at 1.5x, gas turbines at 1.9x, and HVAC at 1.7x. SEMI's semiconductor equipment book-to-bill has been discontinued since 2017, leaving EMS and
Electric motor prices in 2026 are climbing 10-20% on standard product lines, driven by copper near $12,780/tonne, Section 232 steel tariffs at 50%, and a weak euro. Cost is set by nine dials, not one.
Electric arc furnaces are projected to capture a growing share of global steel output through 2034, with the equipment market expanding from US$3.95B–4.00B in 2025–2026 toward US$5.7B–6.1B by 2033–2034 at a 4.8–6.4% CAGR. Scrap quality and availability now gate that growth: regions with mature scrap
Electric actuators held 48% of the global USD 76.5 billion actuator market in 2026, with the segment growing at a 5.8% CAGR versus 5.17% for automotive pneumatics, driven by Industry 4.0 integration, EV throttle/brake/steering demand, and a measurable shift away from compressed-air systems in proces
Global Edge AI server demand is scaling from a USD 2.7 B 2024 base toward USD 26.6 B by 2034 at a 25.7% CAGR, with manufacturing, retail, automotive and healthcare leading. Plant-floor and store-level inference, not data-center training, is shaping the 2026 buy cycle.

The edge AI chip market is valued at USD 26.14 billion in 2025 and is forecast to reach USD 58.90 billion by 2030 at a 17.6% CAGR, with industrial and enterprise devices the fastest-expanding segment at a 24.1% CAGR through 2031.
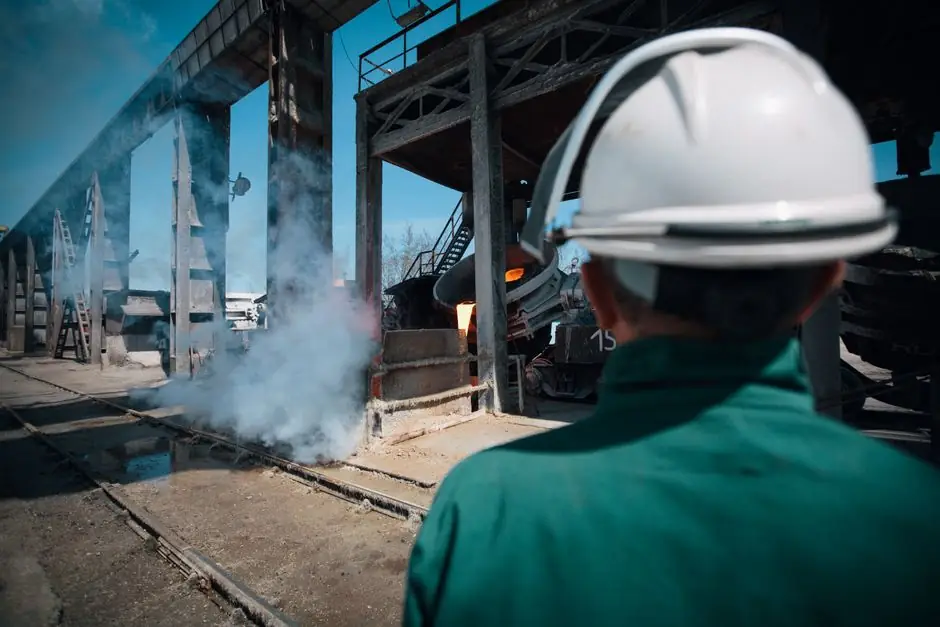
Electric arc furnaces produced 30.3% of global crude steel in 2025 per worldsteel, with the EAF share rising from roughly 27% in 2019 toward a forecasted 32.5% by year-end 2025, and further growth expected in 2026 as DRI-EAF capacity comes online in MENA, India, and ASEAN.
Global e-waste recycling is a USD 44.84 billion market in 2026, with metals recovery holding 51.62% share; only ~20-22% of e-waste is formally collected, while the metal-recovery sub-segment is forecast to grow from USD 4.6 B (2026) to USD 10.8 B by 2036 at 8.90% CAGR.
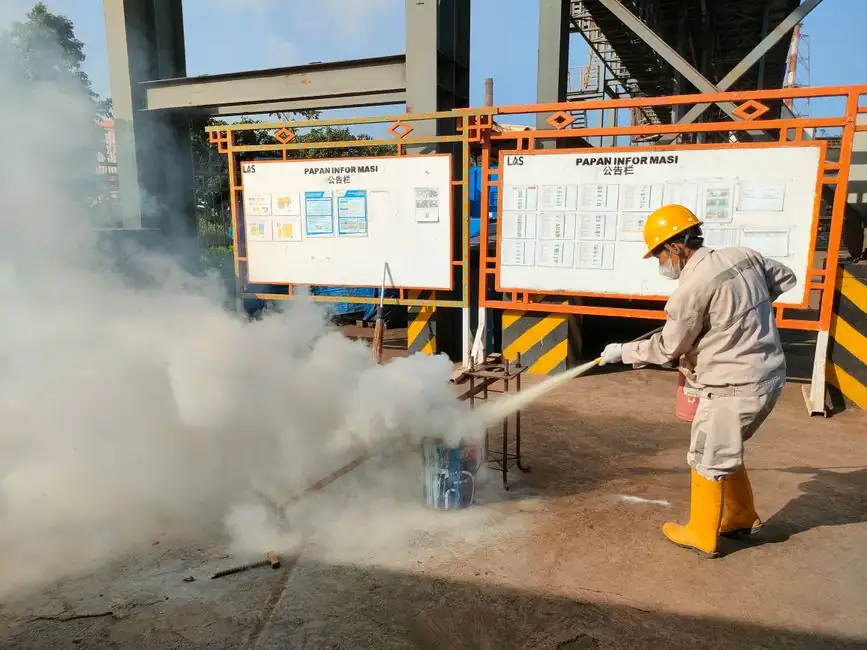
NFPA 660 became enforceable on January 1, 2026, consolidating six legacy dust standards into one framework and shifting the industrial dust collection market toward mandatory DHA-led compliance. With the market projected to grow from USD 7,814.45 Billion in 2025 to USD 13,122.5 Billion by 2035 at a
The global dry-type transformer market is valued at USD 18.37 B in 2026 and is forecast to reach USD 24.18 B by 2031 at 5.65% CAGR, with data center and renewable installations driving oil-free demand across all major regions.
Global DRAM wafer capacity is on track to reach roughly 1.67 million 300mm wafers per month exiting 2026, up about 6-8% year over year, with SK hynix 1c and Samsung 1c at P4 driving most of the net adds while Micron's HBM-specific 60,000 wafers per month expansion reshapes mix.
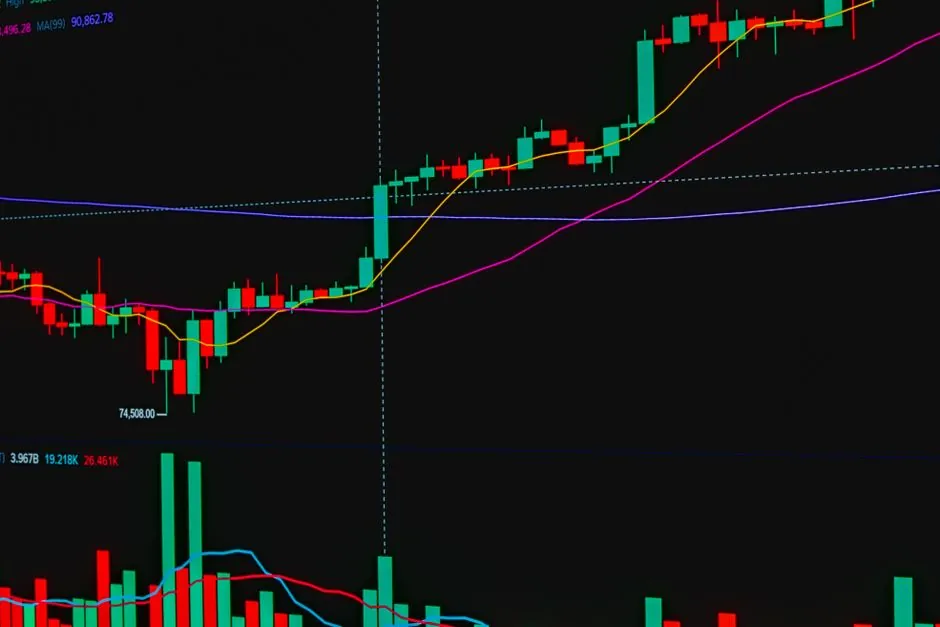
DRAM spot prices in early September 2026 sat well above contract benchmarks, with DDR4 8Gb 3200 near $43-44 and DDR5 16Gb averaging about $54 per chip, while Q4 2026 contract forecasts cooled to roughly +0-5% QoQ. The chip-module inversion and record spot prints point to a bifurcated cycle: HBM and
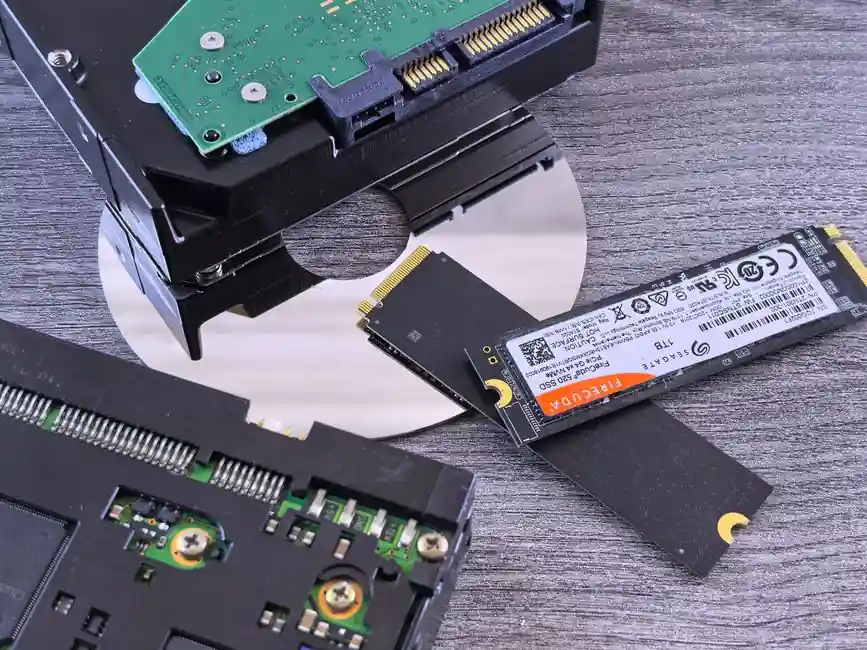
DRAM 1b and 1c node migration is concentrated at Samsung, SK Hynix, and Micron in 2026, with SK Hynix targeting over 50% of domestic general-purpose DRAM output on 1c by year-end. Tight EUV tool lead times of 12–18 months constrain how fast the three majors can rebalance wafer mix.
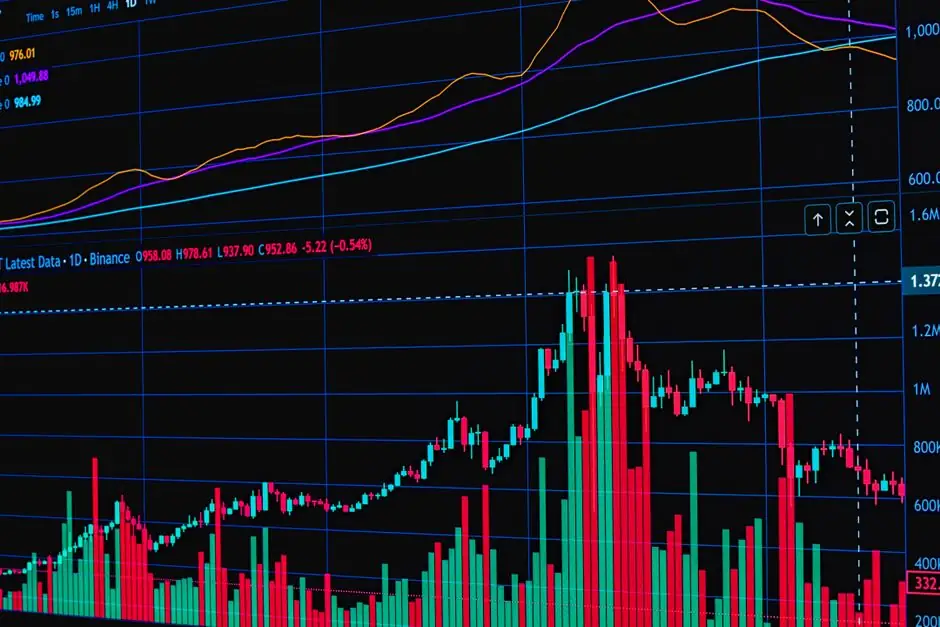
Q3 2026 DRAM contract prices for DDR4 8Gb are set to rise more than 50% quarter-on-quarter, while DDR5 16Gb spot prices are also climbing fast; DDR4 remains cheaper per gigabyte but its supply-demand gap could persist up to two years as Samsung, SK Hynix and Micron shift wafer capacity to HBM and DD
Distribution transformer price in 2026 spans roughly $7.2–$22.0 per kVA factory reference, driven by LME copper near $14,185/ton, DOE 2024 efficiency phasing, and 50% U.S. electrical-steel tariffs. Three quotes on the same 1500 kVA pad-mount diverged 31% in 2026.
U.S. grid investment over the coming decade is split roughly 37% transmission and 63% distribution (~$1 trillion), while global transmission spending is forecast to grow at nearly twice the distribution rate through 2030 on a $5.8 trillion base.
Direct-to-chip cold plate market 2026 estimates cluster between USD 1.26B and USD 3.4B depending on scope, with CAGR projections of 7.0% to 20.94% through 2030-2035. Data centers drive 50% of demand; single-phase designs hold 45-70.4% share; copper dominates material choice.
Direct air capture (DAC) costs span $152–$1,000 per tonne of CO2 in 2026, with operational plants running $400–$600/t FOAK, against a $100/t long-term target needed for gigaton scale by 2050.
Digital substations built on IEC 61850 process bus replace copper point-to-point wiring with fiber Ethernet between merging units and IEDs, with IEC 61850-9-2 as the globally accepted process-bus standard. Adoption is accelerating after utility station-level rollouts, and STPA-based logical selectiv
U.S. on-highway diesel reached $6.382/gal on September 28, 2026, up 70% year-over-year, pushing the AGC nonresidential input PPI up 1.7% in March alone and reshaping construction cost models.
Diesel genset price per kW in 2026 ranges from roughly $180 to $800/kW commercial, with absolute prices scaling non-linearly across power bands. Used 500–800 kW units land at $42K–$95K; 1 MW industrial sets run $125K–$220K, and 7–15 kW residential models sit at $5,500–$11,000.
Diesel gensets held 72.6% to 81.24% of the 2025 data-center generator market, and U.S. data-center diesel capacity nearly tripled from 20 GW in 2018 to 55 GW by 2024, with hyperscalers and large facilities (Tier 3/4, above 2 MW units) driving the next procurement cycle.
Desalinated water in 2026 ranges from €1 to €6 per cubic meter ($0.50 to $5.00 per m³ across sources), with solar-powered reverse osmosis at the low end and diesel-driven thermal systems at the high end; total cost of ownership is dominated by energy at 60-70% of operating expense, and a 100 m³/day
Industrial demand response capacity reached ~75 GW across all sectors in 2026, with the global market valued at USD 39.5 billion and a 12.2% CAGR toward 2036. Curtailment payments of $50-200/MWh and FERC aggregator reforms effective May 2026 are reshaping how plants participate.
The DCS market for process industries is valued at USD 18.89 billion in 2026, with process control systems holding a 58% share; a 5.1% CAGR takes the market to USD 29.6 billion by 2035, driven by oil and gas, chemicals, and power generation demand.
DC microgrids in industrial plants are growing at a 17.0% CAGR through 2035, the fastest of any microgrid topology, even though AC units still hold 58% of 2026 revenue. Battery-plus-solar EsM hybrids at $140-190/kWh and 380 V LVDC buses standardized under IEC 63290 are reshaping plant power architec
Data center UPS revenue is tracking 41-46% of the global UPS type mix in 2026, with double-conversion on-line units alone at 41.06% segment share and large data centers at 44.10%. Market size estimates for 2026 range from USD 4.48B to USD 8.2B depending on scope.
Data centers could claim up to 40% of the electrical-equipment market under accelerated AI-build scenarios, with medium-voltage transformer lead times crossing 160 weeks by Q1 2026 and a USD 8.9-9.48 B data-center transformer segment in 2026.
Average data center rack density reached 27 kW in 2026, up 69% year-over-year, with AI training clusters running 40–132 kW and next-generation GPU racks targeting 250–900 kW. The global data center rack market is valued between USD 2.90 billion and USD 7.26 billion in 2026 depending on scope, with h
2026 data center construction runs $8M–$12M per MW for standard facilities and $15M–$20M+ per MW for AI-optimized builds, with electrical systems consuming 40–45% of the budget and Tier IV redundancy adding up to 40%.
Liquid cooling in 2026 is forecast to capture 55% of the data center cooling segment by type (US$ 3.1 Bn+), while only 19% of surveyed facilities report active deployment today, exposing a sharp gap between plan and install.
Ethernet is on track to dominate AI back-end scale-out networks, with AI scale-out Ethernet revenue projected above $100B by 2030, while 800G ports become the floor for new AI clusters and data center switch spend reaches $20.81B in 2026.
US data center electrical equipment demand jumps from $20B in 2026 to $65B by 2030, with AI data center switchgear alone forecast to grow from $2.26B to $9.02B at 11.8% CAGR, while transformer lead times stretch to 24-48 months and reshape project underwriting.
U.S. data center operators are placing 2026 standby orders against 52+ week diesel lead times, 27 GW of Virginia-permitted diesel, and Tier 4 cutoffs that arrive December 1, 2026, while natural gas is winning where pipeline access and continuous-run air permits allow.
U.S. data center construction hit a $49.5 billion seasonally adjusted annual rate in 2026, overtaking general office at $43.4 billion and reshaping nonresidential building priorities. Cushman & Wakefield tracks a $2.3 trillion pipeline with $492 billion under active build, while the Census Bureau re
For 2026 data center UPS battery cabinet procurement, lithium-ion (LFP-dominated) wins on weight, cycle life, and TCO over 10-15 years, while VRLA still holds ~40% market share on safety simplicity and upfront cost.
U.S. data center backup power is bifurcating in October 2026: natural gas reciprocating gensets and aero-derivative gas turbines are taking prime-power roles to bypass 5+ year grid lead times, while lithium-ion UPS batteries handle sub-second ride-through but cannot economically stretch to multi-hou
Hyperscaler AI capex guidance for 2026 sits at $732.5 billion, 158% above early forecasts, with consensus for 2027 near $934.5 billion. A 10-20% capex pullback would first dent networking, memory, and high-bandwidth packaging supply, not GPU silicon orders already booked for delivery.
Data centers drove nearly 60% of US corporate PPA volume in 2024, up from around 50% the prior year, with Europe already at a third of PPA demand. AI workload growth and 24/7 clean-power needs are pulling hyperscalers ahead of heavy industry in long-term renewable contracting.
US core capital goods orders rose 1.6% MoM in August 2026 to $100.5 billion, accelerating YoY growth to roughly 14.1% and signalling sustained equipment investment. For capital planners, this is a strong forward indicator, with unfilled orders at $1,609.4 billion confirming the backlog-to-shipment r
Copper wire rod prices diverged sharply across 2026: USA Q2 2026 averaged USD 20,097/MT versus China USD 11,839/MT, while secondary copper rod flipped to a 200-400 yuan/MT premium over futures. Cost drivers are cathode parity, scrap tax compliance, freight, and currency.
Global copper tube prices in Q4 2026 are anchored to LME copper above $12,000/ton, with HVAC demand pushing the global copper tube market to USD 39.02 billion in 2026 at a 3.50% CAGR. Cost is driven primarily by raw cathode, fabricated-product tariffs, and refrigerant-grade tube specifications.
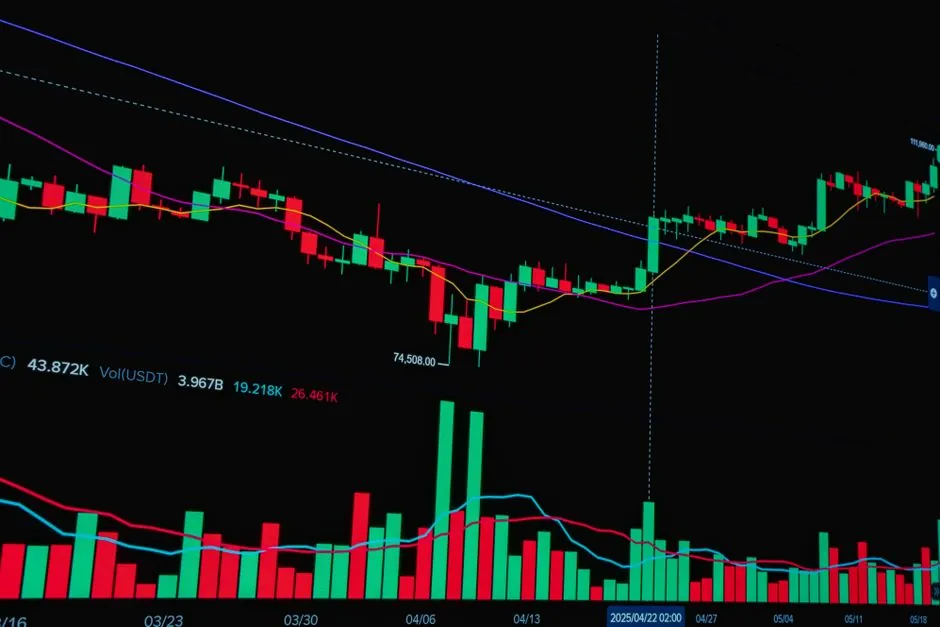
LME copper broke USD 14,500/t intraday in January 2026 and set a fresh all-time high of USD 14,533/t on 7 September 2026. The 2026 rally is driven by US tariff stockpiling, AI-data-center demand, and a 600 kt 2025 surplus being absorbed, with Goldman Sachs expecting the price above USD 13,000/t to b
Global copper mine capacity rose 3.8% in H1 2026 while production fell 1.1% to 11.34 Mt and utilization slid from 81.0% to 77.1%, exposing a concentrate bottleneck as China holds roughly 50% of smelting capacity.
The 2026 refined copper market is heading into a 150,000-tonne deficit per ICSG, while sell-side banks cluster around 330,000 to 600,000 tonnes, with concentrate supply remaining the binding constraint through the decade.
Grid, EV, and electronics sectors are pulling copper demand higher in 2026, with LME three-month prices near $14,700/t in September and data-center new-install demand projected at 475,000 t for the year.
Global coolant distribution unit (CDU) market sizing for 2026 spans USD 1.03B to USD 11.4B depending on scope, with data center CDUs alone projected at USD 11.4B (35.3% CAGR to 2032) and broader industrial CDUs at USD 2.54B (14.3% CAGR to 2034). Rack densities exceeding 80-120 kW are driving structu
Global pharmaceutical CDMO market is sized between $104.4B and $245B in 2026 depending on scope, with biologics, ADCs, and sterile fill-finish driving capacity additions. Fujifilm, Lonza, Samsung Biologics, and WuXi Biologics lead biologics expansions through 2027.
Global containership orderbook reached ~13.1-13.3m TEU in Q2 2026, lifting the orderbook-to-fleet ratio to 38.7-39.1% against an active fleet near 33.8m TEU, a post-2010 peak driven mostly by 7,600+ TEU mainliners.
U.S. construction material costs rose 2.6% in May 2026 and 3.7% in April, the steepest monthly residential pace in three years. The ENR-based California CCCI climbed from 10,124 in March to 10,717 by September 2026, a 5.9% intra-year jump. Annual nonresidential cost inflation is running 5.6% nationa
U.S. new financed mini excavator sales fell 7.7% to 32,500+ units between June 2025 and May 2026, with Caterpillar overtaking Kubota at 23.3% share, while the global heavy equipment market tracks USD 160.11 billion in 202.
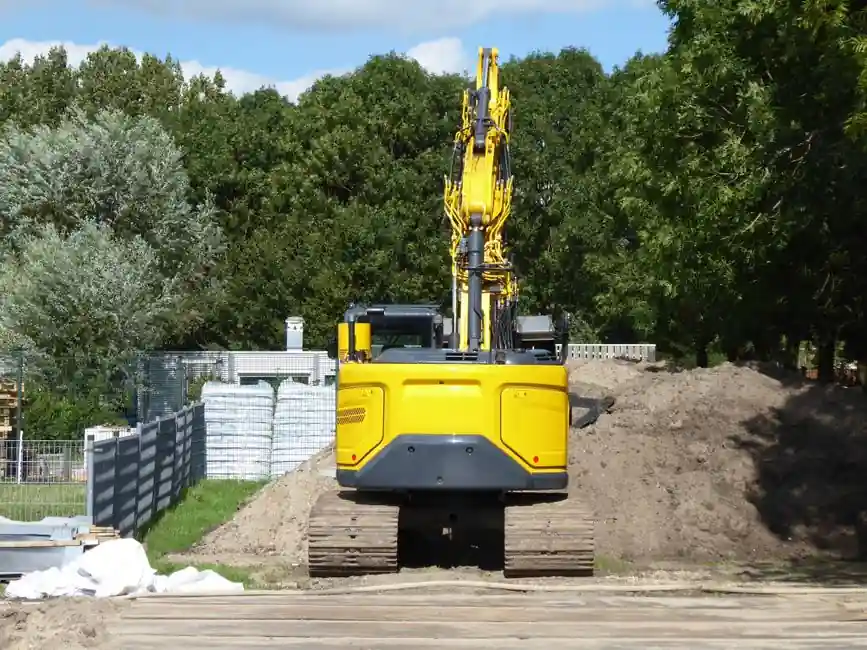
Global electric construction equipment market estimates for 2026 cluster between USD 3.81 billion and USD 69.49 billion depending on scope, with growth rates of 15.12% to 20.80% CAGR through the early 2030s. China leads regional volume, North America leads compact-equipment revenue, and battery-elec
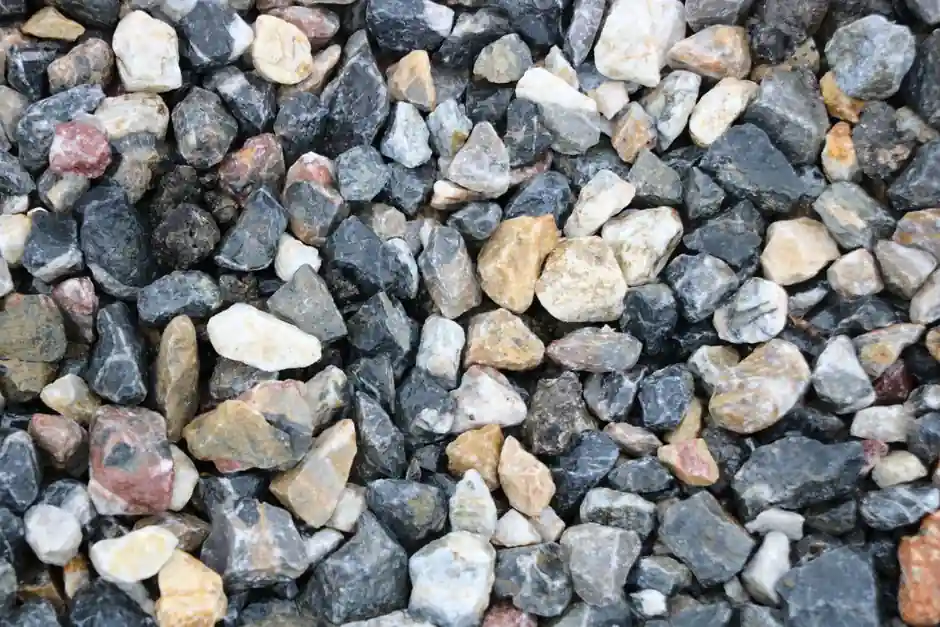
US construction sand and gravel averaged $14.50/ton in 2025 with further increases expected into 2026, driven by infrastructure, data-center, and metropolitan demand, per USGS. The 2026 benchmark market price for construction aggregates is $19.39 per ton per IBISWorld, while global market estimates
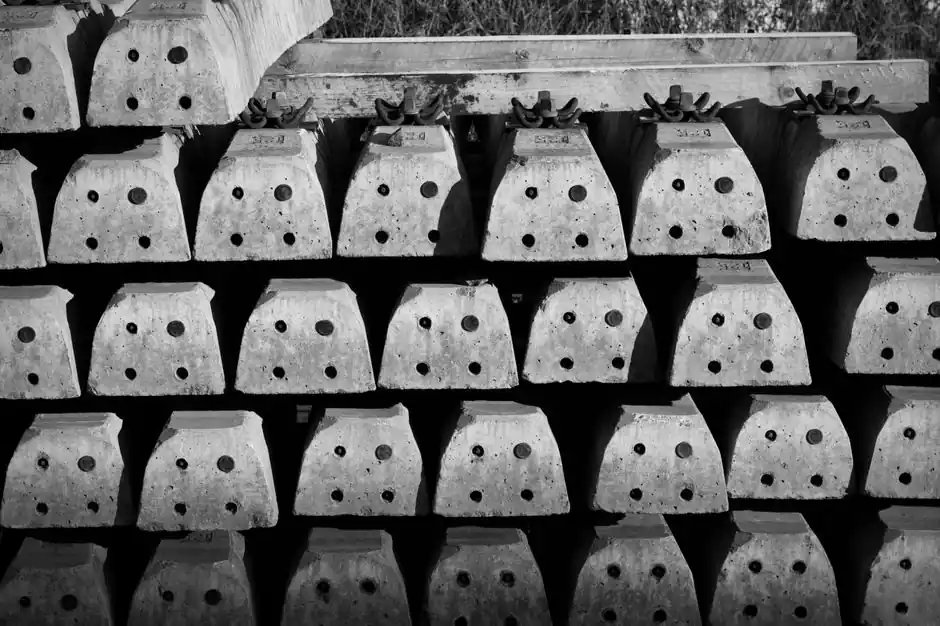
Low-carbon concrete mixes are reshaping the strength-class landscape, with Type IL portland-limestone cement (PLC), Class F fly ash, slag cement, and silica fume now competing with ordinary portland cement (OPC) for structural and pavement bids. Specification writers cite 5–10% embodied carbon cuts
Hyperscale data centers need roughly 20,000 tonnes of steel and around 45,000 cubic yards of concrete per site, translating to about 60-100 tonnes of steel and 130-270 cubic yards of concrete per MW of IT load in 2026 builds.
Commercial EV battery demand is rebounding in 2026 as electric truck deployment accelerates, with the ECV market reaching USD 108 billion and the global EV battery market valued at USD 85.9 billion in 2026.
Commercial and industrial battery storage systems in 2026 deliver a typical payback of 3-6 years, with turnkey installed costs ranging from $290 to $800 per kWh depending on system size and chemistry. LFP cells dominate at roughly $40/kWh factory-gate, while demand-charge exposure and the 30% U.S. I
Cold storage construction in 2026 is a high-cost, supply-constrained industrial segment, with ground-up U.S. builds at $150–$450/sq ft by temperature zone, a national vacancy near 3.4%, and a market projected at US$46.8 B in 2026, growing 8.4% CAGR to 2033, led by pharmaceutical cold chain and autom
Cold spray additive adoption for repair is accelerating in 2026, with the global cold spray technology market projected to grow from USD 1.2-1.29 billion in 2025-2026 toward USD 1.9-3.9 billion by 2033-2035, driven by aerospace MRO demand and solid-state aluminum landing-gear repair standards.
Coking coal closed at USD 264.50/MT on 29 September 2026, down 6.21% on the month but still 38.48% above year-ago levels. Q2 2026 regional landed prices spanned USD 255–295/MT, with India highest and the US lowest, on tight blast-furnace demand and weather-driven supply disruptions.
Entry-level 6-axis cobots sit in a US$15,000–45,000 per-unit band in late 2026, with 5 kg payload models below US$25k, while welding-class >10 kg units reach US$75,000–120,000. Total installed cost typically runs 1.5–2.0x the arm price once gripper, vision, and integration are counted.
As of September 28-29, 2026, LME cobalt metal trades near $39,140-$39,640/t (≈$17.7-$18.0/lb) while cobalt hydroxide (min 30% Co, CIF China) holds a $22.00-$23.00/lb bid-offer, leaving a sustained positive premium for the refined metal over the intermediate.
Global cobalt demand hit 276 kt in 2025, up 13% year-on-year, with EV batteries at 39% of the total, superalloys at roughly 8%, and hard metals at about 4%; the U.S. mix is superalloy-heavy at ~51%.
Cleanroom equipment demand is set to roughly double between 2025 and 2035, growing from USD 5.6B to USD 10.8–11.64B at a 7.5–7.55% CAGR, driven by semiconductor fabs, pharmaceutical biologics, and gigawatt-scale lithium battery dry rooms.

The global cleanroom construction market is valued at USD 7.73 billion in 2026 and is projected to reach USD 11.74 billion by 2030 at an 11.0% CAGR, with semiconductor and pharmaceutical demand driving ISO 4-8 build pipelines and modular delivery.
The U.S. CHIPS Act has allocated over $36B of its $52.7B appropriation across 40+ fab projects, but a hard December 31, 2026 construction-start deadline and 12-24 month schedule slippage threaten the program. The Section 48D credit is now 35% under OBBB, and the Trump administration is renegotiating
Air-cooled industrial chillers in 2026 list at $1,300–$2,000/ton installed while water-cooled centrifugal units run $1,700–$2,000/ton plus cooling-tower infrastructure; air-cooled wins on capex, water-cooled wins on kW/ton and 15-year TCO. The crossover sits around 4,000 annual operating hours.
Data center chiller market 2026: USD 5.23B base, projected 8.26% to 8.90% CAGR through 2032-2035, with North America holding 40-44.1% share and Asia-Pacific the fastest growing region at 11.5% CAGR.
Pyrolysis and depolymerization plant capacities have grown over 70% since 2024 per IDTechEx, with the global chemical-recycling market tracked at USD 13.16 Bn in 2025 and a 28.8% CAGR through 2035. Process choice is polymer-specific: pyrolysis for mixed polyolefins, depolymerization for PE
European chemical plant closures surged to 17.2 Mt of announced capacity in 2025, a six-fold increase from 2.9 Mt in 2022, with 37 Mt cumulative and 20,000 direct jobs lost since 2022. Cefic reports annual investment fell from 2.7 Mt to 0.3 Mt while energy costs drove 49% of closure decisions, resha
Global chemicals remain in a supply-contraction cycle into Q3 2026, with Deloitte placing the sector "near the bottom of a capital cycle" while Cefic projects Europe at roughly 3% production growth.
Global chemical-industry capital expenditure in 2026 is splitting sharply by region: US capex is forecast to rise only 0.9% to roughly $40 billion, EU27 spend fell from €29.3 billion (2023) to €28.4 billion (2024), while growth projects concentrate in AI data-center chemistry and Middle East petchem
Chemical industry M&A in 2026 is concentrated: $67bn deal value across 552 transactions in the trailing 12 months to Q1, with eleven deals over $1bn capturing ~70% of value. Capital is flowing to specialty assets in coatings, water, and advanced materials, while European commodity assets face Chines
Q2 2026 cerium oxide landed at USD 1,090/MT in China and USD 1,265/MT in the USA, with SMM metal at USD 3.88/kg on 3 Sep 2026, down 5.86% MoM. Forecasts diverge from 5.9% to 23.7% CAGR through 2030-2033.
Cerium oxide prices are forecast to soften mildly in Q3 2026 in both China (FOB Shanghai) and Europe (Ex-Warehouse Rotterdam) on easing supply tightness and modest inventory builds, while the structural driver, a chronic oversupply tied to neodymium-praseodymium separation, keeps any rally capped ab
Cerium oxide holds about 34.8% of global cerium value in 2026 and roughly 77% of all cerium product revenue, with glass polishing, automotive catalysts and specialty alloys as the three primary demand drivers through 2035.
Global cement prices firmed into Q2 2026 with Europe at USD 256/MT (Germany) versus USD 55/MT in China, a 4.6x regional gap driven by EU ETS carbon pass-through and CBAM. Carbon cost exposure, energy, and producer discipline are the dominant price drivers through 2026-2027.
Cement decarbonization investment in 2026 is concentrated in three buckets: clinker substitution and low-carbon binders, alternative fuels and hydrogen, and CCUS at the kiln stack. US public funding of $1.6 billion through DOE's Industrial Demonstrations Program targets six cement projects, matched
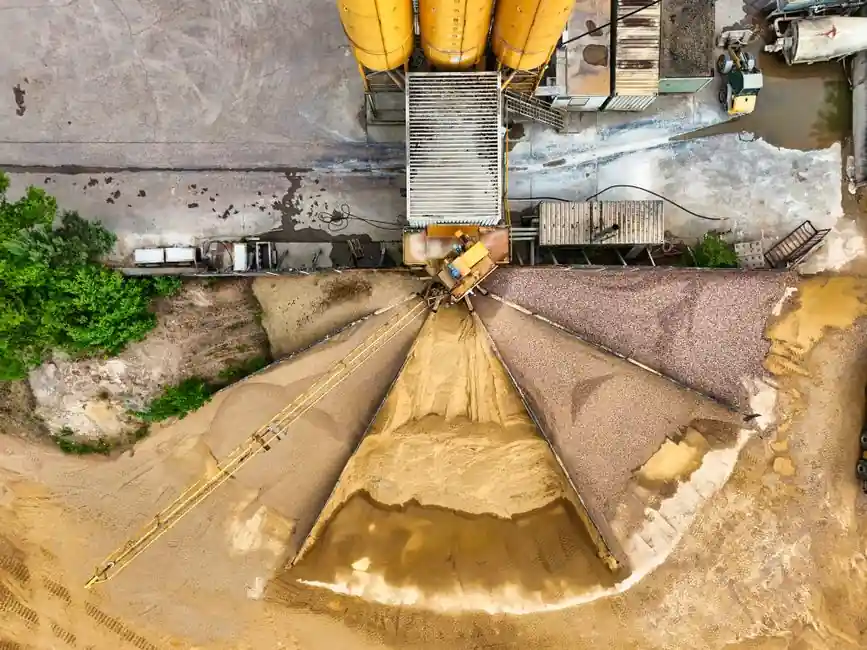
US cement capacity utilization sits near 76% against an 80% producer target, China utilization is below 50%, and India is adding 160-170 Mt of new capacity through FY2028, signalling a three-speed global market in 2026.
Cell-to-pack (CTP) and cell-to-body (CTB) designs replaced module-based packs across most Chinese EV programs in 2022-2025, with the cell-to-body market reaching $15.33B in 2025 and projected at $17.48B in 2026. LFP prismatic and large-format (46x) cylindrical cells remain the only practical enabler
Q2 2026 caustic soda prices diverged sharply by region: USA USD 589.33/MT, Germany USD 803.67/MT, Japan USD 451.00/MT, Saudi Arabia USD 631.33/MT, with chlor-alkali margins compressed by Chinese oversupply and weak PVC economics.
Industrial-grade PAN carbon fiber runs $10–30/kg in 2026 while aerospace-grade (high-modulus) commands $40–90/kg, with aerospace prepreg and autoclave-cured sheets exceeding $260–320/m². Specifying the wrong tier inflates part cost 3–5x without structural benefit, so match modulus and processing to
Global carbon fiber production capacity is on track to reach 575,000 metric tons by 2030 if all planned projects complete, against a 2026 market valued at USD 3.93 billion growing at 6.96% CAGR. Industry trackers flag a structural price war: announced capacity outruns current demand, pushing utiliza
Global carbon black averaged USD 1.35–1.60/kg through 2026, with North America at USD 1.80–2.00/kg, the EU at USD 1.45–1.70/kg, and Northeast Asia near USD 1.06/kg; specialty grades grow at a 10.9% CAGR versus 3.46% for the broader market.
PJM's 2026/2027 capacity auction cleared at USD 329.17/MW-day, the market cap, leaving the 13-state region roughly 6,800 MW short for a second year running. Locked-in contracts hold capacity charges at nine times their pre-2024 level through May 2029, with a Reliability Backstop procurement for new
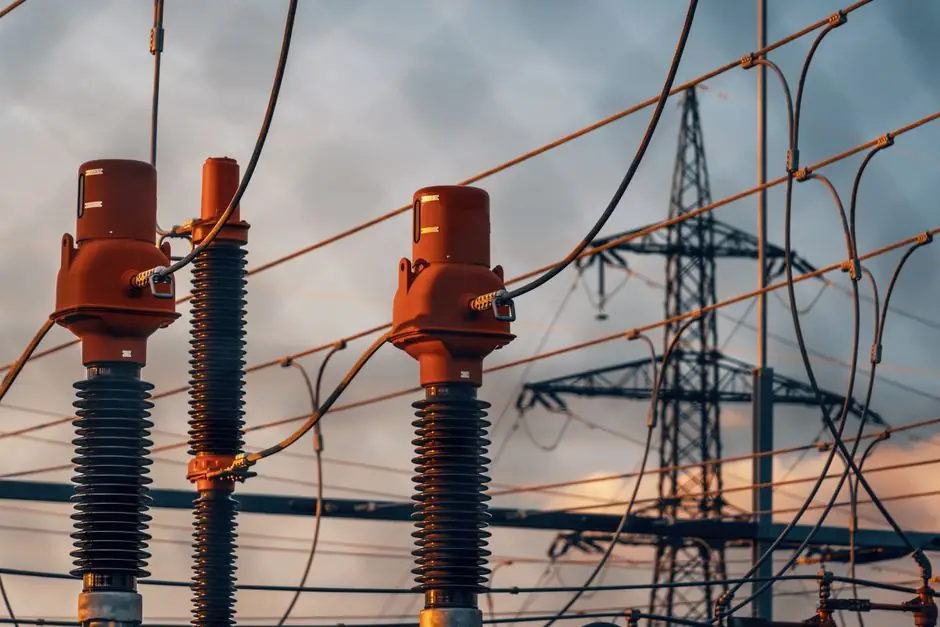
Vacuum circuit breakers (VCBs) are mature and dominant from 1 kV up to 40.5 kV, with breaking capacities to 63 kA and 10,000+ mechanical operations, but at transmission voltages above 72.5 kV SF6 gas breakers remain the default in US practice. SF6 has a global warming potential 23,500 times that of
Chemical recycling in 2026 still processes only a small share of global plastic waste, with pyrolysis dominating capacity and depolymerisation scaling for PET. The pathways that close the loop, depolymerisation back to monomer, conversion to cracker feed, and feedstock flexibility, remain constraine
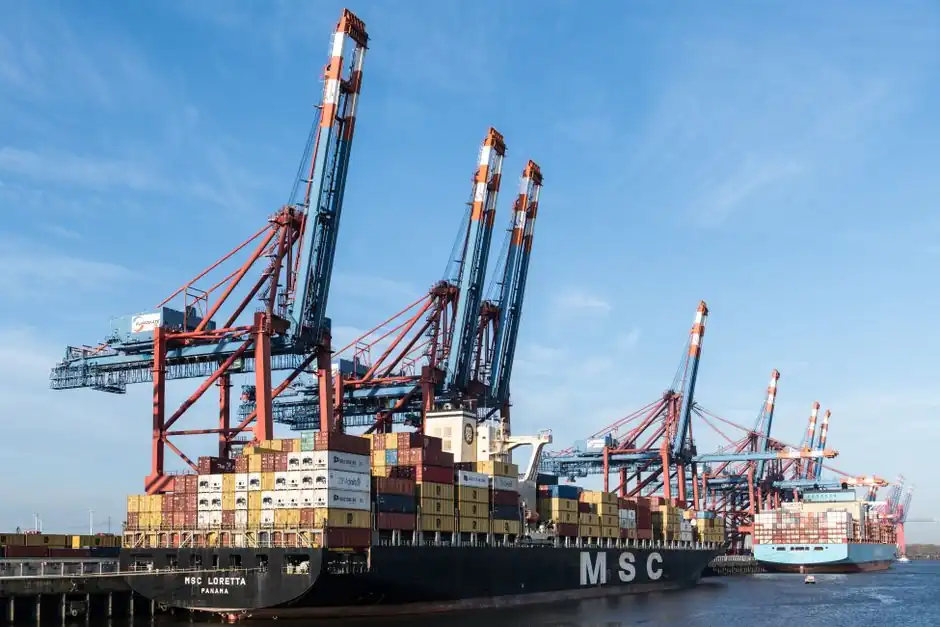
Ammonia and methanol can cut shipping CO2 by 90-95% on a tank-to-wake basis, but only if upstream production, bunkering, and engine slip/NOx controls scale in parallel. Methanol leads near-term with ~60 vessels in service and 300+ on order; ammonia is still in proof-of-concept, constrained by toxici
US PPI for Copper Wire and Cable hit 602.48 in August 2026, up 27.24% year-over-year and 4.20% month-over-month, driven by LME copper around $6.51/lb and COMEX at $6.5880, with cable price indices climbing 7–12% across India, North America, and APAC.
Data center busways are forecast to grow from USD 3.9 billion in 2026 to USD 8.1 billion by 2032 at a 13.1% CAGR, with the broader busway market at USD 14.75 billion in 2025. Copper conductor and 801-1,250 A ratings dominate current designs.
Global building automation market value sits at USD 122.49B in 2026 with an 11.8% CAGR to 2030, driven by EU energy directives, Asia-Pacific smart-city spending, and AI-led retrofit programs. Operators should focus on open-protocol interoperability and edge analytics to close the adoption gap.
European bronze spot price reached USD 20.09/kg in September 2026, up 1.2% month over month and 21.5% above the December 2025 level of USD 16.16/kg, driven by copper and tin feedstock costs and tight import supply. Brass and bronze scrap posted modest weekly gains in the April 2-9, 2026 Scrap Monste
The board-to-board connector market reached USD 12.42 billion in 2025 and is forecast to hit USD 16.05 billion by 2030 at a 5.3% CAGR, while the wire-to-board connector segment grew to USD 4.88 billion in 2026, both shaped by EV battery systems, 5G, and sub-2 mm pitch demand.
Wind blade recycling capacity scales sharply in 2026 as retirements hit 3,000-9,000 blades/yr, with mechanical, thermal, and chemical routes competing at $1,000-2,000/ton versus $60-150/ton landfilling. Glass fiber recovery and AI-driven blade sorting now anchor commercial deployment.
Refined bismuth traded at $67.00/kg on 25 September 2026, up 275.77% since the start of 2025 and 465.40% since January 2024. The driver is a supply squeeze, not a demand boom: China export curbs since early 2025, plus concentrated by-product output. Specification impact is highest for low-
Global bio-based plastics production capacity is set to double from 2.31 Mt in 2025 to 4.69 Mt by 2030, with the broader bioplastics market valued between USD 21.7 B and USD 28.08 B in 2026 depending on scope, growing at a 17.5-17.9% CAGR through 2033-2035.
Bifacial PV module share of newly installed utility-scale solar power is on track to reach roughly 90% by 2033, up from 5% in 2017. With bifacial gain commonly running 8-15% in real projects and dual-glass designs holding 57.4% of 2026 shipments, specifying the format correctly is now the defau
BESS augmentation adds new battery capacity to an existing storage system mid-life, restoring or exceeding nameplate after LFP fade reaches 2-3% per year. The U.S. installed base crossed 60-70 GW by 2026, with Q1 deployments up 32% year-on-year and Q2 hitting a record 20.2 GWh, making mid-life repow
U.S. data center developers have announced roughly 100 GW of behind-the-meter natural gas generation capacity, equal to 18% of the existing U.S. gas fleet. Enverus forecasts 25.5 GW of new industrial BTM load from 2026 to 2030, with 22.5 GW attributed to data centers.
Bearing buyers face a 2026 cost stack where hot-rolled coil has roughly doubled to about $1,200/ton from $800 a year ago, Section 232 tariffs remain at 50%, and bearing steel demand tracks a 3.2% CAGR toward a $9.19 billion market by 2036. Expect single-digit-to-low-double-digit list price pass-thro
Global bearing demand is splitting into two tracks in 2026: traditional ICE automotive slides to roughly 2% annual growth, while EV drivetrains, 5 MW+ wind turbine slewing rings, and industrial robotics pull the market toward a 10.9% CAGR through 2034. High-carbon bearing steel, hybrid silicon nitri
U.S. battery storage installations hit a record 20.2 GWh in Q2 2026, pushing first-half deployment to 30.8 GWh, and Benchmark/SEIA raised the 2030 U.S. forecast 11.5% to 683 GWh on utility-scale momentum.
Used EV battery packs retired at 70-80% State of Health now feed a 2026 second-life stationary storage market valued at USD 1.70-10.96 billion, with 25-30 GWh of repurposed capacity scaling toward 330-350 GWh by 2030 at roughly $116/kWh.
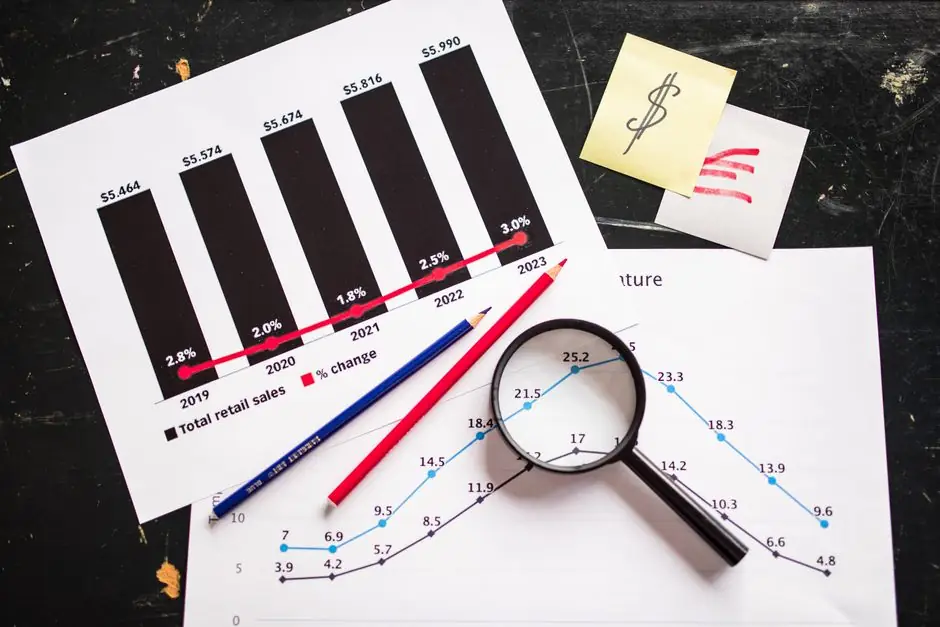
The global black mass recycling market is sized between USD 12.13B and USD 18.2B in 2026 across major forecasters, with EV-battery feedstock driving 58.23% of 2025 share and hydrometallurgy capturing 43.35% of processing technology. Q2 2026 payables cooled versus Q1 as battery metal benchmarks decli

Global volume-weighted EV battery pack price averaged $108/kWh in 2025, with Chinese LFP packs at roughly €64/kWh ($74) and stationary storage packs falling to $70/kWh. Cobalt and lithium price shocks were absorbed via LFP adoption, keeping cell-only averages at $79/kWh.

Global battery cell capacity will reach 3,200 GWh by 2027 with utilization near 77%, while regional ratios run 1.9x (North America), 2.2x (Europe), and 5.6x (China), per a 2026-08 plant-setup white paper and 2025-11 capacity data.
Global BESS fire protection spend tracked between USD 3.8B and USD 6.8B in 2025 across published forecasts, with 10.5–12.4% CAGRs running to 2034–2036 as NFPA 855 and UL 9540A enforcement plus pre-fire gas detection reshape BESS suppression specification.

In 2026, LFP battery cells run $60-$100/kWh versus $80-$150/kWh for NMC at the cell level, and LFP packs average $81/kWh against $128/kWh for NMC. The 30%-plus spread reflects chemistry, regional tariffs, and segment choice more than raw metal costs.
The global average EV battery pack size in 2026 sits between 60 kWh (China BEV) and 90 kWh (US BEV), with the EU near 70 kWh and global fleet average around 73 kWh at the higher end of BEV offerings.

Autonomous forklift revenue in 2026 sits between USD 3.17B and USD 8.76B depending on scope, with most analysts clustering near USD 4.3B-5.6B. LiDAR-led navigation, 24/7 operation, and WMS-integrated fleets are the dominant 2026 procurement signals, with growth in the 4.6%-13.9% CAGR band.

Automotive semiconductor content per vehicle is rising sharply through 2026, with average memory alone forecast to climb from $111 in 2025 to $275 by 2030, and total chip value per new EV climbing alongside zonal E/E and SiC adoption.
Global light vehicle production for 2026 is projected at roughly 97.8 million units with BEV sales reaching 17.4 million (about 19% global share), while China alone targets 2.45 million units in January 2026 alone and India leads regional growth at 10.4 million units.

North American and European tier-1 auto suppliers cut more than 60,000 jobs in 2025, with 20% already in financial distress before tariffs and tariffs projected to push that figure up by 23%. Tier-1 capex restraint through 2026 will tighten flows to industrial equipment and component suppliers.

Turnkey robot cells are expanding at a 14.6% CAGR through 2034, against roughly 8% for industrial robots overall, signalling that integrators and end users are buying pre-engineered cells faster than standalone manipulators.

Second-life EV batteries are not cost-competitive with new LFP cells in 2026, losing on $/kWh and energy density despite environmental upside, so they fit only stationary storage roles where 70-80% residual capacity and footprint savings beat raw price.

Power semiconductors are not in broad oversupply in 2026; supply is split, with 8-inch legacy MOSFET/IGBT and AI-grade SiC tight, while automotive SiC shows price pressure. Industrial buyers face 26–52 week lead times on branded discretes and 20–30+ weeks on PMICs and VRMs.

New nuclear PPAs for data centers are landing at $80-115/MWh, on par with new combined-cycle gas at $70-120/MWh, but win on capacity-factor economics because nuclear delivers 93% versus gas's 59.7% availability. Cost crossover is tight: nuclear wins on 24/7 carbon-free baseload, gas wins on speed an

FRP composite prices are trending upward in 2026, with the global market expanding from USD 79.07 billion in 2025 to USD 83.17 billion in 2026, a 5.20% CAGR through 2031 driven by wind, EV, and retrofit demand.

Electric forklifts have outsold internal combustion (IC) units in North America since 2019, with 144,861 electric units vs 77,588 IC units purchased that year per the Industrial Truck Association, and the gap widened in 2020 to 135,163 electric vs 61,161 IC units. Lifecycle cost, indoor air-qua
Para-aramid dominates the 2026 aramid fiber market at roughly 68–76% share, with global revenue near USD 4.52–4.88 billion. Protective apparel and fiber-optic cable reinforcement are the two most concentrated demand pulls, alongside tire, aerospace, and battery-enclosure growth.
Antimony peaked at $27.50 per pound in June 2025 after China's export ban, then fell 36% to roughly $20.30 per pound by November 2025 as flame-retardant buyers cut orders, with the correction extending into 2026 as Southeast Asian smelting capacity scaled up.
Global analog chip demand in Q3 FY2026 is recovering selectively, with one major supplier's industrial revenue jumping 40% year-over-year, while the broader market tracks toward USD 98.1B in 2026 at a 7.3% CAGR as EV power management and factory automation absorb the supply.

The global AMR market sits between USD 5.5B and USD 8.6B in 2026 depending on scope, with manufacturing-floor deployments closing the gap on warehouses as Industry 4.0 line-side and WIP transport scale out. Warehousing still leads in unit count, but factories are the faster-growing node for sensor-b

The global amorphous core transformer market sits between USD 3.23 billion and USD 21.88 billion in 2025-2026 depending on the research scope, with all major studies tracking 4.4-7.6% CAGR through 2031-2035 and Asia-Pacific holding 46-52% of demand. Oil-immersed distribution designs dominate, driven

Ammonia prices rose sharply in September 2026 across major regions, with Europe at USD 0.92/kg (+22.7%) and North America at USD 0.81/kg (+24.6%), driven by natural gas feedstock costs, Iran-linked Gulf conflict disruption, and tight Russian supply, while global production sits near 198 MT/yr and 70

From 1 July 2026 ammonia cargo on gas carriers can be burned as fuel under the amended IGC Code, opening the first commercial path. Engine programmes from MAN Energy, Win GD and Wärtsilä target ammonia-capable newbuilds, with IMO modelling 60% ammonia penetration by 2050 under a levy-plus-standard p

Aluminum wire rod prices in Q2 2026 ranged from USD 3,407/MT in Brazil to USD 4,708/MT in Argentina, with Germany at USD 4,218/MT, Japan at USD 4,387/MT and China at USD 4,050/MT. Global market size for aluminum wire rod, cables and conductors is forecast to reach USD 41.6 billion by 2030, while Ind

LME aluminium traded at $3,252.10/t on 23 September 2026, down 0.29% day-on-day. Energy accounts for 30% to 40% of primary smelter cash cost, making power price exposure the single largest swing factor on the 2026 cost curve.
On Sept. 11, 2026, the European Commission withdrew its proposal to restrict EU aluminium scrap exports, ending a 2026 policy fight as BIR and Recycling Europe warned of market distortion. The U.S. parallel track, led by The Aluminum Association's push for a Used Beverage Container export ban, remai
LME aluminium settled at $3,257.05 per tonne on 2026-09-23, near a 22.88% year-on-year gain, with regional premiums of $612/t (Europe) and $302/t (Japan) reshaping landed-cost stacks for downstream extruders and mills.

European duty-paid aluminium premium held near $489.50/tonne on the April 2026 forward, with the duty-unpaid benchmark settling $451.15/tonne (SEP 2026) on 22 September 2026, a $38.35/tonne spread that mirrors the 3% EU import duty on LME cash. CME lists both legs side-by-side: AEP (duty-unpaid) and

Visible aluminum inventories on the LME fell below five days of global supply in early June 2026, with 1.5 million tonnes total visible stock, driving the spot price to a 22.67% year-on-year rise to 3,258 USD/T on 22 September 2026.
Aluminum foil prices held firm across Q2 2026 at USD 3,540–3,695/MT FOB/CIF, while battery-grade foil capacity expansions and ultra-thin gauge demand (≤8–10 μm) pull the segment toward 9.4% CAGR. Buyers in 2026 must split sourcing strategies between commodity packaging foil and precision battery cur

U.S. PPI for Extruded Aluminum Shapes (WPU10250162) printed 252.267 in August 2026, down from 261.139 in July, while spot LME aluminum closed at 3261.40 USD/T on 22 September 2026, a 23.44% gain year-on-year. Regional extrusion-grade premiums sit at 3.23 USD/kg in North America, 3.27 USD/kg in Europ

Aluminum extrusion demand in 2026 sits inside a global market sized at USD 101.48-108.71 billion, with construction holding the largest end-use share (about 38% in Asia Pacific) and transportation, electrical, and machinery pulling the rest of the structural growth curve.

Global aluminium demand is forecast to reach 106.8 million tons in 2026, up 2.7% year-on-year, with transportation, construction, and packaging the dominant end-use channels driving solar frames, EV lightweighting, and can/foil growth.

North-American BEVs averaged 885 lb of aluminium per vehicle in 2022, 85% more than non-BEVs, and EU studies project a further ~54 kg of EV-specific aluminium per car by 2030 versus 2022 baselines.

Aluminum coil price in 2026 splits by alloy and temper on top of LME spot: 1xxx O coils sit near USD 2,300–2,800/ton, 3xxx H14 around 2,500–2,950, 5052-H32 near 2,800–3,300, and 6061-T6 or 7075 climbs to 3,300–3,900 and beyond. Regional and gauge premiums then layer another 10–55% on top.
A380 and A356 prices diverge on chemistry, not on commodity aluminum: A380 runs higher because of its 3.0-4.0% Cu content driving alloying cost and energy use, while A356 is cheaper per kg but accumulates cost in T6 heat treatment. North American gravity-cast A356 and high-pressure die-cast A380 are

Narrowbody output (693 units YTD July 2026) ran roughly 5.2x widebody volume (134 units) as Airbus and Boeing's A350 and 787 programs struggled to stabilise at target rates.

The AI server market reached USD 262.22 billion in 2026 against a general-purpose server base of USD 102.25 billion, but ASIC share slipped to ~27% as GPU systems still dominate. TrendForce pegs 2026 AI server shipment growth at ~28% YoY versus ~13% for general servers.

Ethernet now leads AI back-end fabric shipments, with the data center Ethernet switch market reaching $15.4 B in Q1 2026 (+39.8% YoY) and Nvidia's Ethernet switch share rising from under 4% to 21.5%; InfiniBand holds under a quarter of new AI cluster wins but retains the lowest-latency niche.

NVIDIA still commands roughly 80% of the AI accelerator market in 2026, but custom hyperscaler ASICs are growing 44.6% year-over-year against 16.1% for GPUs, reaching 27.8% of AI server shipments. For inference workloads at scale, ASICs win on cost-per-query; GPUs retain training and flexibility.
The 2026 AI capex cycle sits at $775–800B from the Big-5 hyperscalers (about 64% above 2025), with PwC modelling $31.6T global data-centre spend through 2050; the live debate is overbuild vs underbuild, resolved more by power, chip packaging, and chip cost than by demand.

Cloud and data-center AI accelerator shipments are scaling sharply in 2026, with Omdia's July 2026 forecast covering GPUs, AI ASICs, and FPGAs through 2032, and Microsoft negotiating TSMC capacity for more than 300,000 Maia 300 units for 2027 delivery.
Airbus and Boeing combined backlog hit 15,461 commercial aircraft at end-2025, with Airbus targeting 75 A320neo-family aircraft a month while CFM Leap and Pratt & Whitney GTF engines absorb the rate ramp. IATA projects 5.2 billion passengers in 2026, up 4.4 to 4.9 percent year over year.

AEM electrolyzers moved to multi-megawatt commercial delivery in 2026, with Power to Hydrogen installing a 500 kW system at Port of Antwerp-Bruges on 250 kW stack modules and Horizon shipping a 5 MW unit in April. CAPEX claims of up to 65% below PEM remain vendor-stated.

Global adhesives and sealants demand is expanding in 2026, with the broad market sized near USD 81 billion and EV-specific adhesives forecast to compound at 18.67% CAGR through 2031, pulling higher-value chemistries like epoxy and silicone into battery pack, power electronics, and semiconductor pack
Prototyping still owns 57% of the 2025 additive manufacturing application mix, but production parts are the higher-CAGR segment as polymer and metal systems cross the 100 to 10,000-unit serial threshold in aerospace, medical, and automotive lines.

Additive manufacturing consolidation accelerated in Q2 2026 as BigRep delisted, Ricoh divested its 3D-for-Healthcare unit, Würth wound down its AM team, and 3DEO entered insolvency, while AM users Venus Aerospace, SWISSto12, and Ursa Major raised tens of millions. Capital is rotating from diversifie

US activated carbon prices reached USD 949.69/MT CIF in July 2026, up roughly 23% from June, as PFAS-driven municipal demand overran softer Asian supply. Coal-based grades still anchor 45% of global volume; coconut shell GAC remains the spec workhorse for PFAS removal but costs 15-25% more.
Brown fused alumina and silicon carbide abrasive grain landed costs are up 6–15% in 2026, with F46 BFA at the centre of grinding-wheel demand. Three pressures drive the move: bauxite and petcoke feedstock volatility, tariff and CBAM enforcement, and a 25–35% widened supplier-quote spread.

5N (99.999%) ytterbium oxide demand is anchored by Yb-doped fiber lasers operating in the 1030-1100 nm band and Yb-171 trapped-ion qubits, with optical lattice clocks at NIST and PTB adding a precision-metric pull on the same isotope.
Four-hour BESS projects now outpace 2-hour builds on IRR in Germany, delivering 13.7% unlevered return at 2026 COD vs 12.2% for 2-hour systems, despite 34% higher capex (€935k/MW vs €700k/MW).
Industrial 3D printing part cost in 2026 hinges on technology and volume tier, not headline machine price. Powder-bed metal systems reclaim and refresh unused powder, while desktop FDM units now sell for $250–400 with throughput near 500 mm/s, reshaping cost-per-part baselines.
Aerospace held 27.73% of the 2026 metal 3D printing market, with LPBF, DED and binder jetting expanding into flight hardware, hypersonics, and satellites. Ti6Al4V, Inconel 718, and AlSi10Mg dominate material selection across brackets, turbine blades, and thermal management.

Samsung demonstrated a 900-layer 3D NAND die in May 2026 by string-stacking two 450-layer arrays, pushing the industry past the 300-layer threshold that has defined production since 2023. Mainstream rivals Solidigm and SK hynix remain at 192 to 321 layers, while Samsung targets 1,000-layer chips by
Global 300mm fab capacity is set to reach a record 9.6 million wafers per month in 2026, with $149 billion in front-end equipment spending, a 31% year-over-year jump. Memory leads the ramp at +32% spend growth, while China, Korea, and Taiwan account for the largest regional equipment outlays through
TSMC's N2 entered high-volume manufacturing in early 2026 at Fab 20 in Hsinchu, targeting 60,000 wafers per month by Q4 2026 with Apple securing over 50 percent of initial allocation. NVIDIA's Rubin AI accelerator lands on N3P rather than N2, leaving AMD's Zen 6 and EPYC Venice as the marquee CPU ad

Offshore wind has standardised on 15 MW-plus turbines in 2026, with the Vestas V236-15.0 MW and Siemens Gamesa SG 15-236 anchoring bids, while MingYang and Dongfang push 18-26 MW in China. The bottleneck is now WTIV day rates ($340,000-$560,000) and 15 t/m² quay loads, not the turbines themselves.

On-demand GPU capacity is effectively sold out through mid-2026, with HBM, TSMC N3, and power infrastructure forming simultaneous bottlenecks. Supply pressure is structural, not speculative, and lead times on Blackwell PRO SKUs run 3-7 months with spot DRAM up roughly 8x since early 2025.
EUROBAT's June 17, 2026 Battery Innovation Roadmap projects lithium holding about 80% of the European battery market (around 6 TWh) beyond 2030, with LFP evolving into LMFP and high-nickel chemistries, while solid-state remains a long-term play and sodium-ion targets an 8% share by 2035.
Global GPU capacity expansion in 2026 is anchored on HBM and CoWoS packaging, not raw die output: SK Hynix, Micron, and Samsung hold roughly 100% of HBM share while TSMC's CoWoS gap narrows from ~20% to ~10% by year-end. AWS and NVIDIA added 2 million GPUs to the 2027-2028 pipeline.
China and the United States jointly anchor global UPS production, with Asia-Pacific carrying roughly 30% of 2025 demand and North America holding 42.3% of the industrial UPS segment. Modular and lithium-ion designs are the fastest-shifting capacity lines, and the market is on track from US$9.13 bill
Cloud GPU rental prices for the newest cohort rose from $2.12/hr in October 2024 to $4.72/hr by September 2026, while Legacy silicon fell from $1.77 to $0.95 over the same window, per the AIMultiple index covering 17 models across 75 providers. Retail-side GPU tracking is dominated by Tom's Har

NVIDIA's GPU roadmap through 2028 pins Blackwell in volume production, ships Vera Rubin in H2 2026 with 336B transistors and 50 PFLOPS NVFP4 inference, and schedules Rubin Ultra for H2 2027, anchored by an annual architecture cadence confirmed at GTC 2026 and Computex 2026.

Chile led global lithium carbonate exports at $2.81B in 2024, with Argentina at $666M and South Korea at $72.8M, while Australia dominated mine output at 88,000 MT. China remained the largest importer at $2.53B, anchoring demand to its refining and cell capacity.

Siemens AG led the industrial Ethernet market in 2025 with 19.3% share, while the top five vendors (Siemens, Cisco, Schneider Electric, Rockwell Automation, ABB) together held 65.3%. Ethernet-based industrial networks reached 76% of new nodes in 2025, and the market is sized between USD 9.8B and USD

Global HVAC filter demand is forecast to climb from $9.32B in 2025 to $13.35B by 2030 at 7.5% CAGR, with HEPA, fabric-filter dust collectors, and PHA-based filter media shaping industrial procurement through 2030.
Activated carbon market estimates for 2026 diverge sharply across published trackers, ranging from USD 4.16B to USD 9.26B with CAGRs of 5.62% to 14.1%. Coal-based grades held 43.18% of raw-material share in 2025, and Asia-Pacific leads consumption at 37.72% regional share.
Goldman Sachs raised its 2026-2030 AI server forecast ~18% to roughly $1.24 trillion by 2030, with traditional servers clearing $160B; data center power demand is projected to climb 165% versus 2023 by end of decade.

The 2026 global industrial laser market sits at $27.17B in 2026 heading to $42.39B by 2033, with IPG, Coherent, Trumpf and Han's Laser leading a six-vendor source tier plus four Chinese clusters that control over 60% of production capacity.

Welding robotics demand is forecast to expand from a $7.41B cell market in 2026 to roughly $11.83B by 2030 at a 12.4% CAGR, with broader robotic welding lines tracking $19.9B by 2032 (10% CAGR). Asia-Pacific anchors volume, automotive and EV battery lines lead use cases, and arc-on-time gains of 90–
2026 industrial gearbox procurement splits into three tiers, with Indian planetary/helical suppliers pricing 30–50% below European equivalents and wind/slew niches dominated by Flender, Siemens, ZF, and Winergy. Selection is spec-driven, not brand-driven, anchored on ISO 1328 gear grade, AGMA 2001 d

Global RV reducer market reached US$ 908 million in 2025 (1.56 million units, average price USD 566.9), with Japanese suppliers, led by Nabtesco at ~60% industrial-robot share, still dominating high-end joints. Chinese localization and humanoid-robot demand are reshaping competition through 2032.

UBTech Robotics led the global humanoid robot market with 14% revenue share in 2025, followed by Unitree at 13% and Agility Robotics at 11%. Top-5 OEM concentration reached 55%, with the broader market projected to grow from USD 10.9B in 2026 to USD 192.7B by 2035 at a 37.6% CAGR.

Global AI accelerator demand is set to reach $68.38 billion by 2030, with North America at $26 billion, GPUs holding 62% share, and TSMC guiding 2026 capex to $52-56 billion on hyperscale pull.

AI server competition in 2026 pivots on NVLink 5 (1.8 TB/s/GPU), HBM3e capacity (180-256 GB), and PCB stack-ups above 40 layers, with NVIDIA HGX B200, AMD MI325X and Intel Gaudi 3 all shipping in 6U/2U OEM sleds from Dell and Supermicro.
The 2026 DRAM market is defined by structural undersupply: TrendForce logged 93–98% quarter-on-quarter contract price growth in Q1 2026, IDC projects only 16% YoY supply growth, and DDR5 SKUs have run 3.5–4x above late-2025 levels as Samsung, SK Hynix, and Micron divert wafers to HBM at a roughly 3:

Global industrial pump demand is projected to expand from $77.16B in 2026 to $118.47B by 2034 at a 5.51% CAGR, with regional GCC spend hitting USD 2.45B by 2025 (3.3% of global). Vendor differentiation now hinges on energy efficiency, dry/oil-free architectures, and tariff-resilient sourcing.

China controlled 60% of global mined magnet rare-earth output in 2024 and over 80% of refining capacity, with Asia Pacific capturing 87% of 2025 market revenue. Lynas, Iluka, MP Materials, and Energy Fuels lead ex-China supply diversification efforts.
Global desalination market is forecast to grow by USD 11.27 billion at an 8.9% CAGR from 2025-2030, building on a 40% capacity expansion between 2020-2025. Municipal and industrial demand, brackish and seawater sources, and renewable-energy integration are the main 2026-2030 growth drivers.

Emerson Electric led the industrial valve market with over 12% share in 2025, followed by a top-5 cohort holding 42% collectively, per Global Market Insights. Ball valves captured 37.10% of the 2025 valves market by type and stainless steel held 45.05% by material, per Mordor Intelligence.

Global PCB revenue is projected to land in the USD 85-90 billion band in 2026, expanding at a 5-7% CAGR through 2030 on AI server, EV, and high-end HDI demand. AI-server PCB alone is forecast to reach USD 84 billion by 2028 at a 148% three-year CAGR, with 30+ layer and M9-class material share accele
U.S. DC fast-charging competition in 2026 is consolidating around OCPP-compliant hardware with ISO 15118 Plug & Charge, dual CCS1/NACS connectors, and 120–400 kW per-port output. A 4-port 150 kW site draws 600 kW continuous, and per-port power guarantees now matter more than headline price.

Global EV charger demand is forecast to grow from a USD 22.50 billion 2025 base at a 36.2% CAGR through 2030, with APAC capturing 44.7% of incremental revenue and US residential Level 2 AC chargers (7-19.2 kW, NACS/J1772) heading to USD 11.20 billion by 2030 on 80% home-charging share.

Solar glass supply remains heavily concentrated in China, with Xinyi Solar and Flat Glass Group jointly controlling roughly 50% of global production capacity as of March 2026. Anti-reflective coated glass holds 60-65% of the market by type, and float-line output accounts for 67.78% of 2025 volu
Global EV battery market value is projected to reach USD 198.86 billion by 2030 at a 22.2% CAGR (2025-2030), but BNEF flags slower growth as plug-in hybrids and range-extenders cut per-vehicle pack size, while stationary storage offsets part of the road-transport slowdown.

CATL and BYD together held 55.6% of global EV battery installations in 2025 at 659.5 GWh, and CATL alone hit a 50.1% domestic China share in Q1 2026 on NMC chemistry dominance.
Consumer FDM 3D printing in 2026 is a three-tier market: budget ($150-300) at 60% unit share led by Creality, speed ($300-600) at 30% led by Bambu Lab, and professional ($600+) at 10% led by Prusa, Ultimaker and Bambu X1 Plus. Hardware has plateaued, while AI slicers, multi-material capability, and
BloombergNEF's July 2026 forecast puts US data center installed capacity at 118 GW by 2030, up 52% from its December 2025 number, with Goldman Sachs Research modelling a 165% global power-demand rise versus 2023 and a near-doubling of capacity by 2030, driven primarily by AI training and inference l

Global wind installations added 165 GW in 2025 (+40% YoY), and the wind turbine market is forecast to grow from $194.83 billion in 2026 to $283.8 billion by 2030 at a 9.9% CAGR, led by Asia-Pacific, with offshore and high-capacity units driving the second half of the decade.

Server hardware in 2026 is being reshaped by a hyperscaler AI buildout: combined cloud-provider capex is forecast above US$710 billion, server DRAM prices are up ~95%, and the global server market reached US$122.6 billion in vendor revenue, forcing enterprise buyers to reset budget baselines.

Global data center server spend is forecast to expand at a 21.2% CAGR through 2030, adding USD 273.57 billion in market value, with rack servers leading the product mix and North America commanding the largest regional share. Hyperscalers still own most capacity, but neocloud and sovereign AI factor

The global lithium-ion battery market is converging on roughly $136-175 billion in 2026, with chemistries splitting between LFP cost leadership and NMC premium-EV dominance, and CATL, BYD, LG, Panasonic, and Samsung SDI anchoring the supplier tier.

Lithium battery demand is set to expand 3x by 2030 and 4.2x by 2035, with the global lithium-ion market projected at USD 136.28 billion in 2026 reaching USD 366.82 billion by 2031, and cell prices falling toward USD 80 per kWh.

The data center GPU market is forecast to add USD 125.43 billion between 2026 and 2030 at a 15.8% CAGR, while the broader GPU market is sized at USD 102.8 billion in 2026 reaching USD 652 billion by 2033 at a 30.2% CAGR, with training workloads dominant in 2024-2025 and inference overtaking by 2027.
NVIDIA holds 80-85% of the 2026 data center AI accelerator market by revenue, down from 92% in 2023, with AMD MI300X/MI400, Intel Gaudi 4, and hyperscaler custom silicon closing in. AMD's MI400 sells at 25-30% below B300 while matching inference performance, reshaping the TCO argument.

NVIDIA holds roughly 70% of total AI semiconductor sales and 92% of the data-center GPU segment, while AMD, Broadcom, Intel, and the hyperscaler in-house ASIC programs (Google TPU, Meta MTIA, Amazon Trainium, Microsoft Maia) split the remainder of a market sized at USD 52.92B in 2024, tracking towar

AI chip demand is on track to expand roughly 5-9x from 2025 to 2030, with the global AI chip market projected to exceed USD 1 trillion by 2030, and broader semiconductor demand reaching USD 1.5 trillion the same year on 33.2% CAGR.
NVIDIA held 55.2% of the installed PC video-card base and roughly 75-81% of 2026 AI accelerator revenue, while AMD captured 20.0% of the installed base and 5-7% of AI revenue, and Intel sat at 19.2% installed and about 1% of AI share.

Syntegon, IMA, GEA, and ACG head the 2026 pharmaceutical equipment supplier map, with the global pharmaceutical manufacturing equipment market valued at USD 21.24 billion in 2026 and projected to reach USD 30.39 billion by 2032 at a 6.2% CAGR.
The global SCADA market is projected to expand from USD 13.87 billion in 2026 to USD 26.59 billion by 2034, an 8.5% CAGR driven by cloud, edge, and AI integration across utilities and discrete industries.

Global industrial ethernet market reached USD 12.26 billion in 2026 and is projected to climb to USD 26.10 billion by 2034 at a 9.90% CAGR, with PROFINET and EtherNet/IP retaining protocol dominance, while SPE, APL, and TSN reshape plant-floor hardware and cabling requirements through 2026.

The global cutting tools market is estimated at USD 23.1–27.7 billion in 2026 with 4.5–5.2% CAGR to 2035, while metal cutting tools alone reach USD 91 billion in 2026. Automotive leads demand at 33%, with EV battery and motor machining driving Asia Pacific growth.

The global industrial fasteners market is valued at USD 92.13 billion in 2026, on track to USD 113.33 billion by 2031 at a 4.23% CAGR, with metal fasteners at 49.23% of 2025 revenue, automotive at 33.47%, and engineered high-strength and battery-ready grades outpacing commodity carbon-steel hardware

Global industrial filtration market estimates for 2026 diverge widely, from USD 37.88B to USD 48.52B depending on scope, with 2030-2035 CAGRs clustered between 5.4% and 6.8%; liquid vs air media split and HEPA/ULPA demand drive the variance.
Global food processing equipment demand in 2026 is sized between USD 59.0B and USD 68.3B depending on scope, with CAGR forecasts of 4.2% to 6.3%; drivers are automation, FSMA-style compliance, and Asia Pacific capacity build-out.
5G industrial modules are shifting from pilot gateways to scaled Industry 4.0 deployment, with 5G-specified minimums of 100 Mbps user-experience rate, 1 ms air-interface latency, and one million devices per square kilometre, all driving adoption in closed industrial networks.

Global 5G industrial module market revenue is projected to climb from USD 2.86 billion in 2026 to USD 7.36 billion in 2031, a 20.8% CAGR, with RedCap and eRedCap categories rising from 17.0% to 36.0% of revenue by 2031.

The global industrial catalysts market is sized at USD 23.57 billion in 2026, with a 4.81% CAGR to USD 36.03 billion by 2035, while heterogeneous catalysts hold over 60% revenue share and Asia Pacific is the fastest-growing regional segment.
Global vanadium supply is concentrated in three countries, China at 59%, Russia 17%, South Africa 7% of production, with integrated miners like EVRAZ, AMG, Ansteel and Bushveld dominating alongside battery-focused juniors such as Largo and Australian Vanadium in 2026.

Data center cooling spend is projected to grow from roughly USD 12.4B to USD 31.4B in 2026, depending on scope, with a 2026-2033 CAGR between 14.9% and 26.4% across major analyst forecasts. Liquid cooling is the fastest-growing slice, expanding at 26.4%-31.5% CAGR, while North America holds 36%-44%
Global BESS market value reached USD 50.81 B in 2025 and is forecast to hit USD 105.96 B by 2030 at a 15.8% CAGR, while installed capacity tracks 768.5 GW in 2025 to 3735.3 GW by 2033 at 21.9% CAGR.

Global battery electrolyte demand is forecast to reach USD 15.18–15.84 billion in 2026, with projections of USD 28.7–54.9 billion by 2031–2035 at CAGRs between 7.1% and 13.7%. Lithium-ion still holds ~81.7% of revenue, EVs absorb ~67% of volume, and Asia-Pacific commands ~69.7% of the market, while

The global battery electrolyte market is forecast to reach USD 34.46 billion with Tinci Materials, CAPCHEM, ENCHEM and Mitsubishi Chemical Group ranking as the leading suppliers, anchored by LiPF6 salt and carbonate-solvent output in China, South Korea and Japan.

Global vanadium market estimates for 2026 cluster between USD 2.6 billion and USD 58.6 billion depending on scope, with 2026–2034 CAGRs reported from 5.0% to 9.1%. The vanadium electrolyte sub-segment is forecast to expand from USD 234.9 million in 2026 to USD 1,012.1 million by 2033.

Global silicone rubber demand is sized between USD 14.5 billion and USD 16.9 billion in 2025, with 2026 forecasts clustering at USD 15.6–16.9 billion and 2034–2035 projections ranging USD 9.8–29.65 billion at 5.5–7.4% CAGR. Growth is driven by EV battery sealing, ISO 10993 medical-grade LSR, and Asi
Global battery management system (BMS) market value is projected to land between USD 11.55 B and USD 17.21 B in 2026, with 2026-2035 CAGRs clustered in a 14.0-21.7% band. AI-driven SoC/SoH estimation, wireless BMS, and EU digital-battery-passport compliance are the three structural shifts specifiers
ABS plastic's global sheet market is set to grow from USD 8.4 billion in 2025 to USD 13.6 billion by 2034 at 5.5% CAGR, driven by automotive trim, electronics and chrome-plated parts. Standard grades span 1.04–1.06 g/cm³ density, 40–50 MPa tensile strength, and 200–500 J/m notched Izod impact p

Global ball screw demand reached USD 5.72B in 2025 with a projected 7.31% CAGR to USD 10.79B by 2034. NSK, THK, SKF, Bosch Rexroth, Hiwin, and Schaeffler dominate a market where precision ground, rolled, and heavy-duty formats split by accuracy class and load capacity.

Chemours, Daikin, 3M, Solvay, and AGC lead the high-performance fluoropolymers field in 2026, with PTFE, FKM, and PFA grades dominating chemical, semiconductor, and aerospace demand. North America capacity expansion and a projected 8.2% CAGR through 2032 make supplier benchmarking a near-term procur
Global SCADA market value is projected to rise from USD 2,960 million in 2025 to USD 4,592 million by 2031, a 7.60% CAGR, with cloud deployment the fastest-growing segment and Asia Pacific the fastest-growing region through 2030.

The 2026 global abrasives market is valued at $69.35 billion in 2025 and is projected to reach $124.92 billion by 2035 at a 6.06% CAGR, with 3M, Saint-Gobain, Norton Abrasives, Klingspor, Carborundum Universal, and Abrasive Technology as the dominant competitive players.

The 2026 measuring-instruments market sits between a $940.57B process-and-control segment in 2026 and a $36.5B test-and-measurement segment, with fragmentation rising: DirectIndustry tracks 549 vendors and 1,471 SKUs, and Rockwell's 11th State of Smart Manufacturing report shifts 2026 specs from aut
The global wafer fab equipment (WFE) market is projected to add USD 34.7 billion between 2024 and 2029 at a 6.2% CAGR, while Yole forecasts the market reaching USD 133.7 billion by 2029 with deposition WFE alone rebounding to 2022 levels by 2026.
ISO 13726:2026 (Edition 3) refreshed accessory mounting dimensions for 16 MPa / 250-500 mm bore single-rod cylinders in 2026, while Chinese suppliers such as Dongguan Union Industry, Guangzhou Henghuan, Huanfeng and HPS Asia actively publish 2026-spec hydraulic cylinder catalogs targeting mobile and
Global hydrogen fuel cell market is split across three OEM layers: automotive stack makers (Daimler, Honda, Hyundai, Toyota), Tier-1 component suppliers (Toray, Sumitomo, NOK, Freudenberg), and Chinese system integrators like Sinopower exporting stacks and electrolyzers worldwide. PEM

Enterprise AI accelerator spend is on track to reach USD 372.68 billion by 2030 at a 16.9% CAGR, driven by GPU, ASIC, and FPGA demand for training and inference across cloud and HPC data centers. Vendor landscape centers on Nvidia H100 alternatives like Intel Gaudi 2/3 and AMD Alveo V70, with t
China-origin PV module spot offers sit at US$0.07-0.10/W for small-format cells and US$0.10-0.40 for monocrystalline thermal-hybrid panels as of 24 June 2026, with PV-glass spot assessments published daily by SCI99 and module-line utilisation rebounding from policy-driven restarts.
Top desalination EPCs in 2026 are consolidating around RO dominance, ERD retrofits, and multi-site SWRO buildouts; the supply chain stack — high-pressure pumps, energy-recovery devices, and RO membranes — anchors the competitive set.

Top lithium hydroxide producers in 2026 are dominated by Chinese battery-grade LiOH·H2O refiners anchored to lepidolite and spodumene conversion lines, with battery-grade purity ≥56.5% LiOH·H2O. Sourcing gates center on CAS 1310-65-2 (anhydrous) and 1310-66-3 (monohydrate), strong-alkali handling, a

The 2026 EV competitive landscape is shaped by three forces: range-extender hardware scaling to USD 2,656.66 million by 2032, European charger OEMs consolidating around ABB, Siemens and KEBA, and Chinese plus Korean OEMs locking in Southeast Asian share.
The 2026 IGBT competitive landscape is a consolidated, patent-heavy field where the top five filers hold 47% of patent records among the hundred largest filers, with Mitsubishi Electric (4,602), Fuji Electric (4,551), and Toshiba (3,427) leading. Press-pack IGBT demand is shifting toward 5.2–6.5 kV

Robotics unit prices in 2026 are bifurcating: 6-axis industrial arms and parallel pick-and-place units face ASP compression below 2019 baselines as Chinese capacity ramps, while wearable exoskeletons are climbing from a USD 3.52B 2026 base at a 43.7% CAGR toward USD 64.23B by 2034.

Global PV leaderboard in 2026 is set by three measurable axes — module shipments (GW), polysilicon output (tonnes), and inverter revenue — with Chinese integrators and Tier-1 silicon makers crowding out European oil-and-gas entrants in public revenue tables.

China's diode/transistor/semiconductor export value fell to USD 3,956.068 million in May 2026, down from USD 4,845.817 million in April 2026, per the General Administration of Customs via CEIC; long-run average is USD 1,714.425 million/month over 397 observations since 1993.

Eight forecasters now size the 2026-2030 edge computing market between USD 39.6 billion and USD 111.34 billion for 2026, with 2030 endpoints spanning USD 157.91 billion to USD 424 billion, and 2031-2035 endpoints from USD 267.42 billion to USD 547.16 billion at 23.3%-37.9% CAGR. The spread drives de
The global low voltage cable market was valued at USD 158.9 billion in 2022 and is projected to reach USD 278.7 billion by 2032 at a 5%-plus CAGR, anchoring cable-and-wire TAM growth through 2026.
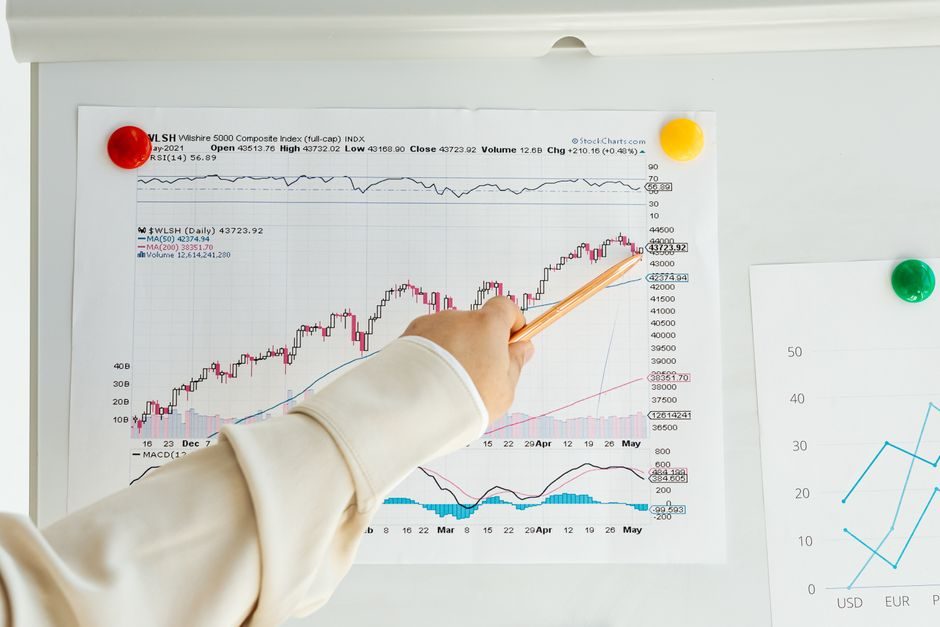
Inner Mongolia samarium oxide and NdFeB magnet-feed oxides moved into July 2026 with renewed price pressure, with the global rare-earth metals market valued at US$ 14.1 Bn in 2025 and projected to reach US$ 30.9 Bn by 2036 at a 7.4% CAGR.

Global high-end AI server shipments are projected to climb from 639,000 units in 2024 to 1.323 million in 2025, with US hyperscalers holding over 60% of demand and GPU/ASSP platforms reaching 71% share. Through 2026, supply diversification, CoWoS capacity, and enterprise AI deployment are reshaping

Top e-axle suppliers for 2026 are dominated by Tier-1 automotive drivetrain OEMs (Bosch, ZF, Dana, BorgWarner, Allison) plus EV-native players (BYD, Tesla, Nidec), evaluated on peak power, integration, and 800 V architecture readiness. The supplied 2026-07 research sources do not include any e-axle
Global zinc ingot supply in 2026 is dominated by integrated miners and smelters (Glencore, Korea Zinc, Nyrstar, Boliden, Hindustan Zinc), with Chinese pure-zinc ingot 99.99%/99.995% trading at US$2,000-3,000/tonne on Made-in-China.com. Spec-driven buyers should weight purity grade, LME delivera

Specialty chemicals in 2026 are being reshaped by four forces: bio-based feedstocks, SSbD-compliant chemistries, AI-augmented R&D, and tighter differentiation through green portfolios, with APAC capturing 63% of forecast 2025-2030 growth and the global market adding USD 381.92 billion at a 6.3% CAGR
U.S. dry shale gas output is projected to reach 38.0 Bcf/d in 2026 and 39.3 Bcf/d in 2027 per the EIA STEO, while global demand hinges on LNG export build-out and power-sector switching. Industrial buyers should size gas-analyzer and detection budgets to that throughput band.
Caterpillar, Komatsu, Sandvik, Epiroc and Liebherr anchor the 2026 mining-equipment majors, with diesel-electric drive, autonomous haulage and battery-electric loader pilots defining the spec race for mining dump truck fleets.
European Union nickel powders and flakes demand is set to climb through 2030 on EV-battery cathode precursor and stainless steel backfill, with BAC Reports tracking 2021-2025 production, consumption and price baselines and a 2026-2030 forecast horizon. Specifiers should treat Class I nickel pow
Global machine vision system market estimates diverge sharply in 2026: IndustryARC pegs the hardware/components segment at $17.20Bn by 2027 at 7.1% CAGR, while Allied Market Research projects the broader system market reaching $159.2Bn by 2032 from $49.7Bn in 2023 at 13.9% CAGR. Asia-Pacif

Wind turbine blade market reports in 2026 are priced from USD 2,650 (June 2025) to USD 5,850 (Jan 2026), tracking materials, blade-length tiers and offshore rotor demand. Procurement should weigh composite supply, vessel capacity and turbine-component forecasting as interlocking constraints, not sin
The 2026 global bearing supplier landscape splits into four engineering tiers — Japanese precision houses (NSK, NTN, Nachi, JTEKT), European specialists (SKF, Schaeffler/FAG/INA, Timken, SKF-Resolve), Chinese volume champions (LYC, ZWZ, Toprol), and US/Indian mid-tier — with selection driven by dN,
Global aluminum demand is on track to reach 120 million tonnes by 2030 at a 4.2% CAGR (2024–2030), with structural supply deficits widening as EV, renewable, and construction demand outpace new smelter capacity through 2026.
ExxonMobil, Chevron, Shell, TotalEnergies and BP retained the five top slots in the 2026 global natural-gas league table by production and LNG capacity, with Saudi Aramco, Gazprom, PetroChina, QatarEnergy and Equinor rounding out the top ten.
As of 2026-07-03, the top robotics companies 2026 landscape is shaped by three driver lanes — industrial arm OEMs serving automotive cells, humanoid platform developers, and warehouse AMR vendors — with vendor lists still dominated by ABB, FANUC, KUKA, Yaskawa, Universal Robots and emerging Chinese

Global food processing equipment supply in 2026 concentrates in three hubs — Duravant-owned sorting specialists like Key Technology, Chinese OEM platforms, and U.S. regional integrators — with the next Guangzhou IFPE expo scheduled 10-12 March 2027.

EV battery cell prices in 2026 sit well below the 2022 peak on a $/kWh basis, while raw-material volatility, recycling feedstock and 2026 cathode trade flows keep the floor under downward pressure.

Global steel demand in 2026 is led by building & construction (30.6% of 2025 end-use) and basic-oxygen-furnace production (59.8% of 2025 output), with the top 10 producers holding 49% of capacity. EN 1991-3:2026 and EN 1991-4:2026 tighten Eurocode rules for crane, silo, and tank steelwork.
Global stainless steel coil demand is forecast to grow from USD 4.12B in 2025 to USD 6.36B by 2034 at a 4.95% CAGR, while 2026 trade policy shocks (a U.S. 15% Section 122 import surcharge, CBAM compliance, and tightened raw-material quotas) are reshaping competition around carbon, trade compliance,

Global power grid market is forecast to reach USD 367.4 billion by 2028, up from USD 282.1 billion in 2023 at a 5.4% CAGR. Manufacturer share concentration remains anchored in switchgear, transformer, and HVDC converter station supply, where HVDC capex is the chief cost gating factor.
Global mining equipment demand is projected to reach USD 200.9 billion by 2032 at a 4.1% CAGR (2023-2032), with Asia-Pacific holding 58.9% share in 2020 and surface mining equipment at 30.6% revenue share. The 2026-2030 window adds automation, IoT, and electrification to the replacement cycle.

The global heat pump market is projected to grow from $103.0 billion in 2026 to $200.7 billion by 2033 at a 10.0% CAGR, with Chinese OEMs including Power World, SPRSUN, Hodglon and Dabei dominating export volumes across more than 60 countries. Top air source, geothermal and inverter split-type model

Global aerospace robotics demand is projected to grow from $2.9B in 2020 to $9.2B by 2030 at a 12.69% CAGR, while aerospace lubricant demand rises from $2.1B in 2023 to $2.5B by 2026.

Global abrasives demand is projected to expand from $54.17 billion in 2026 to $72.37 billion by 2030 at a 7.5% CAGR, with bonded, coated, and super-precision segments driving $22.18 billion of incremental revenue through EV, aerospace, and electronics-miniaturization demand.
Global test and measurement market share is anchored by Keysight, Fortive, AMETEK, Rohde & Schwarz, NI, and Teledyne per Fortune Business Insights, while the broader measuring and control instruments market reached USD 78.6 billion in 2024 and tracks to USD 110.2 billion by 2030 at 5.8% CAGR [S

The global pharmaceutical equipment market reached USD 27.10 billion in 2026 and is forecast to USD 33.79 billion by 2031 at 4.51% CAGR, with aseptic fill-finish systems holding 29.55% revenue share and North America at 42.52%.
Global activated carbon demand is forecast to expand from 3.5 million tons in 2024 to 5.9 million tons by 2030 at 9% CAGR, with vendor valuations ranging USD 3.9-8.41 billion depending on scope and methodology through 2030.
The global food processing equipment market sits at USD 60.35 billion in 2026, projected to reach USD 87.82 billion by 2035 at a 4.27% CAGR, while the broader processing-and-handling scope hits USD 132.7 billion in 2026 at 6.1% CAGR to 2033. Asia Pacific commands 36–38% of 2025 revenue, sm

Global abrasives market reached USD 47.53 B in 2025, is valued at USD 49.77 B in 2026, and is projected at USD 74.99 B by 2035 at a 4.67% CAGR. 3M, Saint-Gobain, Norton Abrasives, Klingspor, and Carborundum Universal anchor the major-producer list.
The global industrial automation software market was valued at USD 40.83 billion in 2025 and is forecast to reach USD 62.9 billion by 2031 at a 7.45% CAGR, with Siemens, Rockwell, Schneider Electric, ABB, and Emerson leading vendor share. SCADA held 33.92% of solution share in 2025, on-prem
Global rare earth elements market is forecast to reach US$ 6.28 Bn by 2030 at 8.6% CAGR, with Asia Pacific holding over 86% revenue share in 2024, dominated by Chinese supply chains covering mining, separation and magnet alloy output.
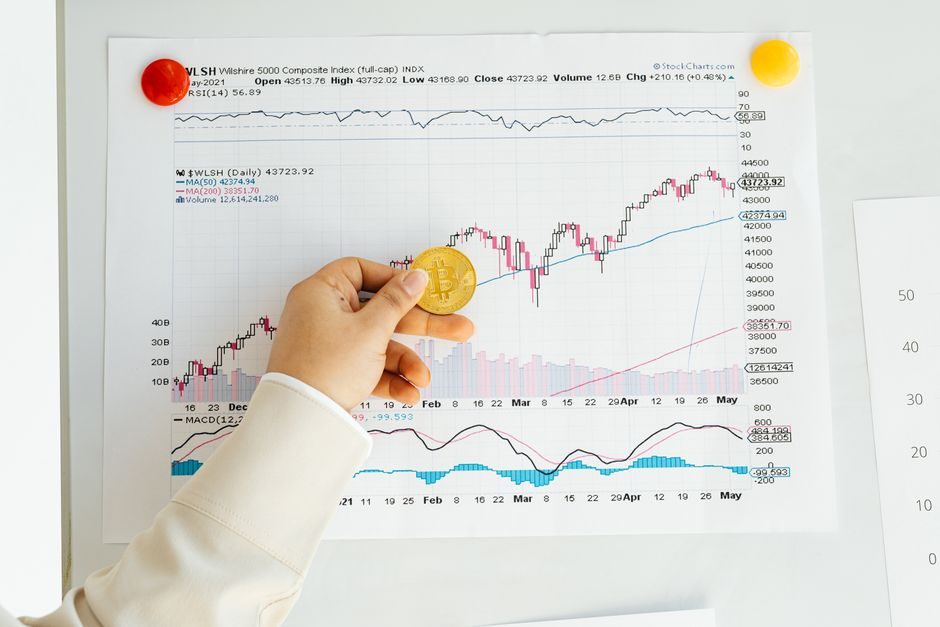
Battery-grade lithium carbonate CIF Asia reached a 27-month high of $12,250/t in August 2021, while a 2023 spot quote of 219,000 yuan/t ($31,800) showed a 57% YTD collapse; 2026 Made-in-China listings cluster LiFePO4 packs at $200-400 and 3.7V Li-polymer cells at $0.95-1.35.

The industrial automation software market is sized at USD 43.87 billion in 2026, projected to reach USD 62.9 billion by 2031 at a 7.45% CAGR, with SCADA holding 33.92% share, on-premises still 55.86% of deployments, and Asia Pacific dominating at 38.22% regional share.

The global packaging machinery market is projected at USD 53.26 billion in 2025, expanding to USD 87.59 billion by 2035 at 5.1% CAGR, with Krones, Tetra Pak, Multivac, ProMach and KHS controlling 34.5% of the food-and-beverage slice.
The global food processing equipment market is valued at USD 60.35 billion in 2026 and is projected to reach USD 87.82 billion by 2035 at a 4.27% CAGR, with no single manufacturer holding more than 5% share and Tetra Pak, GEA, Alfa Laval, Krones, Middleby, Bühler, and Marel leading the field.
The global industrial 5G market reached USD 28 Billion in 2025, is forecast to hit USD 40.16 Billion by 2032 at a 5.60% CAGR, and stays structurally concentrated around Ericsson, Huawei, Nokia, Cisco, and Qualcomm.

Cold chain equipment demand is splitting along two tracks: pharmaceutical-grade storage and AI-enabled reefer monitoring are pulling margins up, while commodity refrigeration is consolidating around six OEMs controlling over 60% of 2026 revenue.

The global membrane water and wastewater treatment market is sized at USD 6.91 billion in 2026, growing at a 7.24% CAGR to USD 9.80 billion by 2031, with reverse osmosis holding 37.14% share in 2025 and Europe leading at 34.30% regional share.

Global cold chain equipment spending is forecast to expand from USD 46.52 billion in 2026 to USD 152.06 billion by 2034, with the monitoring sub-segment alone tracking 12.6% CAGR through 2030. Deep-frozen and ultra-low-temperature services tied to mRNA and biologic pipelines remain the fastest-growi

Global pneumatic actuator demand is forecast to grow from USD 21.78B in 2025 to USD 30.52B by 2030 at a 6.98% CAGR, with the wider actuator market tracking USD 71.22B to USD 100.41B over the same window, driven by valve automation, factory robotics, and electrification of process control loops.

The reverse osmosis membrane market reached USD 5.66 billion in 2026 with 8.18% CAGR to 2031, led by DuPont, Toray, LG Chem, Hydranautics, and Veolia across thin-film composite and spiral-wound formats. Asia-Pacific holds 45.6% revenue share while municipal and desalination use captures 37.85% of gl

The global specialty chemicals market is valued at roughly US$795 billion to US$949 billion in 2026 across major forecasters, with CAGRs of 4.9% to 5.2% and Asia Pacific holding around 40-49% regional share. Competitive advantage now hinges on portfolio mix, regional distribution discipline, and sus
Global first-use tungsten demand is projected to climb from ~162,000 t WO3 in 2025 to 180,000 t by 2030, with ex-China mine supply covering only ~68% of ex-China demand and a 16,000 t deficit forecast even if all 11 announced projects deliver on time.

The global industrial fasteners market reached USD 108.51 billion in 2026 and is projected to hit USD 134.51 billion by 2032 at 3.6% CAGR, with Asia Pacific holding 50.15% share in 2025 and ITW, Stanley Black & Decker, SFS Group, LISI, and Bulten leading the manufacturer rankings.
Top 5 industrial refrigeration OEMs (Danfoss, Johnson Controls, GEA, Mayekawa, Emerson) hold roughly 20% combined market share, with the 2026 market sized at USD 26.49 bn growing to USD 32.41 bn by 2031 at a 4.12% CAGR. Asia Pacific leads with 41.22% of 2025 revenue, ammonia holds 42.41% refrigerant
Zinc ingot demand is projected to grow modestly in 2026 at roughly 1% per ILZSG, with the IZA forecasting a 22% rise in automotive-galvanising demand by 2030. Spot Q2 2026 ingot prices ranged from USD 3,210/MT (China) to USD 4,025/MT (USA).

The 2026 global hydraulic cylinder market sits between USD 16.99B and USD 21.11B depending on the analyst, with Asia-Pacific holding 35.1–42.73% share and double-acting welded designs dominating at 70.2% / 52.3% segment share, while tariffs on steel tubes are reshaping regional sourcing.

Chinese state-linked converters and a Western tooling trio (Sandvik, Kennametal, IMC) anchor tungsten supply, with Xiamen Tungsten at 16.8% share and Asia-Pacific holding 54.2–71.6% of 2025 volume across the major reports.

Global packaging machinery demand is projected to expand from USD 72.25B in 2025 to USD 76.03B in 2026, reaching USD 98.12B by 2031 at a 5.23% CAGR, with Asia-Pacific holding 45.72% share and Middle East and Africa pacing at 6.08% CAGR through 2031.

Global zinc ingot demand was valued at USD 32.46 Billion in 2025, with Hindustan Zinc, Nyrstar, Glencore, Korea Zinc, Teck Resources, Boliden, and China Minmetals identified as the dominant manufacturers across both commodity and high-purity segments.

Global ferrosilicon market is sized at USD 12.12 billion in 2026, projected to USD 16.93 billion by 2036 at 3.4% CAGR, with Asia-Pacific holding 64% regional share and steel-mill deoxidizer demand above 70% of application volume.

Global molybdenum demand is forecast at 329.21 million tons in 2026, rising to 404.79 million tons by 2031 (Mordor Intelligence). The market is valued at USD 5.36 billion in 2026, projected to reach USD 6.42 billion by 2030 at a 4.6% CAGR.

Global cutting tools demand is set to grow from USD 26-30 billion in 2025 toward USD 33-45 billion by 2030, with CAGRs of 3.45-6.2% depending on the forecast scope. EV machining, aerospace titanium backlog, and Asia-Pacific capacity expansion are the principal growth pillars through 2030.

DuPont, Toray Industries, and Hydranautics (Nitto Denko) held star-player status in the 2026 global membranes market, which MarketsandMarkets sizes at USD 8.48 B in 2026 rising to USD 12.74 B by 2031 (8.5% CAGR), with Asia Pacific at 45.3% regional share in 2025.

BASF SE led the global specialty chemicals market with over 9.4% share in 2025, followed by Dow, Evonik, Shin-Etsu and Lanxess in the top five. The market was valued at USD 940.72 billion in 2025, with forecasts spanning USD 1018 billion by 2030 to USD 1377.32 billion by 2035.

The global 5G-A module market is projected to reach US$26.1 billion by 2035 at an 18.1% CAGR for 2026–2035, while the broader 5G Industrial IoT market is set to expand from US$14.65 billion in 2025 to US$263.5 billion by 2034 at 6.1% CAGR, with Asia Pacific holding 34–38% regional share.

The global aluminum ingot market reached USD 98.5 billion in 2025 with China Hongqiao leading output above 6 million tonnes annually, while primary ingots hold roughly 68% revenue share and the top 7 producers control 72% of supply.

The global industrial refrigeration systems market is sized at USD 22.7 billion in 2025, projected to USD 23.6 billion in 2026 and USD 31.7 billion by 2032 (4.9% CAGR), with Asia-Pacific holding 40% share and CO2 the fastest-growing refrigerant at 5.4% CAGR.

Global specialty chemicals demand is forecast to grow from $796.84B in 2026 to roughly $1.0–1.4 trillion by 2030, with consensus CAGR of 5.1–6.3% across major 2026 outlooks, driven by EV, semiconductor, water-treatment, and bio-based applications.
Global galvanized steel sheet demand is projected to grow from USD 118.49 billion in 2026 to USD 157.65 billion by 2031 at a 5.88% CAGR, with hot-dip coils dominating at 73.26% of 2025 volume and Asia-Pacific holding 55.18% regional share.

The global Industrial Ethernet market reached USD 11.71 billion in 2025 and is projected to grow to USD 27.68 billion by 2035 at a 9.48% CAGR, with Asia-Pacific leading growth at 10.37% CAGR on China and India manufacturing programs.
Global hydraulic cylinder demand is forecast to grow from $20.02B in 2025 to $26.06B in 2030 at a 5.4% CAGR, with welded mobile cylinders and the 51-100 mm bore class leading the segment mix and Asia Pacific driving incremental volume.

Global galvanized steel sheet demand in 2026 sits inside a market estimated at USD 116.7-178.1 billion depending on scope, with hot-dip galvanizing leading at 40% share, and seven integrated mills (ArcelorMittal, Nippon Steel, POSCO, Tata Steel, China Baowu, JFE, ThyssenKrupp) controlling the supply

Global stainless steel coil demand is forecast to expand from 14 million tons in 2026 to 17.63 million tons by 2031, a 4.72% CAGR, with flat and cold-rolled product forms dominating volume. Asia-Pacific holds 61.29% of 2025 tonnage and remains the primary growth engine through 2030.

The pneumatic actuator market is led by ABB, Parker Hannifin, Emerson, Rotork, SMC, Cameron, and Festo, with Europe holding 32.9% of global revenue. Scotch-yoke designs and brake-actuator applications dominate product sub-segments today.
Global fluoropolymer demand is forecast to grow from USD 10.32 billion in 2025 to USD 14.13 billion by 2030 at a 6.5% CAGR, with high-purity grades tightening in supply as semiconductor and EV-battery pull intensifies.

Global hydraulic cylinder demand sat at roughly $20.0 billion in 2025, with the top five OEMs holding about 30% of 2024 revenue, Caterpillar at over 8%, and Asia Pacific commanding over 40% of the market. Specifying engineers should match cylinder type and bore size to mobile vs industrial

The cold chain equipment market is sized between USD 29.3B (2026) and USD 46.52B (2026) by major houses, with Carrier, Daikin, Danfoss, Bitzer, and BAC leading. North America holds the largest revenue share, and growth runs at 6.7% to 18.7% CAGR depending on segment scope.

Global ferrosilicon demand is forecast to expand from US$15.7 billion in 2026 to US$20.9 billion by 2033 at a 4.2% CAGR, anchored on EAF steel growth, EV/renewables pull on electrical steel, and silicon-route solar purification.

The global silicone rubber market is estimated at USD 14.52 billion in 2025, on track from USD 15.60 billion in 2026 to USD 29.65 billion by 2035 at 7.4% CAGR, with high-temperature-vulcanized (HTV) grades, liquid silicone rubber (LSR), and medical-grade formulations driving most of the competitive

Global silicone rubber demand is forecast to expand from USD 5.7 billion in 2025 to USD 9.8 billion by 2035 at a 5.5% CAGR, with the broader silicone market tracking toward USD 30.9 billion by 2030 at 7.4% CAGR. Liquid silicone rubber (LSR) is the fastest-growing sub-segment, with projections of USD

Industrial automation software demand is forecast to grow from $43.87-53.6 billion in 2026 to $62.9-96.98 billion by 2030, a 7.45-16% CAGR depending on scope. AI/edge integration, IEC 62443-driven cybersecurity, and software-defined architectures are the named demand drivers across SCADA, MES, and P

Global aluminum ingot demand is forecast to grow at 4.22-5.2% CAGR through 2030-2031, lifting the market from USD 103.6-268.12 billion in 2026 to USD 163.5-329.67 billion by 2031-2035, with secondary/recycled ingots outpacing primary at 5.32-6.4% CAGR.

Global steel rebar demand is forecast to grow at 4.4–5.89% CAGR through 2030, taking the market from USD 166.3 billion to USD 322.2 billion in 2026 toward USD 232.4–381.98 billion by 2030–2034, with APAC holding 53–65% share and EAF process expanding fastest.

Global aluminum ingot market value estimates for 2026 diverge sharply: USD 268.12 billion at 4.22% CAGR through 2031, versus USD 64.4 billion at 3.6% CAGR and USD 193.28 billion at 6.70% CAGR, driven by EVs, construction, and low-carbon supply premiums.

Global ferrochrome demand is forecast to expand from USD 22.83 billion in 2025 to USD 30.61 billion by 2032 at a 4.28% CAGR, driven by stainless-steel production growth and EAF efficiency gains. China, India, Japan, South Africa, and Kazakhstan dominate supply and consumption.

The global packaging machinery market is sized between USD 55.98B and USD 67.7B in 2026 across major analyst houses, expanding at a 4.5–5.63% CAGR through 2035. Asia-Pacific leads with 38.4% of 2025 revenue; the EU PPWR (force Feb 2025, applied from Aug 2026) and U.S. FDA QMSR (Feb 2026 compliance)
The global SCADA market is valued at USD 13.10 billion in 2026 and is projected to reach USD 34.46 billion by 2035, expanding at an 11.35% CAGR. ABB, Schneider Electric, Siemens, Emerson, Honeywell, Rockwell Automation, and Yokogawa remain the dominant manufacturers across industrial and utility dep
Global industrial coatings demand is forecast to reach USD 130.2 billion by 2030 at a 4.1% CAGR (2024-2030) per Maximize Market Research, with parallel estimates of USD 128.4 billion at 2.80% CAGR from Vantage Market Research and a U.S. sub-market growing at 5.1% CAGR through 2030 per Fortune Busine

Asia Pacific commands 57.8% of the silicone rubber market by volume in 2025, with Dow Inc., Wacker Chemie, Shin-Etsu Chemical, Momentive, and Elkem ASA anchoring the global supplier list. The global market reached USD 14.52 billion in 2025, projected to reach USD 29.65 billion by 2035 at a 7.4% CAGR

The compressed air treatment equipment market reached USD 4.4 billion in 2025 and is projected at 6.1% CAGR to USD 7.9 billion by 2035, with Atlas Copco leading at over 22% share. Top five vendors hold 50% of the market.
Industrial edge computing gateway revenue grew from USD 54.46 billion in 2025 to USD 61.67 billion in 2026, with on-premise edge appliances holding 54.05% share and manufacturing taking 42.10% of demand. The category is forecast to expand at a 13.24% CAGR through 2031, with hardware vendors and OT p

Asia Pacific held 74.1% of the 2025 steel rebar market by value, with ArcelorMittal, Nippon Steel, Nucor, Tata Steel, and NLMK positioned as star players; global revenue is forecast to reach USD 250.38 billion by 2031 at 4.4% CAGR, with BOS-process rebar retaining a 68.70% production share over EAF.

Global vanadium market size sits in the USD 2.7-3.78 billion band for 2025-2026 across major analysts, with supply concentrated in Russia, China, and South Africa at over 90% of global share; vanadium pentoxide dominates by type and steel alloys still absorb roughly 85% of demand.

Global ABS demand is forecast to grow at a 5.80% CAGR through 2034, reaching USD 58.82 Bn, with Asia Pacific holding 56.8% share in 2025. Recycled-ABS is the fastest-rising sub-segment inside that envelope, and electronics plus automotive interior trim remain the structural anchors.

Global copper cathode demand is forecast to add USD 9.82 billion between 2025 and 2030 at a 6.3% CAGR, against a backdrop of 23 MMT primary production in 2025, a 330,000 tonne refined deficit, and AI/data-center pull that lifts AI-linked cathode intensity to 58% of data-center copper by 2030.
Global food processing and handling equipment demand is forecast to expand from US$132.7Bn in 2026 to US$200.9Bn by 2033 at 6.1% CAGR, with the hot-processing sub-segment alone adding US$4.68Bn through baking, pasteurization, and frying lines.

Global measuring and control instruments demand is forecast to climb from $940.57 billion in 2026 to $1224.37 billion by 2030, a 6.8% CAGR, with horizontal and precision segments growing at 5.8% and 6.5% respectively, and Australia's import-led market expanding 3.5-5% annually through 2035.
Global reverse osmosis membrane demand is projected to expand from USD 5.0-5.66 billion in 2026 to USD 8.38-10.16 billion by 2030-2033, at a 8.18-10.5% CAGR, led by Asia-Pacific (41-45.6% 2025 share) and thin-film composite elements (62-81.9% share).
LG Chem, Chi Mei, INEOS Styrolution, SABIC, and Trinseo anchor global ABS supply, with Asia Pacific holding 75%+ of capacity and Western Europe concentrated in three producers. Market sized near USD 27 billion in 2025, growing 4.6-5.7% CAGR through 2034.

Global polypropylene (PP) resin demand is set to reach USD 140.64 billion in 2026, with Asia-Pacific holding 36.79% revenue share in 2025. The competitive landscape in 2026 is split between petrochemical majors running licensed technology at scale and trading/compound specialists serving moulders. B

ABS sheet demand is expanding at 5.5% CAGR toward $13.6B by 2034, with Asia Pacific holding 42.3% of 2025 revenue and SABIC leading suppliers; PC/ABS, the premium blend, grows faster at 5.1% CAGR to $8.73B on EV and electronics pull.

Global copper cathode demand is on track to add USD 9.82 billion between 2025 and 2030 at a 6.3% CAGR, with Asia Pacific holding 55–63.8% share and high-purity grades outpacing standard cathode at 8.1–8.9% CAGR through 2034.
Global activated carbon market sits in a USD 3.9-6.04 billion range across 2026 estimates, with Asia-Pacific holding 37.72% of 2025 revenue and coal-based grades leading raw-material share. Calgon Carbon ranks as the dominant GAC producer on capacity.

Pharmaceutical manufacturing equipment demand is projected to grow from USD 21.24 B in 2026 to USD 30.39 B by 2032 at a 6.2% CAGR, with packaging holding a 52.4% equipment share and Asia Pacific the fastest growing region at a 6.9% CAGR through 2032.

Global galvanized steel sheet output is led by ArcelorMittal, Nippon Steel, POSCO, China Baowu, JFE, Tata Steel, and ThyssenKrupp, with hot-dip galvanizing holding 40% of process share in 2025 across a USD 170.3 billion sheet market growing 4.6% CAGR to 2035.

Atlas Copco, Ingersoll Rand, Siemens Energy, Kaeser, and Gardner Denver lead the compressed air market, with the top tier jointly holding an estimated 20–25% combined share. Manufacturing alone drives 40.7% of global demand, and the market is on a 5.14% CAGR path toward USD 31.84 billion by 2035.

Industrial edge computing gateways are a USD 111.34 billion 2026 market growing at 23.3% CAGR through 2031, with manufacturing holding a 22% revenue share and APAC as the fastest-growing region at 17.8% CAGR.
Global industrial refrigeration equipment demand is forecast to grow from US$25.1B in 2026 to US$36.3B by 2033 at a 5.4% CAGR, with industrial refrigeration systems tracked separately at a 6.3% CAGR toward $34B by 2030. Asia-Pacific leads regional share at 33% and data centers emerge as the

Global polypropylene resin demand is forecast to grow from USD 108.7 billion in 2026 to USD 129.5–170.1 billion by 2030–2035, a 4.4%–5.1% CAGR, anchored by Asia-Pacific's 54% volume share and PDH capacity expansion exceeding USD 14 billion in announced projects since 2022.

The global industrial catalyst market is forecast to reach USD 24.8 billion in 2026 and grow at a 3.1–4.1% CAGR through 2030–2034, with heterogeneous catalysts and Asia-Pacific refining capacity driving the bulk of demand. Slower single-digit growth masks a sharp segment split: refining and petroche

The global industrial catalyst market is valued at $27.63 billion in 2026 and is projected to reach $32.1 billion by 2030 at a 3.8% CAGR, with the top five manufacturers (BASF, Johnson Matthey, Clariant, W.R. Grace, and Albemarle) collectively holding over 50% of global share, while heterogeneous ca

Vanadium's 2026 competitive landscape is split between grid-scale VRFB storage (1.6–2.0 M commercial electrolyte baseline, pushing toward 3.6 M demonstrated) and specialty chemical demand, with Alcoa and Australian Vanadium Limited launching an Australian flow-battery study on 2026-08-12. The decisi
Polypropylene resin output is geographically concentrated in Asia Pacific, which holds 54-58% of global market share in 2025; top producers are LyondellBasell, SABIC, ExxonMobil, Braskem, Sinopec, and Borealis.
Global steel rebar demand tracks at 152.96 million tons in 2026 with value estimates ranging from USD 202.27 billion to USD 258.02 billion across published forecasts, and Asia Pacific commands 53% to 74.1% of volume while EAF share grows on recycled-content economics.

Global stainless steel coil demand reached USD 4.12 billion in 2025 and is forecast to reach USD 6.36 billion by 2034 at a 4.95% CAGR, with Tsingshan, Outokumpu, Aperam, Acerinox, ThyssenKrupp, POSCO, and China Baowu anchoring the competitive field across cold-rolled and hot-rolled product splits.
Daikin Industries led the high-performance fluoropolymer field with an 18% share in 2026, followed by The Chemours Company at 15%, while the broader fluoropolymers market grew from USD 11.60B in 2025 toward USD 30.24B by 2036 at 9.1% CAGR, with PTFE holding 44–65% of the resin mix depending on segme

Global molybdenum demand is anchored by steel, which held a 67.3% to 71.08% product share in 2025, with Asia-Pacific controlling 54.08% to 61.4% regionally. Top producers include CMOC, Freeport-McMoRan, Jinduicheng, and Rio Tinto, while supply remains tight under Chinese export licensing.
Thin-film composite (TFC) elements held 81.9% of 2025 RO membrane revenue, with spiral-wound modules at 69.6% and Asia-Pacific at 45.6% of global share, per Mordor Intelligence. Municipal and desalination utilities account for 37.85% of demand, while healthcare/pharma is the fastest-growing end-use

Global compressed air system demand is forecast to grow from USD 20.01B in 2026 to USD 33.82B by 2034 at a 6.80% CAGR, with VSD adoption, IIoT monitoring, and reshored manufacturing driving the 2026-2030 build cycle.

Global polyethylene resin demand is split across LDPE, LLDPE, and HDPE families with 2025 totals near USD 98.5 B, Asia-Pacific at 38% of 2022 volume, and LLDPE holding 70.03% of biaxially oriented PE value while HDPE holds 29.97%. Bio-based and PCR grades such as Dow LLDPE 95060 are now commercial-s

Global pharmaceutical equipment demand is forecast to add USD 5.88 billion between 2025 and 2030 at a 6.1% CAGR, with packaging lines, aseptic fill-finish systems, and single-use bioreactors driving the bulk of capital outlay through 2030.

The pneumatic actuator market is forecast to grow from USD 58.98 billion in 2026 to USD 86.91 billion by 2034 at a 5.1% CAGR, with double-acting and linear units leading share and oil-and-gas plus packaging driving incremental volume through 2026.
Global industrial fastener demand is projected to climb from $110.21B in 2026 to $156.11B by 2033 at a 5.1% CAGR, with North America holding 39.2% share, metals at 91.2% of raw material use, and externally threaded fasteners leading at 35.9% of product mix.

The global industrial coatings market reached USD 164.43 billion in 2025 and is forecast to climb to USD 228.68 billion by 2035 at a 3.35% CAGR, with PPG, AkzoNobel, and Sherwin-Williams leading the competitive field.

Polyethylene led the global plastic resins market with a 35.00% share in 2024 and held the top spot inside crystalline resins, where HDPE alone commands 48.7% of PE demand. ExxonMobil, Dow, LyondellBasell, SABIC, BASF and Formosa Plastics anchor the supplier landscape, with LyondellBasell ranked #1
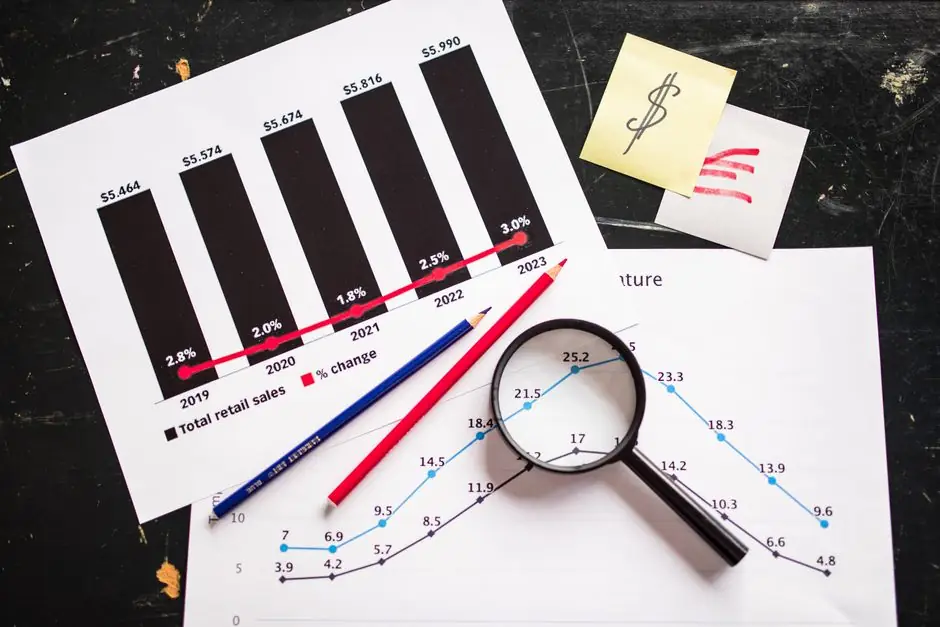
Global PVC resin demand is on track to exceed 50 million metric tons in 2026, with the market valued between USD 51.53 billion and USD 79 billion depending on scope, growing at 4.1–4.2% CAGR through 2035. Asia-Pacific holds 45–50% of consumption, and the top five producers control 32.6–46% of supply

Global PVC resin demand is forecast to grow at 5.2%–5.9% CAGR through 2030, with the market expanding from USD 59.3 billion in 2024 toward USD 88.5 billion by 2030, driven mainly by APAC infrastructure and rigid pipe consumption. Bio-based PVC remains a small but fast-qualifying sub-segment at 5.1%
Global PVC resin market sits at $79B in 2026 with a 4.2% CAGR through 2035, but no single producer dominates: the top five hold only 32.6% and the broader top ten control roughly half of global supply, leaving the rest contested by regional and specialty suppliers.

Epoxy resin global demand is forecast to reach 3.36 million tons in 2026, up from 3.27 million tons in 2025, with 2031 volume projected at 3.99 million tons at a 3.53% CAGR. The market remains moderately concentrated, with Asia-Pacific holding 47.55% of 2025 demand and DGBEA (Bisphenol A/ECH) resins
Global epoxy resin demand is forecast to grow from USD 14.24 billion in 2024 to USD 19.74 billion by 2030 at a 5.6% CAGR, with Asia Pacific driving volume and BPA-based systems retaining 58% share.
Aramid fiber demand is set to reach roughly US$5.2-6.46 billion in 2026 with consensus CAGR of 8.5-11.2% through the early 2030s, driven by aerospace, defense, and tire-reinforcement growth. Para-aramid leads at ~68% of type share, with Asia Pacific holding ~42% regional share. Procurement decisions

Aramid fiber demand is forecast to expand at 3.9% to 9.7% CAGR through 2030 depending on segment, with global value projected between US$5.86 billion and US$6.46 billion by 2030 versus a 2025 base of US$5.81 billion. Para-aramid dominates at roughly 68% of North American volume, while automotive app

DuPont and Teijin anchor a moderately consolidated aramid fiber market, jointly holding the majority share with Kolon, Hyosung, and Yantai Tayho rounding out the top tier across para-aramid and meta-aramid segments through 2026.

Global fiberglass demand is projected to expand from USD 12.5 billion in 2026 to USD 21.0 billion by 2036 at a 5.3% CAGR, with E-glass at 67% product share and rovings at 46%, while high-performance variants track a parallel 6% CAGR into aerospace and wind.

Global glass fiber demand is forecast to grow from 8.34 million tons in 2026 to 10.17 million tons by 2031 at a 4.03% CAGR, with the broader market adding USD 4.91 billion at a 5.4% CAGR through 2030. S-grade high-strength fiber is the fastest sub-segment, projected at a 7.6% CAGR to USD 4

Global glass fiber demand is projected to grow from USD 27.1B in 2025 to USD 34.9B by 2030 at a 5.2% CAGR, with Owens Corning, China Jushi, CPIC, Nippon Electric Glass, and Saint-Gobain leading the manufacturer landscape and Asia Pacific accounting for the largest share.

Global carbon fiber demand is set to roughly double between 2026 and 2030, with the composites market projected at USD 26.4B in 2026 rising to USD 46.1B by 2033 (8.3% CAGR), while pure fiber volumes grow from 245.37 kt in 2026 toward 562.77 kt by 2031. Aerospace, wind energy, and hydrogen pressure v

Toray Industries leads the global carbon fiber market with about 18.2% share, followed by Teijin, Hexcel, Mitsubishi Chemical, and SGL Group, with Asia Pacific holding 38.7% of regional revenue. The T700-grade segment alone is valued at USD 543 million in 2024 and tracks toward USD 864 million by 20
Global magnesium ingot demand is forecast to reach 1.63 million tons by 2031 at a 5.08% CAGR, with the broader metal magnesium market tracking $4.73 billion in 2025 toward $8.01 billion by 2034, a 6.1% CAGR, per Mordor Intelligence and Data Insights Reports.

Global high-purity titanium sponge demand is forecast to grow at 5.2-6.7% CAGR through 2030-2035, lifting the aerospace & defense segment from $1.8B (2026) toward $3.2-3.6B as Western OEMs diversify away from Russian supply and retool with Chinese, Japanese and Kazakh sources.

China holds over 50% of global titanium sponge capacity at 200,000+ MT/yr, with Pangang and Baoti anchoring state-run output above 30,000 t/yr each, while VSMPO-AVISMA, UKTMP, Toho Titanium, and OSAKA round out the four-firm non-China producer map.

Global manganese ore supply tightened through Q1-Q2 2026 on South African logistics bottlenecks and an Australian cyclone-driven guidance cut above 6%, while India, Oman, and the US advanced policy-driven new capacity. Baseline forecasts diverge widely, with a 2.9% CAGR to USD 137.23 million by 2036
Manganese ore demand for 2026 to 2030 will track steel output, with Exxaro projecting steel to remain the dominant first-use consumer and India pushing 300 MTPA capacity by 2030-31. Spot manganese held flat near $4.80/dmtu through mid-2026.

Global manganese ore output in 2026 is led by South Africa, Gabon, and Australia, with South32, Eramet/Comilog, Anglo American, OM Holdings, Jupiter Mines, and Vale controlling most seaborne high-grade supply. Verified 2026 data shows the market valued at USD 17.0 billion, expanding at an 8.4% CAGR

Global cobalt sulfate demand is anchored by battery-grade CoSO4·7H2O (CAS 10026-24-1) used in lithium-ion cathode precursors, with the market valued at $1.8B in 2025 and projected to reach $3.1B by 2034 at a 5.8% CAGR, dominated by Asia Pacific at 48.7% share. Competitive intensity is driven by HPAL

Global cobalt sulfate demand is projected to grow at a 6.8-11.4% CAGR through 2030-2036, with battery-grade material representing 75% of 2026 volumes and EV cathodes the dominant end use. Market value ranges from USD 1.84 billion (2026) to USD 7.8 billion (2026) depending on report scope and grade c
Battery-grade cobalt sulfate (CoSO4·7H2O) supply remains concentrated among Chinese refiners Huayou Cobalt, GEM, and Ganzhou Tengyuan, with Glencore and Umicore holding the integrated Western flank, on a global battery-grade market valued at USD 1,180 million in 2026 per Chemical Research Insight (2

Refined nickel sulfate demand is on track to roughly triple from USD 17.86 billion in 2025 to USD 56.89 billion by 2032 at an 18.0% CAGR, anchored by EV cathode precursor pull from NCM 811 and NCA chemistries. Battery-grade material already represents 85.9% of 2025 volumes, with Asia Pacific (China-

CNGR Advanced Materials led the global nickel sulfate market with 13.2% value share in 2022, followed by GEM (11.0%) and Sumitomo Metal Mining (9.9%), per Prof Research. The battery-grade segment is on track from USD 3.40 billion (2024) to USD 5.67 billion (2030) at 8.92% CAGR.

Global lithium hydroxide demand is projected to expand from 302.60 LCE kilotons in 2026 to 2,105.40 LCE kilotons by 2035 at a 24.80% CAGR, anchored in nickel-rich EV cathode chemistry and gigafactory commissioning. Battery-grade material captures 65.8% of 2025 high-purity volume, with Asia-Pacific h

Chinese refiners anchor the 2026 battery-grade lithium hydroxide supply map, with Albemarle, Ganfeng, Yahua, SQM, and Livent dominating global RFQ shortlists. Battery-grade monohydrate (LiOH·H₂O, CAS 1310-66-3) trades near $1.30/kg on Chinese spot as of 9 July 2026, while anhydrous LiOH (CAS 1310-65

Global lithium carbonate demand is forecast to expand 6.67%-22.74% CAGR through 2031, with battery-grade material controlling 82.6%-82.8% of 2025 volume and Asia Pacific anchoring 47.8%-60% of regional share. The 2026 base case sits between 1.15-1.58 Mt LCE supply, with LFP chemistry driving 80% of

Ultra-high power (UHP) graphite electrodes sized 700mm and 750mm are now the rigid-demand mainstream for EAF steelmaking, with Fangda Carbon, Jilin Carbon, and Liaoning Dantan (120,000 t/yr capacity) leading a Chinese field that competes against SGL Carbon, GrafTech, Showa Denko, Graphite India, HEG

Global graphite electrode demand is forecast at 1.78 million tons in 2026, rising to 2.13 million tons by 2031 at 3.63% CAGR, with UHP grades at 4.12% CAGR and EAF steel accounting for 71.25% of consumption. Premium low-CO2 and battery-grade supply will outpace commodity RP growth.
Global graphite electrode demand is projected at USD 12 billion in 2026, with the top five manufacturers holding 47% market share, China controlling 52% of production capacity, and Asia-Pacific capturing over 64% of regional demand. UHP grade electrodes command 70.11% of 2025 share at a 4.12% CAGR t

The global polysilicon market reached USD 18.5 billion in 2025, with solar-grade silicon holding 88% share and Asia-Pacific dominating 82% of supply. On August 7, 2026, China's top eight producers pledged to end loss-making sales, reshaping competitive dynamics for non-Chinese entrants.

Polysilicon supply in 2026 is concentrated in a handful of tier-1 producers, with China-based Daqo, Tongwei, GCL-Poly, and OCI alongside Wacker Chemie controlling the majority of global capacity. Solar-grade (6N-7N) and electronic-grade (9N-11N) split clearly across different process routes and end-

The global industrial laser market was valued at USD 11.43 Billion in 2025 and is projected to reach USD 20.86 Billion by 2035 at a 6.2% CAGR, with fiber lasers, EV battery welding, and Asia-Pacific capacity driving the bulk of growth through 2030.

Global industrial laser market reached $7.8B in 2025 with a 5.8% CAGR through 2032, while fiber lasers hold 48.4% of the type mix and Asia Pacific captures 42.3–53% of regional revenue. Six anchor vendors (IPG, Coherent, Corning, Jenoptik, 600 Group, Lumibird) lead sources, with Trumpf, Bystronic, A
Welding-robot listed prices on the major Chinese B2B catalog span US$3,400-23,000 per cell in July 2026, with global market sizing from Allied Market Research projecting US$10,784.4 million by 2026 at an 8.7% CAGR. Fanuc, Yaskawa, and OTC Daihen still own the US$30,000-58,000 tier; Estun, Efort, and

The 2026 laser cutting machine market splits into two tiers: high-power fiber platforms (≥6 kW) from European and Japanese OEMs (Trumpf, Bystronic, Amada, Mazak) anchor heavy-gauge work, while a Chinese price tier ships at US$ 7,000 to US$ 30,000 per unit from Suzhou, Jinan, and Jiangsu/Shandong clu

Global laser cutting machine demand is forecast to grow from a USD 4.12–8.01 billion 2025 base to USD 11.4–12.34 billion by 2031–2032 at a 5.16–9.55% CAGR, with fiber and solid-state sources leading and Asia Pacific holding the regional lead. Procurement teams should plan capex against the 2026 base

The global CNC controller segment is forecast to reach USD 7.0 billion by 2033 at a 6.6% CAGR, with FANUC cited as holding roughly 65% of CNC controller share globally and dominating high-precision segments since 1956. Siemens, Mitsubishi, and Heidenhain round out the leadership tier

Brazil's industrial gearbox and geared motor market is sized at USD 1.16 billion in 2025 with a 2025-2030 CAGR of about 5.0%, while global drivers (IEA forecasts of 3.6% annual electricity demand growth and US utility capex of about USD 1.3 trillion through 2030) point to broadly firmer replacement

The global industrial gearbox market is valued at $27.4 billion in 2025 and is projected to reach $45.8 billion by 2034 at a 5.8% CAGR, with Siemens AG, SEW-Eurodrive, Bonfiglioli, Flender, and David Brown Santasalo identified as the leading suppliers commanding meaningful share in a moderately conc
Global ball screw demand is forecast to expand from roughly USD 4.8 billion in 2026 to USD 8.6 billion by 2035 at a 6.70% CAGR, driven by CNC, semiconductor, and humanoid robot actuator end-uses. Procurement should lock accuracy grade, preload, dynamic load rating Ca, and DN value before vendor shor

Global ball screw demand reached $3.55B in mid-load and $729.5M in high-speed segments in 2025, with THK, NSK, HIWIN, Bosch Rexroth and Schaeffler setting the precision tier while Chinese suppliers like Luying capture cost-flexible volume.

Profiled-rail ball guides (HGR/HGH 15–45 mm) remain the 2026 default for new CNC and automation builds, while crossed-roller MONORAIL and solid-rail cam-roller formats gain share in heavy, dirty or high-precision cells; the global linear motion market tracks USD 11.74 Bn in 2026, compounding at 7.8%
Global linear guide rail demand is forecast to expand at 5.4-7.9% CAGR through 2030, with the market reaching USD 7.59 Bn by 2032. Asia Pacific holds 42.8-55% share, and ball guides dominate at 38.5-57.6% of the mix.

RV reducer demand from industrial and humanoid robots is forecast to exceed 7.5 million units globally between 2025 and 2028, with China's 2025 industrial robot output already running at 148,000 units in Q1 (+26% YoY) and humanoid robot reducers alone projected to surpass 14 billion yuan by 2030. Do
Nabtesco holds the majority share of the high-precision RV reducer segment above 80 Nm, while four Chinese suppliers (Leaderdrive, Greenharm, Qinchuan, Shuanghuan) compete in the 20-800 Nm mid-range with 4-8 week lead times versus 12-24 weeks from Japan.
Harmonic reducer competition in 2026 is structured around four hard specs: 30:1–320:1 single-stage ratios, 3–1,236 N·m rated torque, ≤1 arcmin backlash on premium grades, and 20–25 N·m/arcmin torsional stiffness. Japanese incumbents HarmonicDrive, Nabtesco, and Sumitomo still lead on precision, whil

Harmonic reducer demand is bifurcating in 2026: the broad harmonic gear market sits near USD 528 M against a USD 1.31 B robot subset, while humanoid-joint usage is forecast to compound at 46.3% CAGR to USD 750 M by 2032.

The 2026 harmonic reducer market is moderately concentrated at the premium tier, with Harmonic Drive Systems, Nabtesco, Sumitomo Heavy Industries, Leaderdrive and Zhejiang Laifu leading a top-five block, while Chinese ODMs in Guangdong and Jiangsu now cover 14–50 mm cup formats at US$100–400 FOB.

Ten vendors (Yaskawa, Mitsubishi, Fanuc, Siemens, Bosch Rexroth, ABB, Delta, Kollmorgen, Schneider, Rockwell) hold roughly 90% of 2026 servo drive sales, segmented across 50 W to 55 kW, with selection decided by bus protocol, current-loop bandwidth, and feedback resolution rather than brand.

Global servo drive demand is forecast to grow from USD 18.43 billion in 2026 to USD 26.93 billion by 2032 at 6.50% CAGR, with Asia Pacific capturing the largest share and robotics applications expanding at 9.3% CAGR through 2034. Specifiers should plan around closed-loop, EtherCAT-capable, low-volta

The global warehouse robotics market is valued between USD 10.96 billion and USD 15.26 billion for 2026, with Asia Pacific holding the largest share at roughly 39.5%. Hardware still captures about 70% of outlay, while software is the fastest-growing layer at an 18.4% CAGR through 2031.
The global warehouse robotics market will grow from $6.21B in 2025 to $7.08B in 2026 at a 14.1% CAGR, and is forecast to reach $11.91B by 2030 at 13.9% CAGR per The Business Research Company's 2026-2030 outlook.
The 2026 warehouse robotics market is marginally fragmented: the top ten named vendors (KION, Honeywell, KUKA, BlueBotics, Omron, ABB, FANUC, Kawasaki, Hirata, Delta) sit in a $7.07B (2023) envelope projected to $31.34B by 2032 at 18.2% CAGR, with Asia Pacific holding 38.5% share and Amazon Robotics
Universal Robots leads the 2026 cobot market at roughly 14.8% global share, with three Chinese suppliers (Dobot, AUBO, JAKA) collectively holding about a quarter. Payload spans 0.5–35 kg, repeatability clusters at ±0.02–0.05 mm, and ISO/TS 15066 governs every cell.

Global collaborative robot shipments hit nearly 58,000 units in 2025 (+14.5% YoY) and are forecast to more than double by 2030, while 2026 revenue sits between $2.8B and $4.0B depending on source, with terminal 2030 estimates spanning $7.67B to $91.3B (CAGR 21.4–42.4%).
The collaborative robot market reached roughly USD 2.3 billion in 2025, with IFR reporting a 46% jump in 2025 installations. In Q3 2026 the leading manufacturers by payload breadth, verified deployment, and integration openness are Elite Robots, FANUC, ABB, KUKA, and Techman Robot, with Chinese supp
Commercial humanoid robots in 2026 span a $4,900 (Unitree R1) to $420,000 (Boston Dynamics electric Atlas) price band, with 23-200 degrees of freedom, 0-50 kg payload, and 2-5 hour battery life. The market now has at least eight shipping manufacturers; selection is driven by payload-per-dollar, dext

UBS expects global humanoid robot demand to reach 30,000 units in 2026 (up to 40,000 in an upside case), with the volume peak concentrated in 2027 to 2028. Industrial pilots in automotive and logistics are driving 6–15 month payback periods, while Tesla, UBTECH, and Boston Dynamics expand capacity t

LiDAR in 2026 splits into three vendor clusters: Chinese dToF and MEMS houses (Hesai, RoboSense, Benewake), North-American digital 3D players (Ouster, Velodyne), and European industrial-2D incumbents (SICK, Hokuyo), with a 14.8% CAGR anchored on a USD 3.4B 2026 base. Buyers select on five numbers: r

Global automotive-grade 3D LiDAR revenue is anchored at USD 1.8B in 2026 with a 21.4% CAGR toward USD 10.31B by 2035, while the broader LiDAR market sits at USD 3.4B in 2026 at a 14.8% CAGR. Solid-state architectures, MEMS-mirror dominant in Europe and India, Flash expanding in China, drive the volu
Global 3D LiDAR safety scanners reached $3.8B in 2025 (11.5% CAGR to 2033), with Asia Pacific holding 44.2% revenue share. Hesai, RoboSense, Luminar, Valeo and Innoviz lead automotive 905/1550 nm units; RIEGL, SICK, Ouster and Velodyne dominate industrial mapping. Selection hinges on range, point ra

Tier-1 platform vendors (Cognex, Keyence, Basler, SICK, Teledyne) still lead 2026 machine vision system RFPs, but the price gap to tier-3 Asian ODMs exceeds 5x. Smart cameras grow at 10% CAGR to $17.97B by 2035, with 3D vision lifting overall market CAGR to 13.9%.

Global machine vision system spend is projected to rise from $49.7B in 2023 to $159.2B by 2032 at 13.9% CAGR, while the 2026 base tracks $14.95B growing to $21.15B by 2031 at 7.18% CAGR. Asia Pacific leads regional growth at 8.1% CAGR through 2030, and 3D cameras plus logistics bin-picking are the f
Asia-Pacific holds 40.25% of the 2025 machine vision systems market, with the top three suppliers controlling roughly one-third of global revenue. Hardware leads at 65.11%, 2D imaging at 71.03%, and PC-based systems at 58.02% of 2025 share. Cognex, Keyence, and Omron anchor the vendor ranking per Ju

The precision air conditioning segment is consolidating around ten global vendors, with Vertiv, Schneider Electric, STULZ, Daikin Applied, Mitsubishi Electric, Airedale, Rittal, Huawei, Delta Electronics, and GOTTOGPOWER shaping 2026 supply to AI data centers, where Daikin led the broader USD 206.6

Global precision air conditioning (PAC) demand is forecast to grow from USD 2.82 B in 2026 to USD 4.24 B by 2034 at a 5.21% CAGR, with air-cooled units heading from USD 5.66 B (2025) to USD 9.00 B (2032) at 6.85% CAGR. R-454B, R-32, and HFO refrigerants are replacing R-410A as the core spec gate for

The global precision air conditioning market reached $4.8B in 2025 with Vertiv leading the competitive landscape, while five Tier-1 OEMs, Vertiv, Schneider (Uniflair), Stulz, Rittal, and Huawei, control most PAC/CRAC procurement in mid-2026.

Global UPS demand reached USD 19.32 B in 2026 and is projected to hit USD 27.68 B by 2035 at 5.4% CAGR, with data-center UPS alone at USD 4.48 B in 2026 climbing to USD 6.46 B by 2031 (7.59% CAGR). Capacity, not demand, is the binding constraint.

The global data center UPS market is led by Schneider Electric (~18.2% medium-voltage share), Vertiv, Huawei, Eaton, and ABB, with the segment projected to grow from $8.76B (2025) to $12.47B (2030) at 7.3% CAGR as modular architectures and lithium-ion chemistries displace legacy VRLA installations.

Immersion cooling in 2026 splits into single-phase (62-70% share) and two-phase (fastest-growing at ~23-24% CAGR) camps, with phase-change/IT-equipment immersion sized between USD 520 million and USD 1.04 billion in 2025 and projected to reach USD 2.34-4.88 billion by 2032, driven by 120 kW GPU rack
Immersion cooling demand is forecast to grow at 14.1% to 27.3% CAGR through 2030-2036 depending on scope, with AI data center single-phase leading at 38.4% share and two-phase expanding fastest on 27.3% CAGR as chip TDPs cross 1,000 W.
TrendForce data shows liquid-cooling penetration of AI chips hitting 53% in 2026, up from 33% in 2025, with the 2026 supplier field split into server-OEM loops, vendor-neutral DLC specialists, and ISO-certified component makers selected on heat load, loop topology, and certification chain.

Liquid cooling for data centers is forecast to grow from USD 3.9-5.7 billion in 2026 to USD 18.6-29.2 billion by 2033, a 25.1-31.5% CAGR, driven by AI rack densities crossing 30-100 kW and chip TDP above 700W.

The 2026 data-center liquid cooling market is split across three functional tiers: server-OEM integrated loops (Lenovo Neptune 6th Gen), independent DLC specialists (CoolIT Systems, LiquidStack, Schneider), and component-tier fabricators (ToneCooling, Koolance, Mstirling, Lian Li). AI training racks

Data center cooling is a USD 31.4B market in 2026, growing to USD 128.3B by 2033 at a 22.3% CAGR, with direct liquid cooling outpacing air at 24.7% CAGR versus air's 5.2% as AI rack densities push past 70 kW per rack.
Data center cooling demand is forecast to expand at a 13.1%–22.5% CAGR through 2030-2034, with the global market reaching $43–60 billion. Liquid cooling is the fastest-growing segment at 26.4% CAGR, driven by AI rack densities of 50–100 kW.
In mid-2026, NVIDIA, AMD, and Intel each field a distinct AI accelerator line, with NVIDIA's H100, AMD's MI300X, and Intel's Gaudi 3 now contested by hyperscaler custom silicon and over $5bn in Q1 2026 AI hardware startup funding.

Global NAND Flash demand is projected to grow 18% in both 2026 and 2027, with the global market reaching USD 75 billion in 2026 and exceeding USD 110 billion by 2030. Bit supply deficit of 4-5% in 2026 will persist through 1H 2027 before easing in 2H 2027 as new Chinese and Korean capacity arrives.

Samsung reclaimed the top DRAM revenue slot in Q2 2026 with 39% share, overtaking SK Hynix (26%) and Micron (25%), while CXMT posted 716% YoY growth at 7% share, per Counterpoint Research.

HBM demand is forecast to grow from USD 35B in 2025 to USD 205B by 2036 at a 16.1% CAGR, with HBM4 ramping in 2026 and per-accelerator HBM capacity scaling from 96-192GB today to 384GB on NVIDIA Rubin Ultra by 2027, while SK hynix, Samsung, and Micron remain supply-constrained through 2030.

Three suppliers control global HBM: SK Hynix holds 50-55% revenue share, Samsung and Micron split the rest, with HBM4 entering mass production in March 2026 across all three vendors.
Global advanced packaging market is forecast at USD 61.8B in 2026 (up 76% YoY), with 2.5D/3D capacity remaining tight through H2 2027. TSMC holds 58% capacity share while FOPLP and hybrid bonding emerge as the next competitive battleground.

Global advanced packaging demand is forecast to grow from USD 42.5-45.1 Bn in 2025 to USD 60-80 Bn by 2030, an 8.6-22.4% CAGR, with 2.5D/3D and CoWoS capacity remaining supply-constrained through H2 2027 before easing.

The advanced packaging market is dominated by Intel, Samsung, TSMC, and four major OSATs (ASE, Amkor, JCET, and one of SPIL/Powertech), with Asia Pacific holding 60.57% of 2025 revenue and 45.3% global share per Market Data Forecast. Market value ranged from USD 43.95 billion to USD 51.65 billion in

The semiconductor packaging market is forecast to expand from $39.55B in 2025 to $60.64B by 2030 at a 9.0% CAGR, anchored by AI silicon, 5G, automotive electrification, and advanced-packaging capacity build-outs through 2026-2030.
Global semiconductor packaging is on track from USD 76.86 billion in 2025 to USD 144.18 billion by 2033 at 7.6% CAGR, with Asia-Pacific holding about 58% share in 2025 and flip-chip technology commanding 48.2% of advanced packaging in 2024.

The 2026 wafer fab equipment (WFE) market is sized at USD 130.76B, growing toward USD 258.11B on AI-driven demand, with ASML, Applied Materials, Lam Research, and Tokyo Electron dominating a top-heavy vendor map. Selection is driven by node generation, wafer size, and deposition technology share.
SEMI projects wafer fab equipment sales at $145B in 2026, rising to $156B in 2027, with the used-tool secondary market scaling from $4.55B (2025) to $10.59B by 2030 at 18.3% CAGR. AI demand, CHIPS funding, and mature-node retrofits drive the 2026-2030 cycle.

ASML leads the wafer fab equipment market with 23.0% WFE share in 2025, up from 15.5% in 2015, as SEMI forecasts global WFE sales hitting $143.9B in 2026 and $200B by 2028 driven by AI and HBM demand.

Global semiconductor lithography equipment revenue is on track to reach USD 30.44-32.16 billion in 2026, growing at a 9.37-9.73% CAGR through 2031-2034, with DUV still holding 67% of unit share and High-NA EUV pulling the next capex wave.

Lithography equipment demand is anchored to a $1.3 trillion 2026 semiconductor revenue outlook and a $145B (2026) to $156B (2027) wafer-fab equipment forecast, with advanced packaging pulling an additional 20%+ equipment growth in 2025 and reshaping where lithography tools ship through 2030.

Global smart meter shipments are projected to reach 186.99 million units in 2026, with smart electricity meters holding a 70.84% market share, while Asia Pacific dominates the market at 48.58% share. Major vendors including Landis+Gyr, Itron, Siemens, Schneider Electric, Xylem, and Badger Meter comp

European and US smart-meter demand through 2030 is anchored by an EU27+3 rollout track now forecasted to 2031, a $1.3T 2026-2030 US utility capex plan, and India's 6.4%/yr consumption growth, with new data-center loads adding 45 GW of US peak demand.

Tesla Supercharger led US public DC fast charging in Q1 2026 with 36,877 ports (51.6% share), while ABB held 15% of global DC fast charger share per IEA-cited data. DC fast captured 77.95% of global EV charging station revenue in 2025, growing at 53.10% CAGR.

US public EV charging ports crossed 242,000 in 2026, up 34.6% year-on-year, with Q2 alone adding 4,382 fast-charge ports across 806 new stations led by Tesla, Walmart, ChargePoint, and Red E.

Global EV charging infrastructure is a US$50–66 billion market in 2026, forecast to reach US$239–493 billion by 2033–2035 at 16–22% CAGR, with India growing 27.67% to USD 1.65 billion and Europe clearing 1 million public chargers by 2030.
ChargePoint led the global EV charging station market in 2025 with over 9% share, while the top 5 (ChargePoint, ABB, Siemens, Schneider Electric, Delta Electronics) held 35% combined. The market was valued between USD 25.5 billion and USD 50.7 billion in 2025 depending on scope definition.
The 2026 e-axle competitive landscape splits between centralized multi-speed architectures led by Dana, ZF, and GKN, and distributed in-wheel systems dominated by Chinese Tier 1s and startups, with EV traction motor volume driving a parallel topology shift toward axial-flux and 8XX-platform high-spe
The global EV e-axle market reached $50.1B in 2025 and is projected to hit $63.5B in 2026, with BYD leading at over 18% share and the top 5 suppliers holding 45% combined. The category is shifting toward 3-in-1 and 5-in-1 integrated architectures at 800V, favoring full-system suppliers over componen

The global EV traction motor market was valued at USD 30.5 billion in 2025 and is forecast to reach USD 101.13 billion by 2032 at a 19.0% CAGR, with North America's commercial-vehicle segment alone scaling from USD 165.5M to USD 2,275.6M by 2029 at 54.8% CAGR. Permanent magnet motors lead on power d

Global EV traction motor demand is forecast to expand from USD 12.5B (2024) to USD 74.1B by 2030 at a 30.2% CAGR, with the 100-500 kW power band capturing 54.9% of 2026 share. Rare-earth-free PMSM, 800 V architectures, and FOC controls are the three dominant design vectors for the 2026-2030 window.

Monopile, jacket, and floating platforms now compete head-to-head as fixed-bottom projects push past 50 m water depth; 6,773 MW installed globally in 2025 and the monopile market alone is sized at USD 1.81 billion for 2026.

Offshore wind foundation demand through 2030 is anchored by a 19% share of global turbine EPC spend and China's 100 GW-by-2030 target, with Europe adding 151 GW of new wind capacity 2026-2030. Monopile, jacket, and floating concrete-steel substructures are the three competing foundati

Fixed-bottom foundations held 99.62% of the offshore wind foundation market in 2025, with Chinese suppliers now supplying 26% of non-APAC installations versus near-zero in 2020. CS WIND Offshore leads monopile output at roughly 20% global share, while the global market scales from $45.2B in 2026 to

The global wind turbine gearbox market is sized at USD 23.92 billion in 2024 and projected to reach USD 45.48 billion by 2033, while competing direct-drive architectures are growing 11.80% per year. Top patent assignees are Ricardo, Solvay, Vestas, Honeywell, and US Synthetic. Fleet replacement, not
Global wind turbine gearbox demand is set to climb at a high-single-digit annual rate through 2030, anchored by 165 GW of new wind capacity added in 2025, a 40% jump, pushing total installed wind to 1,299 GW across 138 countries and pulling aftermarket spares along with it.

Global wind installations are projected to add over 130 GW between 2026 and 2030, with US capacity building toward 48 GW, Europe installing 19.1 GW in 2025, and China targeting 100 million kW of offshore wind. Blade demand tracks these build-out curves, with deep-water and far-offshore designs drivi

Fifteen OEMs hold 95% of 2025 wind turbine installations, with Chinese suppliers at 70% global share. Top three blade makers, LM Wind Power, TPI Composites, and Siemens Gamesa, control over 35% of the rotor blade market.

The U.S. installed 3.3 GW/8.4 GWh of battery storage in Q1 2026, a 54% jump year-over-year, while Europe added 36 GWh in 2025 and is projected to exceed 50 GWh in 2026 toward 138 GWh by 2030. The competitive landscape splits across LFP-dominated Chinese cell suppliers, Korean integrators, U.S. domes
Global grid-scale battery storage deployment hit 108 GW added in 2025, up ~40% year-over-year, with lithium-ion chemistry holding roughly 52% of the stationary storage market share. Top manufacturers include CATL, Tesla Energy, LG Energy Solution, Samsung SDI, Fluence Energy, and Siemens Energy, wit

The battery energy storage market reaches USD 81.6 billion in 2026 with a 9.1% CAGR, while U.S. Q1 2026 installs hit 3.3 GW/8.4 GWh and global capacity scales from 931.7 GW to 3,735.3 GW by 2033 at 21.9% CAGR.

Europe targets 200 GW of battery storage by 2030 under AccelerateEU, with annual installations projected to nearly quadruple from 36 GWh in 2025 to 138 GWh by 2030, while the U.S. expects 600+ GWh on the grid by 2030 and ASEAN storage spend reaches USD 5.43 billion by 2031.
Global energy storage installed capacity is on track to reach 0.54 TW in 2026 and 1.52 TW by 2031 at a 23.05% CAGR, with batteries holding 53.84% of the 2025 mix. CATL, Tesla, BYD, Fluence, and Wärtsilä sit at the top of the integrator and cell-maker rankings.

TOPCon solar cells hold an estimated 60% share of commercial shipments and the dedicated market is projected to grow from USD 13.66 Bn in 2026 to USD 29.83 Bn by 2033 at 11.8% CAGR, anchored by JinkoSolar, Trina, LONGi and a tightening patent moat.

TOPCon (Tunnel Oxide Passivated Contact) solar cells commanded 85–87% of global production share in 2025–2026, with CRU estimating ~85% at the start of 2026 and CPIA/Exawatt putting the 2025 figure at ~87%. The technology dominates crystalline-silicon output but faces a gradual decline as BC cells a
Solar PV glass demand is scaling fast: the global market is projected at USD 22.05B in 2026 and USD 22.43B in 2026 across two forecasts, with CAGR bands of 19.83% through 2034 and 30.04% through 2035, while U.S. capacity expansions by NSG, Caelux/Solx, and JAPRA reshape the supplier map.

Solar demand pulls the global float glass market from USD 171.88B in 2025 to a projected USD 298.65B by 2030, an 11.7% CAGR. US residential solar alone adds USD 13.29B over 2026-2030 at 13.2% CAGR, with US utility capex nearing USD 1.3T.

The global solar cell market is projected to grow from USD 177.07 billion in 2026 to USD 310.39 billion by 2031 at 11.88% CAGR, with HJT, TOPCon, perovskite tandems, and n-PERT architectures competing on efficiency and cost across utility, floating PV, and BIPV segments.

Global solar inverter shipments in 2026 sit on a USD 22.8 billion base market, with string inverters leading the type mix and Asia-Pacific holding 57.6% regional share. Top vendors include Huawei, SMA, SolarEdge, Enphase, and Fronius, competing on AI diagnostics, SiC/GaN power stages, and grid-formi

Wood Mackenzie's 2026 ranking of 23 inverter makers from seven countries, covering roughly 90% of 2025 global shipments, keeps Huawei, Sungrow and Sineng in the top tier by shipped capacity. Asia-Pacific holds 54.4% of 2025 PV inverter shipments, with the global PV inverter market valued at USD 15.2
Four electrolyzer architectures (alkaline, PEM, AEM, SOEC) compete for the green hydrogen market, which IDTechEx values at a projected US$166 billion by 2037 (48% CAGR) while Future Market Insights sizes the narrower equipment market at USD 8.81 billion by 2036 (24.2% CAGR) from USD 1.01 billion in

The hydrogen electrolyzer market is forecast to reach USD 8.81 billion by 2036 at a 24.2% CAGR, with alkaline systems holding 47% product share in 2026 and Asia Pacific accounting for the largest regional share led by China.

Green hydrogen remains under 1% of global hydrogen supply as of mid-2026, with 2025 market size estimates ranging USD 680 million to USD 12.5 billion and 2026 forecasts between USD 14.0 billion and USD 18.2 billion. The 2025-2035 CAGR band across seven analysts spans 31.2% to 80.8%, reflecting diver
Global green hydrogen volume is projected to expand from 0.47 million tons in 2026 to 10.78 million tons by 2031 at an 87.12% CAGR, with China's 15th Five-Year Plan targeting a five-fold production increase and EU offtake economics now driving electrolyzer project bankability.
Green hydrogen's 2025 base is small (USD 11.9-12.5B across six reports) but six independent forecasts put 2034-2035 between USD 115.4B and USD 264.7B at 31.2-40.5% CAGR, with Europe at 45.2-47% share and alkaline electrolyzers at 60-66.6% technology share.

PEM technology holds roughly 42% of the 2026 global fuel cell stack market, with the broader market sized between USD 8.9 billion and USD 16.8 billion depending on analyst scope. North America leads at about 36% share, Asia-Pacific grows fastest at 16.3% CAGR, and stationary SOFC is the strongest su

SOFC and PEM fuel cell stack demand is being pulled by two distinct engines through 2030: stationary SOFC capacity scaling at roughly 20% CAGR, and hydrogen fuel-cell truck stacks riding a USD 2.80B to USD 6.97B market expansion at the same 20.00% CAGR. Total verified global hydrogen fuel-cell truck

Battery management system (BMS) demand is anchored to a 3.6% annual rise in global electricity consumption through 2030, ~35 GWh of new European BESS additions in 2026, and India's USD 68.80 M EV battery swapping market scaling at 25.23% CAGR through 2030.
Top tier in the global battery electrolyte market is concentrated: Samsung SDI leads solid-state with 19.5% share in 2025, while Capchem, Mitsubishi Chemical and UBE dominate liquid LiPF6 supply. Total market hits USD 13.02B in 2026.

The global battery separator market was valued at $11.8B in 2025 and is projected to grow from $13.2B in 2026 to $39.5B by 2033 at a 17.0% CAGR, with wet-process polyolefin separators holding 56.5% of EV-segment revenue in 2024 and ceramic-coated variants forecast to grow at 21.5% per year

Hard carbon anodes reach USD 7.5 billion in 2026, while silicon anode IP and PAA binder systems accelerate to support silicon-carbon anodes approaching 4,200 mAh/g capacity.

Global lithium-ion battery anode demand is split between a $11.03 B graphite-led base in 2026 growing to $31.16 B by 2034, and a silicon-anode segment expanding at 50.16% CAGR from $536.6 M in 2025. Manufacturer share data published in 2026 confirms synthetic graphite holds 56.89% of graphite-anode

LFP overtook NMC in cathode tonnage share at 41.10% in 2025 and is the fastest-growing chemistry at a 24.97% CAGR through 2031, while overall cathode materials demand is projected to climb from 4.85 million tons in 2026 to 14.32 million tons by 2031. The competitive center of gravity is shifting tow

Global cathode materials market reached USD 48.50 billion in 2025, with NMC/High-Ni holding 49% and LFP commanding 41.10% by material, as Asia-Pacific captured 79.10% of 2025 tonnage against North America's 23.5% share.
Solid-state battery makers in 2026 are split between semi-solid cells already powering industrial drones at up to 420 Wh/kg and full-stack automotive programs targeting late-2020s launch. Market sizing varies widely: SNS Insider pegs 2025 revenue at USD 167.76 M, while Grand View Research reports US

Solid-state batteries are forecast to hold roughly 15% of the global EV battery market by 2030, with energy density 2-3x higher than today's lithium-ion cells. Global battery market value is projected to reach $400B by 2030 at a 16% CAGR, while sodium-ion captures about 10% share on lower mater
Asia Pacific holds 54% of the solid-state battery market in 2025, with QuantumScape leading materials suppliers at 14.8% and lithium-metal anodes capturing 55.05% of cell chemistry share. Major players include Toyota, Samsung SDI, LG Energy Solution, Solid Power, and ProLogium.

CATL targets sodium-ion cell cost parity with LFP by end of 2026, while global market size estimates for 2026 range from USD 0.54B to USD 25.20B depending on segmentation, with Asia Pacific leading at 45.6% share and stationary storage dominating applications at 71.8%.

The sodium-ion battery market sits at roughly USD 0.5–2.2 billion in 2026 across major trackers, with forecasts converging on double-digit CAGRs through the early 2030s, and Asia-Pacific manufacturers, led by CATL and HiNa Battery, controlling the bulk of installed production capacity[S

The 2026 battery pack landscape splits into two diverging tracks: EV-grade structural safety design has matured into a four-cluster IP field anchored by NSGA-II multi-material enclosures (deformation held under 2 mm, mass cut 17.62%), while consumer portable packs remain a USD 19.38B (2025) to USD 7
CATL held more than 40% of the global EV-battery market in 2024, with BYD as the clear #2, while the top five cell makers (CATL, BYD, LG Energy Solution, Panasonic, Samsung SDI) control about 65% of lithium-ion capacity.

Global battery cell demand is set to expand at a 3.6% annual electricity-demand CAGR through 2030, with European BESS additions reaching ~35 GWh in 2026 and India's battery market climbing from USD 14.01 billion (2026) to USD 23.30 billion (2031) at 10.71% CAGR.

Global nuclear power market value is estimated at USD 38.30 Bn in 2026, expanding at a 4.3% CAGR to USD 51.43 Bn by 2033, while installed capacity reaches 409.90 GW in 2026 at a slower 0.73% CAGR. PWR/PHWR designs hold 39.3% of market share, and North America leads regional demand at 36.2%
Aerospace commodity pricing in 2026 is shaped by titanium, specialty plastics, valves, and avionics demand. Plastics sit at $1,133M by 2026 (5.4% CAGR), titanium CNC parts list $1–5/piece, and A&D M&A is repositioning supply chains.
Global nuclear power capacity sits at 409.90 GW in 2026 and is forecast to reach 425 GW by 2031, with PWR technology leading installed share at 72.8%. The USA holds 30% of worldwide nuclear generation, Exelon leads US operators, and the equipment segment is dominated by Asia-Pacific at 35.3% [S

Global offshore wind hit 92 GW installed in mid-2026 with EnergyPulse forecasting 230 GW by 2035; the 2026 outlook hinges on >13 MW turbines (67% of 2025 installs), 8.2% fleet failure rate, floating wind scaling, and 644 monopile/145 jacket foundations installed last year.
Global offshore wind installations are forecast to more than double between 2026 and 2030, reaching 327 GW of new capacity by 2035 per GWEC, with annual additions accelerating from ~10 GW/yr in 2026-2030 to 17 GW/yr in 2031-2040.
Chinese wind turbine OEMs took the entire top five by 2025 capacity, with Goldwind leading at 29.7 GW installed and Envision, Windey, Mingyang and SANY following. Vestas still tops cumulative offshore wind installations past 201 GW, while Chinese suppliers hold roughly 70% of total wind installation
The global battery cell market is sized at USD 93.48 billion in 2026 and is forecast to reach USD 241.96 billion by 2031 at a 20.95% CAGR, with CATL holding 37% share in 2024, cylindrical cells at 53.5% of 2025 volume, and solid-state variants tracking a 40.5% CAGR through 2031.
U.S. dry natural gas production supplied 38% of total U.S. energy in 2025 and is projected to rise 20%–40% by 2050, with LNG exports scaling from 15 Bcf/d to over 30 Bcf/d. Global market values diverge sharply, from $918.7 B in 2026 to $1.98 trillion by 2035, with renewable natural gas compound

Global natural gas demand is projected to grow at 4.26 trillion cubic metres in 2026 with low-to-moderate expansion, while Henry Hub prices range $3.00–$3.90/MMBtu in 2026 and $1.16–$4.27/MMBtu by 2030 across major forecasters.
Global natural gas market size is projected to grow from $918.7 billion in 2026 to $1.12 trillion by 2033, with U.S. industrial demand and LNG export expansion driving the largest share gains. Eni, BP, Shell, and TotalEnergies dominate the upstream and integrated value chain.
Global connector demand is forecast to grow alongside a 3.6% annual rise in world electricity consumption through 2030, with US data-center load scaling from 60 GW (2025) to 180 GW (2030) and cable demand compounding at 6.6% CAGR to $422 billion by 2030.
The global connector market reached USD 77.41 billion in 2026 and is projected to hit USD 113.48 billion by 2036 at a 3.9% CAGR, with TE Connectivity and Amphenol holding the top manufacturer positions across automotive, telecom, and filtered sub-segments.
The global wire and cable market was valued at USD 308 billion in 2025 and is forecast to reach USD 422 billion by 2030 at 6.6% CAGR, while North America grew from USD 37.71 billion in 2025 to USD 39.45 billion in 2026 at 4.62% CAGR, with Prysmian, Southwire, and CommScope holding roughly 46% of 202
Global wire and cable demand is on track from USD 308 billion in 2025 toward USD 422 billion by 2030 at a 6.6% CAGR, with India's market adding USD 2.41 billion at 4.5% CAGR through 2030. Power cable, building wire, subsea HV, and data-center optical fiber lead segment growth, while IEA forecasts el
Global wire and cable demand is projected to grow from $230.9B in 2025 to $410.7B by 2034 at 5.17-6.59% CAGR, with Prysmian leading by share and revenue after absorbing General Cable in 2017, and copper still dominating conductor material.
China's industrial valve market hit RMB 238 billion in 2024 revenue with 6.2% growth, while nuclear and deep-sea specialty segments lag below 30% domestic substitution. A weighted six-criterion framework (R&D 35-40%, quality 20-25%, market 15-20%, project 10%, reputation 5-10%, service 5%) separates

Industrial pump demand for 2026-2030 is shaped by a 3.6% average annual global electricity-demand growth, AI data-centre loads pushing towards ~945 TWh by 2030, and a soft EU industrial-production backdrop in spring 2026, favouring pumps tied to power, water and AI infrastructure over general-proces
The global air compressor market is sized at USD 35.21 billion in 2026 with a 4.61% CAGR through 2031. Atlas Copco, Ingersoll Rand, Siemens Energy, and Kaeser jointly control 35-40% of 2025 revenue, while Chinese suppliers like Kaishan are reshaping the mid-market tier through aggressive pricin

Atlas Copco, Ingersoll Rand, Siemens Energy, and Kaeser jointly control 35-40% of the global air compressor market, with US demand valued at USD 3.96 billion in 2024. Manufacturing accounts for 28.7-40.7% of application share depending on segment scope.

2026 pneumatic-system buyers face a three-tier global supplier map: Tier 1 brands (SMC, Festo, Camozzi) sell certified performance at premium cost; Tier 2 Chinese OEMs compete on lead time, customisation, and total cost of ownership; Tier 3 regional rebuilders round out the long tail. Selection is n

Global pneumatic component revenue is split across divergent 2026 estimates: USD 18.66B (components only) versus USD 37.41B (full pneumatic equipment), with Asia-Pacific holding 48.3% of the narrower scope. Valves, actuators, and FRL units dominate segment share, while no single OEM commands a clear

Global hydraulic components and systems for industrial use are valued at USD 50 billion in 2025, projected to reach USD 75 billion by 2034 at 5.5% CAGR. The market remains fragmented, with Parker Hannifin, Danfoss, Gates, Bosch Rexroth, and Eaton shaping competitive dynamics through consolidation, M
Bosch Rexroth, Parker Hannifin, Danfoss, Eaton, HYDAC and Kawasaki together anchor a medium-concentration global hydraulic equipment market sized at USD 44.25 billion in 2026, forecast to USD 56.63 billion by 2031 at a 5.05% CAGR. Pumps lead equipment mix at 27.85%, mobile hydraulics dominate applic
Global bearings demand is forecast to grow by USD 17.90 billion between 2026 and 2030 at a 3.4% CAGR, while the industrial-bearings slice is projected at a 9.23% CAGR from a 2026 base of USD 59.66 billion, lifted by EV drivetrains, onshore wind slewing rings, and smart predictive-maintenance bearing

SKF leads the global bearing market at roughly $9.3B FY2024 revenue, with Timken, NSK, JTEKT, NTN, and Schaeffler rounding out the top tier, while the total bearing market is projected to reach $145-156B in 2026 depending on source.

The global machine tool market is projected to expand from $123.7B in 2026 to $183.5B by 2033 at a 5.8% CAGR, with Asia Pacific holding 56.2% share. CNC adoption gaps between China (~30% in 2015) and Japan/Germany (70-90%+) define the competitive frontier.
Global machine tool demand is forecast to grow from USD 123.7B in 2026 to USD 183.5B by 2033 at a 5.8% CAGR, with CNC, India, and tariff-driven reshoring reshaping the 2026-2030 mix.
DMG Mori, Mazak, Okuma, Doosan and Tongtai lead global multi-tasking CNC machine tools, with Renishaw and Hexagon AB commanding the machine tool touch probe segment. The robotic polishing machine top five hold 37.31% revenue share, per 2017 GIR data.

Global CNC machine market sits between USD 108.58B and USD 109.36B in 2026, with two research houses forecasting 8.7% and 11.10% CAGR through 2034. The 2026 competitive edge has shifted from spindle hardware to software, AI-assisted quoting, and high-mix low-volume throughput.
CNC machine demand is forecast to grow from USD 96.85 billion in 2026 to USD 187.54 billion by 2033 at a 9.9% CAGR, with Asia Pacific holding 38.7% regional share and Automotive at 38.5% of end-use demand. Lathe machines lead by type, while Industry 4.0 integration, 5G-enabled predictive maintenance

Global CNC machine demand is being shaped by Chinese suppliers expanding into 78 export markets and aerospace-focused builders scaling 5-axis gantry platforms, with vendor share data still dominated by fragmented regional players rather than a single global leader.

Underground mining-equipment competition in 2026 is a three-tier field: tier-1 OEMs (Caterpillar, Sandvik, Epiroc, Normet, DUX/Eimco legacy) for new production fleets, tier-2 specialist builders like Getman for production-support mobile equipment, and tier-3 dealers and India-based parts suppliers (
Global mining equipment market is led by a tiered supplier set: Tier-1 majors (Caterpillar, Komatsu, Sandvik, Epiroc) plus India/China regionals like J.B. Engineers, JXSC Mineral, and Hebi Wanfeng. Underground equipment alone is valued at USD 24.03 billion in 2023 and is projected to reach USD 35 bi
The seawater desalination systems market is segmented by technology (RO, MSF, MED, ED/EDR) and region, with the manufacturer list typically dominated by EPC and membrane specialists rather than consumer brands. The provided 2026-08-18 research feed only carries an abstract-level 2019 GIR scope note

UBS Securities projects Chinese petroleum demand will peak in 2029 and turn negative after 2030, with gasoline and diesel already past their peaks. Diesel is forecast at 157 Mt by 2030, gasoline at 138 Mt, reshaping petrochemical capex toward aviation kerosene, LPG, and naphtha.

The global petrochemical equipment supply base is fragmented across regional specialists, with no single vendor holding more than a low-single-digit share of the overall market; consolidation is concentrated in valves, flanges, and fittings rather than finished polymers.
Global LNG supply shifts from a 2025-2026 tight balance into a structural oversupply starting in 2027, with 2026-2030 capacity additions totalling roughly 202 million tonnes and US-Qatar accounting for about 70% of new liquefaction. Total demand is projected to reach 560 million tonnes by 2030 again

LNG market reached 511 MTPA in 2025 and is projected at 553.16 MTPA in 2026, with Shell holding 16.80% of global LNG trading volume, the largest single-company share.

Commercial satellite transponder leasing reached a global market value of US$ 22.10 billion in 2025 and is projected to reach US$ 49.27 billion by 2034 at a 9.3% CAGR, per a 2026-benchmark transponder leasing model. The competitive arena is consolidating around five fleet-operator archetypes defined
Global satellite manufacturing is forecast to reach $27.20Bn by 2030 at a 15.3% CAGR, with the satellite communication market adding USD 16.34Bn at 10.5% CAGR through 2030, driven by LEO mega-constellation deployments and direct-to-device rollouts.

Global satellite manufacturing is on track to reach $27.20 billion by 2030 at a 15.3% CAGR, with SpaceX Starlink alone accounting for nearly 70% of 115 Falcon 9 launches in 2024. Electric propulsion satellites, valued at $35 million in 2019 with a 33.4% CAGR, remain dominated by ArianeGroup, Busek,

The 2026 commercial drone competitive landscape splits into three camps: drone service providers, geospatial software companies, and Drone-as-a-Service (DaaS) vendors, with DroneDeploy, AeroVironment, and Terra Drone leading the data and analytics segment per a 2026-2035 market report.

Drone demand 2026-2030 is bifurcating: swarm and counter-drone defense is expanding at 25-27% CAGR, education-drone spend adds ~USD 1.2 billion, while EU Drone-as-a-Service platforms open a new compliance-led buying channel under EASA rules.
Global drone market share by manufacturer remains dominated by DJI at the consumer/commercial tier, with the component ecosystem spread across 30+ brands including Autel, Holybro, CUAV and T-Motor, per World Drone Market listings as of 2026-08-09.
OLED demand is bifurcating in 2026: 14-inch laptop panels with 240 Hz QHD specs are shipping in volume on RTX 50-series gaming SKUs, while supplier competition tightens on small-to-medium OLED lines. Watch brightness, refresh, and burn-in warranty as the real selection gates.

The OLED panel market in 2026 is led by Samsung Display and LG Display at the large-area/AMOLED tier, while BOE Technology sits as the principal Chinese challenger; mid-size and small-format PM-OLED and AMOLED module supply is dominated by Shenzhen-based custom houses such as Limito Technology and U

Display panel competition in 2026 hinges on four technologies: LED, LCD, OLED, and quantum dot, with OLED capturing premium video-wall and signage slots. Allied Market Research sizes the interactive display space at $14.63B in 2018, projected to $29.19B by 2026 at an 8.80% CAGR.

Display panel demand over 2026-2030 tracks wider electrification and digital capex, with global entertainment and media revenue growing at a 3.4% CAGR to US$4.2 trillion by 2030 and global electricity demand expanding at 3.6% annually over the same window. Industrial buyers should plan LED

BOE, Samsung Display, LG Display, and AUO lead the global display panel market, with display revenue forecast to grow from USD 109.43 billion in 2026 to USD 137.83 billion by 2032 at a 3.9% CAGR. Micro-LED is the fastest-growing technology, and microdisplays post a 12.3% CAGR over 2026-2032.

Guangdong-based factories (Shenzhen Sroada, Dongguan Kangjuhong) dominate LED landscape bulb sourcing as of July 2026, with PAR36 6W–13W 3000K lamps at US$11.80–14.20 per unit (200-piece MOQ) and IP65 solar garden fixtures at US$0.99–22.50 dominating B2B listings on HKTDC and Made-in-China.com.
The global LED market in 2026 is structurally segmented by application tier: packaged LED chips and drivers are dominated by Chinese, Japanese, and Korean suppliers, while secondary optics (PMMA, PC, glass) and display materials show a more fragmented vendor list. No single vendor exceeds roughly on

The 2026 heat pump market is shaped by EHPA-led European certification (KEYMARK, Quality Label), IGSHPA-driven North American training rollouts across U.S. states and Canadian provinces, and large U.S. wholesale distribution of ductless mini-split units starting near $438.00.

Global heat pump demand is forecast to grow from $130.46 billion in 2026 to $166 billion by 2030 at a 6.2% CAGR, with industrial segments in Europe adding $805.4 million at 5.9% CAGR through 2030.

EV charger manufacturing remains fragmented across 2026, with Chinese OEM/ODM suppliers dominating portable AC and CCS2 connector output while US/EU Tier-1s lead DC fast charger deployments. Selection hinges on OCPP version, ISO 15118 support, and regional connector standards.

Global stationary energy storage capacity is projected to climb from 931.7 GW in 2026 to 3,735.3 GW by 2033, a 21.9% CAGR, with LFP chemistry holding over 90% of electrochemical installations. Chinese cell makers dominate cell supply while C&I and residential OEMs differentiate on cabinet form facto
Global battery energy storage capacity is forecast to climb from 931.7 GW in 2026 to 3,735.3 GW by 2033 at a 21.9% CAGR, with lithium-ion raw materials demand tracking a parallel 9.5% CAGR to USD 127.4 billion. This 2026-2030 build-out rewires BESS procurement around cell sourcing, fire protection,

Chinese cell-and-system makers dominate the global BESS supply tier in 2026, with at least seven LiFePO4-focused factories (DCGROUP, Sunly, Honle, Paichen, Hunan Energy Storage, and Sunskypv) actively courting C&I, utility, and residential orders. Verified signals point to a clear product-stack spli

Global power grid spend is forecast to reach USD 531.6B by 2035 at a 6.30% CAGR, with AI-driven grid management hitting USD 9.9B in 2026 alone. Vendor competition now splits between incumbent HV equipment makers and digital-twin software specialists chasing a 17% data-center demand growth signal.

Global electricity demand is forecast to grow 3.6% annually over 2026-2030, with data centers driving about half of US demand growth, per IEA and IEEE forecasts. AI workloads push global data center power toward 290 GW by 2030, reshaping grid planning.

Global AC motor demand is projected to grow from USD 153.4B in 2026 to USD 199.6B by 2030 at a 6.6% CAGR, with EV traction, axial-flux redesigns, and rare-earth-free rotors reshaping the supplier mix.

The global electric AC motor market is projected to grow from USD 153.4 billion in 2026 to USD 199.6 billion by 2030 at a 6.6% CAGR, with EV traction motors and industrial IE4/IE5 efficiency upgrades driving the bulk of incremental unit demand. Permanent-magnet designs still hold over 75% of the car
WEG's 2026-07-10 acquisition of KATT Hessen GmbH tightens the high-speed induction motor tier in Europe, while AC motor demand tracks USD 127.9B (2023) to USD 199.6B (2030) per Grand View Research, and EV traction motors are tracked by Allied Market Research through 2032.

The global power transformer market reached US$ 28.9 billion in 2025 and is projected to hit US$ 48.2 billion by 2033 at 6.6% CAGR, with the broader transformer market growing from US$ 64.96 billion in 2025 to US$ 69.66 billion in 2026. Competitive pressure centers on capacity expansion, digitalizat

Global transformer supply remains fragmented: the distribution-transformer OEM list spans at least 22 majors, with ABB, Siemens, Schneider Electric, Hitachi, and General Electric the recurring names. Materials-side concentration is far higher, with Hitachi Metal holding about 66% of iron-based nanoc

Infineon, ON Semiconductor, and Mitsubishi Electric anchor the global IGBT supply stack, with the rest of the volume split across Fuji Electric, STMicroelectronics, Toshiba, Renesas, and a deep bench of Chinese suppliers listed on sourcing portals.

The 2026 power semiconductor market is sized at USD 58.8-62.14 billion, projected to reach USD 78.25-93.3 billion by 2031-2034 at 4.9-5.46% CAGR. Wide bandgap materials SiC and GaN are the central competitive battleground, with the SiC/GaN device market expected to grow from USD 1.5 billion (2021) t

Power semiconductor demand 2026-2030 is being driven by SiC and GaN wide-bandgap adoption, EV traction inverters, and HVDC grid build-outs, with the market tracked at $48.9B in 2022 toward a projected $79.9B by 2032 at a 4.9% CAGR. IGBT modules and SiC discretes are the structural winners; mature-no

MinebeaMitsumi acquired all shares of Hitachi Power Semiconductor Device on 2 Nov 2023, adding IGBT, SiC, and module-packaging capacity to its Eight Spears portfolio and targeting ¥300B analog sales by 2030. The move reshapes the IGBT module tier of the merchant power-semi market for EV and industri
The global MEMS sensor market is valued near USD 20.33 billion in 2026, projected to reach USD 49.12 billion by 2035 at a 10.30% CAGR, with the aerospace segment growing faster at 11.33% CAGR through 2034. Competition is consolidating through major acquisitions while AI-enabled edge sensing, ADAS co

Global MEMS sensor demand is projected to climb from roughly US$80 billion in 2024 to over US$150 billion by 2030 at a 12–15% CAGR, with the China market reaching RMB 120 billion at 15–18% growth, anchored by automotive, AIoT, and humanoid robotics demand.
China's domestic PCB EDA market is forecast to clear 14.95 billion yuan in 2025, with 2024 having reached 13.59 billion yuan, and Shanghai Hongkuai's RedPCB is positioning full-stack self-developed design, cloud multi-user collaboration, and AI-assisted simulation as the answer to foreign-vendor loc

The global PCB market remains structurally split between Greater China fabricators and lower-volume regional assemblers, with mainland Chinese suppliers running 60,000 m²/month FR4 lines and US EMS shops holding niches in quick-turn and mil/aero certification work.

Silicon wafer demand from 2026 through 2030 splits into three engines: mature-node 200mm reclaim for industrial and automotive ICs, 300mm prime wafers for AI/HBM and high-performance compute, and 300mm SOI plus silicon photonics platforms for 1.6T and emerging 3.2T transceivers. Lead-times, reclaim

Global silicon wafer manufacturing remains concentrated in Asia Pacific, with Chinese mono- and polysilicon suppliers scaling 150mm, 200mm, and 300mm formats for both semiconductor and solar cell lines as of August 2026.
Analyst consensus tracks global refined copper demand near 27 million tonnes in 2024 with a 330,000 tonne deficit projected for 2026, while the IEA forecasts a 30% supply shortfall by 2040. India alone is set to climb from 1.8–1.9 Mt in 2025 to 3.2–3.3 Mt by 2030, and the global copper market is val

Eight named manufacturers, led by Aurubis, Luvata, and Hitachi Metals, control the high-purity copper supply used in integrated circuits, cables, and semiconductor targets. Spec gate is purity grade (5N vs 6N), with regional production split across Europe, North America, and Asia-Pacific.

Aluminum's 2026 competitive landscape is shaped by Chinese extrusion and die-casting capacity, rising extrusions demand, and tighter alloy-spec competition between primary smelters and secondary recyclers.

China still dominates midstream rare-earth oxide and NdFeB alloy output in 2026, with cerium oxide 99% min priced around US$5,100/ton FOB and praseodymium oxide at US$35,500/ton, while US/EU policy and new non-Chinese refiners like RETi target the separation bottleneck upstream buyers cannot solve.

The global rare earth elements market is projected to reach USD 6.28 billion by 2030, expanding at a 7.5% CAGR over 2026-2030, driven by EV magnets, wind turbines, defense electronics, and demand for non-Chinese separation capacity. RETi's non-HPLC, single-pass purification claims up to 99.999% REE

Fuel cell vehicle (FCV) shipments, IPO activity, and cross-border standards bodies all moved in 2026, reshaping competition between Toyota, Hyundai, Honda, and Chinese state-backed OEMs. Three structural shifts define the 2026 landscape: international coordination via IHFCA, public FCV product refre
Fuel cell vehicle market sits at a $3.7B base in 2025, with Grand View Research modeling 2026-2033 growth across passenger cars, LCVs, and HCVs in four regions. PEMFC remains the dominant light-vehicle stack chemistry, with BMW's third-generation 25% more compact system targeted for the iX5 Hydrogen
The 2026 additive manufacturing competitive landscape is defined by three anchors: a maturing ANSI/America Makes AMSC standardization roadmap (Version 3.0) covering industrial AM sectors, a cluster of end-use shows anchored by Formnext Frankfurt on 17-20 November 2026, and a two-tier peer-review sig
Global additive manufacturing demand is projected to reach $35.24Bn by 2026 at a 19.7% CAGR (2021-2026), while the adjacent additive masterbatch market grows from $2.15Bn in 2025 to $2.87Bn by 2030 at 5.97% CAGR. Standards VDI 3404 and VDI 3405 Blatt 2.3 govern process definitions and metal powder f
Additive manufacturing (AM) is fragmenting across polymer, metal powder bed fusion (PBF-LB, PBF-EB) and hybrid process chains, with no single OEM above low double-digit global share as of mid-2026. Selection pivots on material family, build envelope, monitoring maturity and qualification depth rathe

Global 3D printing demand is forecast to reach USD 118 billion by 2030, growing at a 20.5% CAGR over 2024-2030, with North America holding the 2023 leadership position. Hardware splits into industrial vs consumer printers, materials split across polymers, metals, ceramics, and fibers, and 2026 build
Global 3D printing materials market is projected at USD 10.02 billion by 2030 from USD 3.88 billion in 2025, a 20.9% CAGR, with North America holding the largest regional share and DMLS technology leading growth on metal demand. The competitive landscape remains fragmented across desktop, indus
Global industrial robotics revenue is projected to climb from USD 23.71 billion in 2024 to USD 85.63 billion by 2034 at a 13.7% CAGR, with Fanuc, ABB, KUKA, Yaskawa, Universal Robots and Kawasaki controlling the dominant share of the articulated and cobot segments.

Global service robotics demand is forecast to climb from US$ 46.9B in 2023 to US$ 68.1B in 2026 and US$ 107.8B by 2030, a 12.6% CAGR, while the offshore AUV sub-segment tracks a sharper 15.1% CAGR from US$ 93.11M (2025) to US$ 246M (2032). Spec-driven buyers should anchor on application cla

The Insight Partners' April 2026 outlook puts the global robotics technology market at US$ 138.59 B in 2025, expanding to US$ 601.68 B by 2034 at 17.72% CAGR. Vendor concentration remains thin: the report profiles 10 industrial-robot OEMs (ABB, Fanuc, Yaskawa, KUKA, Mitsubishi, Kawasaki, Denso,

Dell, HPE, and Lenovo hold the dominant x86 rack-server share, with IBM z Systems, Cisco UCS, and Inspur splitting the remaining mainstream tiers; selection is driven by CPU generation, DDR5/PCIe 5.0 readiness, and storage endurance rather than brand alone.

Data center market share by manufacturer in 2026 is shaped by hyperscale capex, not symmetric vendor splits. The global data center cooling market alone is set to reach USD 31.4 B in 2026, with Asia Pacific holding 36.9% revenue share in 2025.
Vestas led global wind turbine installations in 2024 with about 15.8 GW added, maintaining its top OEM position while Goldwind, Siemens Gamesa, GE Renewable Energy, and Mingyang filled the next tier. The on-land segment still dominates new builds, with the offshore and floating sub-segments driving

Utility-scale PV in 2026 is a price-driven market: Chinese tier-1 monocrystalline modules list at US$0.08–0.12/W FOB while CdTe landscape-integrated glass sells for US$113–143 per 8 m² panel. TOPCon, HJT, and BC cell architectures now compete on efficiency and degradation, with Sinovoltaics reportin

Chinese module makers (Jinko, JA Solar, Trina, Canadian Solar, LONGi) hold the dominant share of global solar PV module output, with the photovoltaic materials market sized at USD 76.4 billion in 2026 and projected to reach USD 104.3 billion by 2030 at a 7.9% CAGR. Crystalline silicon remains t
Global EV market value is projected to reach $951.90 billion by 2030 at a 13.70% CAGR (2024-2030), with battery-electric vehicles leading at a 42.51% application CAGR and APAC holding 37.36% of regional demand, while second-life EV battery capacity is forecast to satisfy short-term grid storage by 2
Global EV sales leadership is being reshaped by Chinese OEMs and the Asia-Pacific supply chain, with the EV motor market alone projected to grow from USD 24.9 billion in 2022 to USD 99.5 billion by 2032 at a 15.2% CAGR. Norway already registers EVs at 79% of new passenger car share, while BYD, Toyot

IDC projects global semiconductor revenue at $1.29 trillion in 2026 (+52.8% YoY), with data-center semis reaching $477.1 billion in 2026 and $843.2 billion by 2030, while WSTS forecasts 2026 sales above $1.5 trillion and PwC models an 8.6% CAGR through 2030.
Five NAND suppliers — Samsung, SK hynix, Micron, Kioxia, and Western Digital/SanDisk — together represent the global NAND flash industry, with 10–15% output cuts driving 5–10% contract price increases in Q3 2025 and shortages persisting into 2026.

Wind-energy blade composites are driving glass fiber demand in 2026, with China-hosted roving suppliers listing USD 0.67-3.33/kg and FRP pipe MOQs at 500 pieces. Glass fiber remains the lowest-cost reinforcement versus aramid, carbon, and UHMWPE in MarketsandMarkets' 2024-segmented taxonomy.

The global aluminum market is projected to grow from $189.59 billion in 2025 to $201.61 billion in 2026 at a 6.3% CAGR, with the primary aluminum ingot subsegment driving upstream capacity expansion through 2030.

Semiconductor industry trends 2026 pivot on talent localisation, AI-driven test capacity, and advanced packaging, with the global market expanding toward USD 1 trillion by 2030 as fabs scale.
Top OLED companies 2026: Samsung Display, LG Display, BOE, Visionox and Tianma hold the lion's share of small-, medium- and large-area OLED capacity, with Chinese panel makers closing the gap on Korean leaders through Gen 8.6 IT OLED lines.
Global epoxy resin market is projected to expand from $8.9 billion in 2020 to $16.6 billion by 2030 at 6.5% CAGR, with adjacent epoxy composites, adhesives, and corrosion-resistant resin sub-markets showing 5.0–7.3% CAGRs and 2026 valuation points clustered between $10–12 billion.

Power semiconductor supply in 2026 is split between Tier-1 Si/IGBT houses (Infineon, ST, ON, Mitsubishi, Fuji) and Tier-1/2 SiC specialists (Wolfspeed, onsemi, ROHM, ST, Infineon); selection hinges on voltage class, switching frequency, and qualification gate, not brand rank alone.
Chinese producers held 97% of global lithium-battery anode shipments in H1 2023, led by BTR at ~25% global share; ICC forecast 2.9 Mt global anode output and 3.5 Mt raw-material demand by 2025, with non-China capacity concentrated around 2025.
Global display panel market reached USD 122.743 billion in 2020 and is forecast to grow at 4.92% CAGR to USD 163.701 billion by 2026, with automotive HUD, transparent, flexible and 4K segments reshaping the value chain.
Air-source heat pumps from Guangdong OEMs such as New Energy Technology (R290 monoblock, CE/Keymark/MCS) lead 2026 villa and light-commercial sourcing, while European demand is anchored by the EHPA Heat Pump Forum & Awards on 2026-12-01 in Brussels and Bord Gáis service programmes.
Global pneumatic conveying systems market is on track to reach USD 48.36–48.37 billion by 2030, up from an estimated USD 32.49 billion in 2024, implying a ~6.8% CAGR through 2030; pneumatic actuators and cylinders track parallel expansion in industrial and process-control lines.
Centrifugal process-pump catalog pricing on Made-in-China spans US$ 5,000-500,000 per unit with 1-piece MOQ as of 2026-05-08, while US distributors such as Industrial Seal & Pump (est. 1973) and Springer Pumps continue to expand chemical, ceramics and wastewater coverage into 2026-07.</h2>

Cathode material market is forecast to reach USD 21.29 Bn by 2025 at a 10% CAGR per IndustryARC, with global cathode-material research reports pricing USD 3,315-5,850 as of May 2026. APAC dominates on consumer-electronics and EV-cell demand.

Global silicone market reaches USD 25.8B in 2026 with 5.4% CAGR through 2033, while 2,370+ China suppliers list 73,473 silicone rubber SKUs spanning HTV, LSR, and RTV grades. Spec-first buyers should anchor on Shore A, cure system, and FDA/IEC certifications before comparing FOB price bands.
Battery electrolyte market is sized at USD 15.06 BN in 2025 and forecast to reach USD 27.99 BN by 2030 at 13.2% CAGR, with lithium-ion, liquid electrolyte and EV end-use leading the build-out per MarketsandMarkets' June 2026 update.
Global packaging machinery demand is projected to reach $68.41B by 2030 at a 6.1% CAGR, with thermoforming equipment outpacing other types and e-commerce driving 11.32% YoY growth in related sectors.
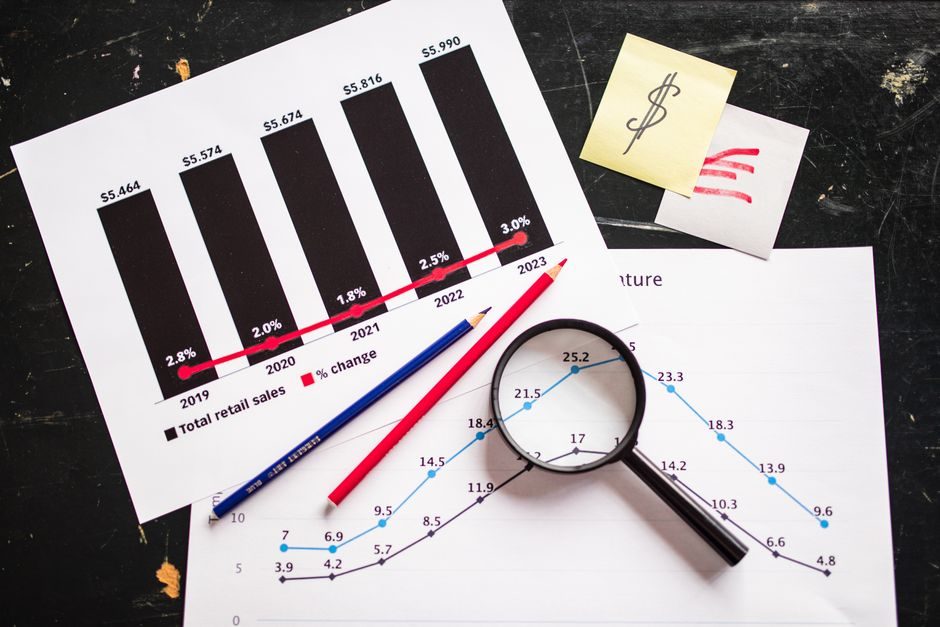
Global battery energy storage system (BESS) demand scales alongside lithium-ion and redox-flow deployments, with the 2026 outlook anchored in 4.2% CAGR growth in adjacent lead markets and shifting mobile-battery demand patterns shaping spec choices.
The 2026 global offshore wind build-out sits inside a wider wind-electricity TAM that is being re-cut for forecast to 2035, with sub-segment work covering cable spend, WTIV fleets and O&M services. U.S. DOE-funded acceleration projects now sit alongside the 2026 UK Offshore Wind
Aerospace in 2026 is shaped by AI-driven digital sustainment, SAF mandates, eVTOL certification cycles and LEO constellation buildouts; the sector is the rare industrial vertical growing on multiple fronts at once.

The global pneumatic actuator market for industrial valve automation is set to expand steadily through 2026, driven by process-control retrofits in oil & gas, chemical, and power plants. Scotch-yoke and rack-and-pinion designs dominate hazardous-area duty, with OEM portfolios spanning quarter-tu
The solid-state battery segment is forecast to compound at roughly 35-39% CAGR through the early 2030s, lifting the dedicated SSB market from about USD 1.66B in 2023 to USD 24.69B by 2032, while the broader battery technology market reaches USD 431.65B by 2030 at 11.4% CAGR.
Top 15 stainless-steel lunch-box makers (Thermos, Haers, Zojirushi, Tiger, Nanlong, Hydro Flask, Klean Kanteen, S'well, Corkcicle, Chilly's, Stelton, Emsa, Chinawaya, Fuguang, Shine Time, Sibao) are the visible brand layer above an OEM chain that splits into IF steel (Nippon Steel, POSCO, ArcelorMit
Edge computing gateways from Siemens, Rockwell, Schneider, ABB, Honeywell, AVEVA, and Robustel define the 2026 industrial tier, combining ARM/x86 hardware, container runtimes, and OT-protocol bridges for sub-second plant decisions.

Industrial edge computing gateways in 2026 are defined by ARM SoCs in the 1.6-1.7 GHz band, 512 MB to 2 GB LPDDR4, -40 to +80 °C fanless enclosures, and dual Gigabit Ethernet plus 4G LTE backhaul, with growing NPU-class edge AI SKUs from Robustel, PUSR, Moxa, OnLogic, and CTHINGS.CO shaping the spec

The 2026 global edge computing market sits between USD 25.63 billion and USD 709.91 billion depending on scope definition, with forecasts ranging from USD 267.42 billion to USD 6,092.42 billion by 2034-2035. The widest-consensus estimate projects USD 317.39 billion by 2031 at a 23.3% CAGR, anchored
Industrial Ethernet market reached USD 13.9 billion in 2026 and is forecast to grow to USD 21.13 billion by 2036 at a 4.3% CAGR, with Siemens leading at 14.0% share and PROFINET holding 27.0% of protocol deployments.
Industrial Ethernet market size forecasts for 2026 diverge sharply: Global Market Insights values 2026 at USD 10.5B (CAGR 7.9% to 2035), The Business Research Company puts it at USD 46.62B (CAGR 16.2%), and Market Research Future at USD 12.73B (CAGR 9.48%). The fourfold spread between

SCADA platform selection in 2026 is dominated by Ignition, Siemens WinCC, AVEVA System Platform, Schneider EcoStruxure, ABB System 800xA, GE iFIX, and Honeywell Experion, each with distinct licensing, protocol, and cloud architectures. The right choice depends on PLC ecosystem, tag count, and whethe
Rockwell, Siemens, ABB, Honeywell, Schneider Electric, Mitsubishi Electric, FANUC, Hexagon, and Omron anchor the 2026 industrial automation software market, with Rockwell's FactoryTalk, Siemens' NX/Teamcenter/Opcenter/MindSphere, and Schneider's EcoStruxure the most cited platforms. Edge-virtualized
Industrial automation software in 2026 is defined by IEC-driven interoperability standards, ISA/IEC 62443 cybersecurity mandates, and a shift toward software-defined, edge-native architectures. Sourcing decisions are now driven by license model and deployment mode rather than feature lists.

Global industrial automation software is sized at USD 40.83–48.5 billion in 2025, with the 2026 base year forecast between USD 43.87 billion and USD 53.9 billion depending on scope, growing at 6.6%–8.9% CAGR through 2030–2031. Asia Pacific held 38.22% share in 2025, and SCADA led the software mix at

Global SCADA market value for 2026 lands in a USD 12.07–15.61 billion band across 2026-dated reports, with forward CAGRs of 6.3%–10.4% to 2030. Forecasts diverge sharply by methodology: businessresearchinsights sizes 2026 at USD 14.84 B rising to USD 24.2 B by 2035, while The Business Research Compa

Keysight, Anritsu, Rohde & Schwarz, AMETEK, Fortive, Tektronix, Teledyne, Yokogawa, Bruker, and National Instruments lead the 2026 test and measurement equipment market, valued at $36.5B in 2026 with 5.5% CAGR to $45.19B by 2030 per The Business Research Company.

ISO 12179 was re-issued in 2026 under ISO/TC 213, with ISO/PAS 12868 withdrawn and the GPS surface-texture family actively being republished, signalling a measurable tightening of calibration baselines for stylus-based surface and CMM instruments across 2026. Buyers should anchor specifications to t
The global cutting tools market reached $87.57 B in 2025 and is projected at a 4.5% CAGR through 2035, led by Sandvik, Kennametal, Seco, Walter, and OSG across carbide, HSS, and indexable platforms.

Cutting-tool procurement in 2026 is being driven by material-specific grade selection (HSS, cemented carbide, ceramics, PCD, CBN), aerospace/medical qualification gates, and a projected 4.5% CAGR for the global metal cutting tools market. Buyers specifying by qualification, not unit price,
The global abrasives market is projected to grow from USD 65.38 billion in 2024 to USD 124.92 billion by 2035 at a 6.06% CAGR, with Saint-Gobain, 3M, Norton, Klingspor, CUMI, and Fujimi leading via proprietary grain technology and vertical integration. Selection depends on abrasive family, applicati

Abrasives demand in 2026 is anchored by automotive paint-prep and metal finishing, with global market value reaching USD 65.4 billion in 2024 and growing on EV body-line grinding. Grain sizing still follows ANSI B74.12-2012 macrogrit tables and ISO 3310-1 sieve calibration, while buyers must triangu

The global abrasives market is sized between USD 49.58–58.3 billion in 2025-2026 across eight forecasters, with 2026-2036 CAGRs clustering at 4.3-7.5% and a midpoint near 5.0%. Synthetic grains hold ~66% share, bonded wheels ~47-49%, and Asia-Pacific ~55% of revenue. Demand is anchored in EV drivetr

Sherwin-Williams, PPG, and AkzoNobel anchor the global industrial coatings top tier, with Asian Paints, Kansai, Jotun, Nippon Paint, RPM, Axalta, Hempel, and BASF Coatings rounding out the 2026 leaderboard. Selection hinges on resin chemistry, regional tech-center reach, and sector approvals (marine
Global industrial coatings demand is forecast to grow from USD 120.93 billion in 2026 to USD 148.60 billion by 2031 at a 4.21% CAGR, with Asia Pacific holding 60.3% of 2025 value and epoxy resin leading growth. Powder and waterborne systems are gaining share as VOC rules tighten, while general
Global industrial coatings demand is projected to climb from USD 112.04 billion in 2024 to USD 142.35 billion by 2030 at a 4.12% CAGR, with waterborne and powder chemistries absorbing most of the regulatory-driven shift away from solventborne systems.

The global specialty chemicals market is on track to reach $588.41 billion by 2025 at a 5.51% CAGR (2020-2025), with APAC commanding over 38% share and construction chemicals growing fastest at 8.89% CAGR. For 2026 sourcing, the top specialty chemical suppliers are tiered by region, product fam
Specialty chemicals demand is forecast to add USD 381.92 billion between 2025 and 2030 at a 6.3% CAGR, with APAC contributing USD 209.56 billion of that growth. Coatings, cosmetic actives, and biosurfactants sit on faster curves than bulk fine chemicals, reshaping sourcing decisions in 2026.

Top industrial catalyst suppliers in 2026 are split between diversified chemical majors (BASF, Clariant, Albemarle, Evonik) and specialized players (Topsoe, W.R. Grace, UOP/Honeywell, Sinopec catalysts, JGC C&C). For petroleum refining and petrochemical buyers the decision is support technology, lic

Activated carbon suppliers in 2026 split into four tiers: China-dominated honeycomb and coal-based producers (Shengjin, Xinhua, Litian Sheng), Indian powdered-carbon specialists (Capital Carbon, 40+ grades, sub-1% rejection), Western water-treatment majors (Kemira), and trading platforms listing 729

Coal-based and coconut-shell activated carbon dominate 2026 sourcing, with Chinese bulk prices ranging from US$400 to US$4,000 per ton across honeycomb, granular, and powder grades. Iodine value (IV) sits at 600–1100 mg/g for mainstream feedstock, while REACH compliance is now the gating filter for
The global activated carbon market is tracked at USD 3.2B in 2020 with a 6.3% CAGR through 2030, and air-purifier demand alone is sized at USD 19.5B in 2026 — the adsorption-supply chain sits between two large, structurally growing end markets.
DuPont, Toray, LG Chem, Hydranautics (Nitto), and SUEZ anchor the 2026 RO membrane supplier landscape, with thin-film composite (TFC) polyamide elements and Asia-Pacific demand driving a USD 5.0B market run-rate. Selection hinges on rejection rate, flux, feed TDS, and certification, not brand alone.
Global reverse osmosis membrane demand is on a USD 3.73B-to-5.11B trajectory (2024-2029, 6.5% CAGR), with thin-film composite (TFC) membranes holding structural dominance and Asia-Pacific driving incremental growth through 2026 desalination build-outs.

Global RO membrane market is projected to reach USD 5.0 billion by 2026 from USD 3.1 billion in 2021, a 10.0% CAGR per MarketsandMarkets. Adjacent membrane separation tech is sized at USD 34.7B in 2025, USD 37.9B in 2026, USD 84.5B by 2033 at 12.1% CAGR.

Decentralized membrane-based water treatment is the fastest-growing 2026 technology slice, with FRP RO housings quoted at US$26–750 and full reverse-osmosis systems at US$6,700–6,750 on Chinese export channels.

Pharmaceutical equipment demand tracks three live segments: contract manufacturing valued at USD 255.74 Bn in 2026, fill-finish at USD 30.37 Bn by 2031, and pharmaceutical inspection at USD 1.62 Bn by 2031, with 7.2-10.1% CAGRs.

The food processing equipment market is fragmented across equipment sub-segments, with dairy processing at USD 12.73 B and poultry processing at USD 4.97 B in 2026, while bakery tracks USD 14.8 B by 2026 at 5.1% CAGR. Growth is driven by automation, food safety regulation, and convenience-food deman
The 2026 global packaging machinery market is anchored by long-established European and US OEMs, Chinese mid-tier exporters shipping to 80+ countries, and UK turnkey specialists. FSC-certified packaging alone is forecast to grow from USD 89.74B (2025) to USD 173.58B by 2035 at 6.82% CAGR, resha

Global packaging machinery demand is sized at USD 46.4 Bn in 2022 with a 4.1% CAGR to USD 56.7 Bn by 2027, while adjacent 2026 segments (sachet USD 10.30 Bn, bioplastic USD 11.99 Bn, flexible USD 307.2 Bn) frame the equipment mix plants are specifying.

Henan-based cold-chain manufacturers lead 2026 vaccine-carrier and refrigerated-truck exports: Phefon offers 12L medical coolers at $20-24 with WHO PQS/CE/ISO 13485, while Weiba ships 12-60V mobile reefer boxes and tricycles from $705-4,830. Spec buyers should match certification depth to lane risk
The global industrial refrigeration market is projected to grow from USD 19.4 billion in 2021 to USD 25.1 billion by 2026 at a 5.3% CAGR, with CO2 cascade systems, screw compressors, and refrigerated warehouses leading each segment. Top-tier suppliers in 2026 are evaluated by refrigerant compliance,
Global industrial refrigeration demand is on track to reach USD 25.1 billion by 2026 at a 5.3% CAGR, with CO2 cascade systems and screw compressors leading the 2026 spec shift across cold-chain, food processing, and chemical plants.
Atlas Copco, Ingersoll Rand, Kaeser, CompAir, Sullair, and OTC Industrial (DIRECTAIR) sit at the top of the 2026 compressed air system OEM landscape, with China-based makers like Demargo and Sunwin dominating the sub-US$700 refrigerated and desiccant dryer tier. Selection hinges on duty cycle, ISO 8
The global compressed air filter and dryer market reached USD 6.13 billion in 2024 with a 6.7% CAGR forecast through 2034, while the broader air brake system market is on track from $4.81 billion (2018) to $6.6 billion (2026) at 4.4% CAGR. Energy-as-a-service models now advertise up to 50%

The global compressed air filter and dryer market reached USD 6.13 billion in 2024 and is forecast to hit USD 11.66 billion by 2034 at a 6.7% CAGR, anchoring the broader compressed air system outlook through 2026. Rotary screw, centrifugal, and reciprocating segments diverge sharply on lifecycl

The 2026 industrial filter supplier landscape splits into ten names that consistently win RFQs in water, chemical, and pharma: Parker Hannifin, Pall, Donaldson, Eaton, Camfil, Mann+Hummel, 3M, Filtration Group, LENGE, and Han Zhikang. Selection should be driven by spec, not brand list — flow rate, p

Industrial filter demand is rising on tighter emission rules and Southeast Asia manufacturing build-out, with the global market tracked at USD 2.7B in 2018 heading to USD 3.7B by 2023. 2026 sourcing prices span USD 145 per FFU HEPA unit to USD 250,000 for chemical filter presses. B

The hydraulic cylinder market is forecast to reach USD 19.50 billion by 2030 at a 5.1% CAGR (2024-2030), with tie-rod and mobile cylinders outpacing the average at 6.2% and 6.4% respectively, and Asia-Pacific holding the largest regional share.

Global hydraulic cylinder demand is projected to expand from $20.02 billion in 2025 to $26.06 billion by 2030 at a 5.4% CAGR, with Asia-Pacific leading both installed base and growth. Tariffs on steel tubes, rods and seals are reshaping sourcing toward localized supply and custom-engineered designs.
The industrial standard fastener market is valued at USD 75.32 billion in 2026, with Asia-Pacific holding over 45% share, led by Würth, PCC, ITW, Alcoa, and Araymond at the global tier.

Global industrial fastener demand is projected to track the broader industrial-equipment cycle in 2026, with end-market growth led by industrial valves at a 6.2% CAGR to USD 126.4 B by 2033, industrial robotics expanding at 12.6% CAGR toward USD 163 B by 2032, and industrial fabrics rising
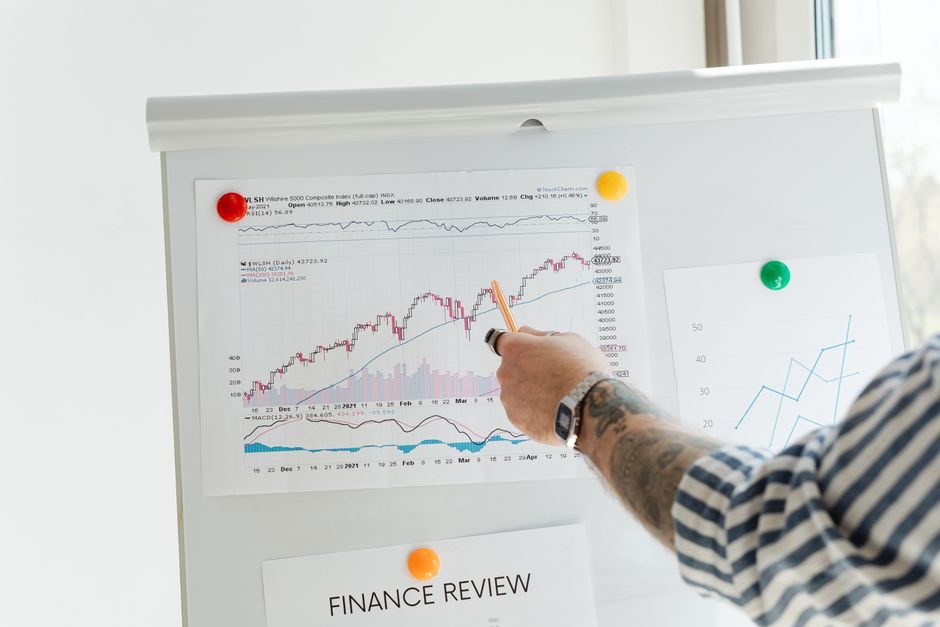
Global ferrochrome (FeCr) market is forecast to reach around USD 30.59 billion by 2030 at a 3.90% CAGR for 2024–2030, driven by stainless steel demand containing 10–20% chromium. High-carbon FeCr leads product mix, with pricing tracked daily on Chinese benchmarks like SCI99.

Elkem, Ferroglobe, Eurasian Resources Group, China Minmetals, and OM Holdings lead the 2026 global ferrosilicon supplier landscape, serving steel, foundry, and electrical-steel end-uses. Standard commercial grades FeSi 45/65/70/75% are produced in submerged-arc furnaces above 2,000°C, with the marke

Global ferrosilicon demand is anchored in 3.4% CAGR growth to USD 12.9B by 2028, with Asia-Pacific capacity — led by China's provincial output — driving both supply and export flows through 2026.

Global ferrosilicon market value is forecast to reach USD 15.4 billion by 2034 from USD 11.2 billion in 2026, with Asia-Pacific holding the dominant regional share. Stainless steel deoxidation and inoculant demand in cast iron remain the principal consumption pillars.
Global vanadium demand in 2026 is shaped by three structural pulls: HSLA steel-grade consumption tied to automotive production on a 6.92% CAGR path to $8,508.56 B by 2035, vanadium redox flow battery deployment for grid storage, and Chinese flake V2O5 operating-rate swings tracked by CBCIE

Freeport-McMoRan, China Molybdenum (CMOC), Grupo México, Antofagasta plc, and Jinduicheng Molybdenum are the dominant upstream molybdenum producers in 2026, supplying roughly three-quarters of mined supply. Specifying Mo-bearing stainless steel, Mo-oxide catalysts, or Mo-alloyed tool steels should s
Global molybdenum demand in 2026 is anchored by HSLA steel, stainless, nickel superalloys, and MoS2 dry-film lubricants, with end-product stratification across steel, chemicals, foundries, Mo-metals, and nickel alloys. MoS2 lubricant demand is forecast to reach $922.10M by 2030 at 4.4% CAGR, wi

Global molybdenum demand remains steel-anchored, with verified market reports projecting steady mid-single-digit CAGR through 2026 and downstream value spread across plates, alloys, and nanoparticles. Forecast data points to a USD 1.22B plates base, USD 0.9B Mo-Cu alloy base, and a 4% global CAGR ov
U.S. ITC ruled on 2025-08-06 that Chinese tungsten shot materially retards a U.S. industry, triggering CVD/AD duties; China retains over half of global tungsten ore reserves. Sourcing and tooling specs are shifting under that trade action.

Tungsten remains a critical refractory metal, with global supply concentrated in China and a 2026 market shaped by APT price floors, EU CRMA classification, and defence demand. Forecasts show 3-6% CAGR through 2030, with primary supply in tungsten trioxide (WO3) and ammonium paratungstate (APT) at 6

China-origin zinc ingot offers in mid-2026 sit inside a US$980–2,588/ton FOB band on Made-in-China.com, with smelting-side capacity being pruned and integrated OEM/ODM service layers now standard. This article maps spec bands, sourcing nodes, and the regulatory floor that defines procurement decisio

Global zinc ingot consumption is anchored in galvanizing, die-casting, and brass production, with coating-adjacent additives and zinc stearate chemistry pointing to stable 2026 demand. LME-grade SHG zinc (99.995% purity) remains the standard specification for industrial buyers.
Electrolytic copper cathode (Cu-CATH-1, 99.99% purity) anchors the 2026 supply map, with Made-in-China listings showing Wuxi traders pricing High Purity Electrolytic Copper at US$ 7.50–8.00/kg on 100 kg MOQ. Procurement should rank LME grade, Cu-CATH-1/ASTM B115 compliance, and port-of-origin before
Electrolytic Grade-A copper cathode (LME Cu-CATH-1) trades at US$8.00-12.00/kg MOQ on Made-in-China listings as of 26 May 2026, with a 10,000 MT Turkish CIF inquiry live on 9 June 2026. LME-grade 99.99% Cu remains the dominant spec for industrial buyers, with supply nodes concentrated in China and G

Global copper cathode demand tracks 2026 EV-battery and grid-cable buildouts, with electrolytic-grade 99.99% Cu wholesale offers on the China export channel at US$7.50-8.00/kg and adjacent cathode-materials market projected to reach $32.42Bn by 2030 at a 6.5% CAGR.

China-origin primary aluminum ingot traded in a US$2,375–3,500/ton band across late-June 2026 supplier listings, with ADC12 die-casting alloy and 6063 extrusion billet the two most actively quoted grades. LME primary aluminum, the benchmark for these contracts, closed Q2 2026 around the US$2,400–2,5

The 2026 global rebar supply chain is fragmented, with no single producer holding dominant share; Pakistan's Nomee Steel runs 250,000 t/yr ASTM A615/A706 capacity, Vietnam and Iran supply export-grade bar to ASTM/JIS buyers, and US/EU scrap feedstock flows through HMS 80:20 and shredde
Global steel rebar demand is tracking toward a $316.31 billion market by 2030 at a 4.40% CAGR, with Asia-Pacific still absorbing the majority share; 2026 is seeing HRC-base price volatility, fresh tariff walls, and tight galvanized supply reshape the bar-cost stack buyers face through year-end.
Global steel rebar market is forecast to reach $316.31Bn by 2030 at a 4.40% CAGR, with the APAC region holding a 66% share in 2018 driven by infrastructure and residential construction in China, India, and Southeast Asia.

Chinese mills dominate the 2026 galvanized sheet market, with DX51D+Z275 coils at US$840-880/t, EN 10346 / ASTM A653 dual-certified supply, and 0.12-6mm thickness range across 100-1800mm widths from Jiangsu Lianzhong, Shineyond, and Made-in-China.com listed exporters.

Galvanized steel sheet supply tightened in mid-2026 as DX51D Z275 hot-dipped coil moved into a US$500-900/ton band on 25-tonne MOQ. ASTM A653 G60/G90 zinc-coating grades and Z120/Z275 metric weights now drive most export quotations, with PPGI colour-coated coil layering on top.

Galvanized steel sheet is a zinc-coated flat-rolled carbon steel product governed by EN 10326 / EN 10346 and ASTM A653, with a 2026 global market valued at roughly USD 28–32 billion and 3–4% CAGR through 2030. Demand is led by construction (roofing, light steel keel), automotive structural panels, a

Outokumpu, Nippon Steel, Daido Steel, and Chinese mills (TSCO, Wuxi SDO, Hermes Steel) lead the 2026 stainless coil supplier map by capacity, grade range, and export reach. Asia dominates production and trade flows, with China's June 2026 exports hitting a year-to-date high.

Stainless steel coil supply in mid-2026 is anchored by Chinese mills and service centers, with 304 cold-rolled coil offered at US$1,077–1,220/ton and hot-rolled 201/304/316 coil at US$1,200–2,400/ton on 1–5 ton MOQs. Slit-coil processing, ASTM A240 grade coverage, and a May 2027 Guangzhou expo shape

Global stainless steel coil demand in 2026 is anchored by chemical tankers (44% product share, US$32.35 Bn sector size) and 300-series cold-rolled coils from China, with H2 price action driven by nickel alloy surcharges on 304/316L grades.

Fluoropolymer demand is tracking two parallel tracks: chemical and oilfield hose workhorses like Parker Polyflex 2440M (345-865 bar) and broader market growth projected from US$3.9B in 2023 to US$7.3B by 2034 at 5.2% CAGR. PTFE still leads by volume, but PVDF is the fastest-mover on Li-ion binders a
The global fluoropolymers market is estimated at roughly USD 11.2 Bn by 2027, with coating-additive fluoropolymers (PTFE, PVDF, FEP, PFA, ETFE, ECTFE) anchoring 5.2-5.4% CAGR forecasts through 2034 across chemicals, electronics, medical, and automotive processing applications.

Silicone rubber sourcing in mid-2026 is dominated by Guangdong-based custom manufacturers with US$10M+ export volume, MOQs as low as 100-500 pieces on consumer SKUs, and damping-grade silicone quoted at 100,000 pieces/day supply capability under TT/LC terms.

ABS remains a specialty volume polymer inside the broader plastic compounding market, which was valued at USD 448.3 million in 2022 and is projected to reach USD 781.3 million by 2032 at 5.7% CAGR (2023–2032). Demand is tied to automotive lightweighting, electrical/electronics, and durable consumer

Global polypropylene (PP) resin supply in 2026 is led by integrated petrochemical majors (ExxonMobil, LyondellBasell, Braskem, Sinopec, SABIC) with Asia-Pacific holding the dominant regional share. The PP market is forecast to reach $110.61Bn by 2030 at a 4.1% CAGR (2024-2030), with injection moldin

Polypropylene resin demand in 2026 is pivoting toward packaging and high-tenacity fiber, with Thailand's market projected at $2 billion by 2030 (CAGR 2%) and Chinese PP sheet offers at US$1.50–2.00/kg MOQ 1 kg to US$1,100–2,000/ton MOQ 1 ton across verified suppliers.

Global polypropylene resin demand is forecast to reach roughly USD 125-130 billion by 2026, expanding at a 5.2-5.5% CAGR, with injection molding and film/sheet applications leading volume growth at 5.28% and 5.48% CAGR respectively through 2027.

Polyethylene resin demand is tracking toward $157B by 2030 at 4.2% CAGR, with Asia-Pacific holding 38% share and bio-based / PCR grades reshaping sourcing. Dow's PCR LLDPE 95060 signals commercial-scale post-consumer recycled LLDPE, while PET resin scales from $47.99B (2024) to $64.01B (2029).
China's PVC industry entered 2026 with capacity growth slowing to roughly 800,000 t new supply through 2028 and 2027 likely seeing zero new additions, while exports hit 3.8 million tons in 2025, overtaking the US as the world's largest exporter at 16% of domestic output. Margins sit at a multi-year
Global PVC resin supply growth slows sharply, with only ~800 kt of new nameplate capacity scheduled for 2026-2028 and 2027 likely seeing zero net additions, while China overtook the US as the largest PVC exporter at 3.8 Mt in 2025, 16% of domestic output. Downstream, PVC stabilizers are tracked to $

Epoxy resin demand in 2026 splits across solvent-free food-grade floor coatings, FR4/glass-fiber electrical laminates, and DIY deep-cast craft resin. Solvent-free 100% solids epoxies with food approval dominate EU floor installs, while Chinese bulk supply holds bulk pricing at roughly US$2-12/kg wit
The para-aramid fibers market is projected to reach $6.6Bn by 2026 at a 7.2% CAGR, driven by automotive friction products, ballistic protection, and optical-fiber cable reinforcement, with Europe leading on PPE regulation.

Global aramid fiber demand is sized in the multi-billion-USD band with mid-single-digit CAGR through 2026, anchored by meta-aramid and para-aramid grades that overlap with high-performance engineering fiber categories like carbon fiber and glass fiber. Buyer-relevant specs cover tensile strength, mo

Top glass fiber companies in 2026 are concentrated in China, with CNBM, Jushi, Taishan Fiberglass and Owens Corning dominating the global supply chain across rovings, chopped strand mat, and coated fabrics, while recycling and lightweight PCR packaging shape the next procurement cycle.

Global glass fiber market will reach $47.9B in 2026 at 4.8% CAGR, with construction, transportation, and electrical-electronics driving demand; E-glass dominates, wind and EV composites shape the upside through 2030.

Toray (gold sponsor), Syensqo (silver), and Zibo Xinnuo are among the carbon fiber players confirmed in the public 2026 supply chain, with CompositesWorld's Carbon Fiber 2026 conference set for Huntsville, AL on November 10-12.
Global carbon fiber demand is on track from $5.52B in 2025 to $6.02B in 2026 (9.0% CAGR) and $8.57B by 2030, driven by wind, EV, and pressure-vessel pull; recycled carbon fiber (RCF) and PAN-based virgin fiber (VCF) are the two material tracks to watch.
China-origin magnesium ingot (Mg≥99.9%) is being quoted at roughly US$2,250-3,200/ton FOB on July 2026 wholesale channels, with Inner Mongolia and Shanxi smelters anchoring supply and 20-ton MOQs standard across 99.9% and 99.99% grades.

China holds the dominant position in titanium sponge production for 2026, with April export volumes (HS:81082021) leading global shipments. Key producers include state-owned Pangang Group, Baoti, Zunyi Titanium, and Yunnan Metallurgical, alongside Japan's Toho Titanium and OSAKA Titanium and Ru

Titanium sponge production capacity, monthly export flows, and domestic price benchmarks tracked through June 2026 show China holding the dominant supply position, with capacity utilization and provincial export data the two most concrete data signals for buyers.

Top phosphate rock suppliers in 2026 split between integrated Moroccan, Chinese, and Russian miners and a long tail of mid-grade Chinese grinders; sourcing is dictated by P2O5 grade, Cd/U limits, and SiO2 ratio, not by brand recognition.

South Africa, Gabon, and Australia sit at the top of the global manganese ore producer ranking by 2026 mine output, while Chinese processors and Brazilian miners (e.g. Svb Construtora, 42–52% Mn, 150,000 t/yr) anchor the supply side. Buyers should weight Mn grade (28–52%), Fe/SiO2 penalties, port in

South African manganese ore lumpy 28-30% trades around a 4-week stable band on Chinese spot markets, while electrolytic manganese flake 99.7% quotes at US$ 1350-2500/t FOB China (July 2026), with battery-grade EMD MnO2 carrying a US$ 2000-3000/t premium over steelmaking flake.
Manganese ore pricing and demand in 2026 is anchored by steelmaking, where high-grade (44%+) ores carry a structural premium over 30-35% Fe-Mn lumps, while battery-grade MnSO4 draws a smaller but fast-growing share of new project capital. Spec-driven buyers should expect continued price band volatil

Industrial-grade nickel sulfate traded at US$4.00-6.00/kg on Chinese B2B platforms in July 2026, with battery-grade supply anchored by type-2 ≥22% Ni, ≤100 ppb magnetic specs. Buyers should weight lithium and nickel as paired sourcing signals.

Global nickel sulfate demand remains tethered to battery-grade nickel supply, with China-origin Ni≥22%, Co≤0.4% material assessed on a delivered basis by S&P Global and quoted in RMB/tonne on CBCIE trade feeds as of 2026-07.

Global lithium hydroxide supply in 2026 is being reshaped by Chinese battery-grade capacity additions (single-train projects at 50 kt/yr), while battery-grade and technical-grade price tracks diverge on the LME and Chinese spot markets. Buyers should anchor specs on CAS 1310-65-2, monitor monthly Ch

Battery-grade lithium carbonate (Li2CO3 ≥99.5%) is sourced mainly from Chinese converters with CBCIE publishing daily ex-works quotes, while technical and pharma grades are supplied globally as CAS 554-13-2 solid at 98-99% purity for industrial and lab use.
Global lithium carbonate demand faces a structural inflection in 2026, with battery-grade Li2CO3 ≥99.5% trading near 163,200 RMB/ton in Jiangxi and 161,700 RMB/ton in Sichuan on 2026-06-08, against a broader lithium compounds market projected to reach USD 30.53 billion by 2030 at 8.30% CAGR.

China hosts ~950 graphite electrode manufacturers with 68,720 active SKUs and quoted ranges of US$1,300-2,400/tonne for RP-grade stock, while pricing scales 5-10× into isostatic EDM grades. Procurement decisions hinge on HP/UHP grade, needle-coke availability, and EAF vs submerged-arc duty.
UHP graphite electrodes for EAF steelmaking are the dominant 2026 product grade, with Chinese 500-700 mm UHP exports listed at US$1,999/ton (20 t MOQ) and competing offers spanning US$1,300-3,200/ton across RP/HP/SHP/UHP grades on the Made-in-China platform.

Global graphite electrode demand is anchored to EAF steelmaking, with the market projected to reach $13.88Bn by 2030 at a 3.80% CAGR (2024-2030); UHP grades lead, needle-coke raw material remains the supply bottleneck, and China-side export data tracks ongoing regional flows.

Polysilicon demand in 2026 is anchored by monocrystalline solar PV pull-through, with a FerroAlloyNet silicon-industry conference set for March 25-27, 2026 in Chongqing, China, and a successor Industrial Silicon Development Forum scheduled for August 5-7, 2026 in Lanzhou.

The global polysilicon market was valued at USD 5.49 billion in 2015 and is projected to grow at a 10.2% CAGR through 2025, driven by solar PV and semiconductor fabrication demand per Grand View Research. Siemens-process and fluidized bed reactor (FBR) routes dominate the manufacturing technology ba

Global laser technology market is projected to grow at an 8.60% CAGR through 2026-2035, led by IPG Photonics, Coherent, Corning, Jenoptik, 600 Group, and Lumibird across cutting, marking, cleaning, and additive manufacturing applications.

The global laser technology market grew from $16.02B in 2025 to $17.36B in 2026 (CAGR 8.4%) and is forecast to reach $23.74B by 2030, driven by semiconductor, optical-comm and industrial-processing demand. Buyers should track ultrafast/EUV specs and China sourcing.
The global laser technology market is set to grow from $16.02B in 2025 to $17.36B in 2026 (8.4% YoY) and $23.74B by 2030 at 8.1% CAGR, with Asia-Pacific the largest region and fiber, Nd, and YAG solid-state lasers leading the type mix.

The 2026 robotic welding market is concentrated among a handful of OEM groups, with Chinese integrators like Hefei Wanyi supplying ISO-certified articulated units from a 1-piece MOQ baseline, and a global supplier map split between Japanese, European, and Chinese manufacturers targeting automot
Chinese-made welding robots now list at US$3,500-20,000 per set on B2B platforms, with a 6-axis collaborative cobot-MIG arm undercutting traditional industrial units. The global robotic welding market is projected to reach US$10.78 billion by 2026 at an 8.7% CAGR.

Robotic welding market tracked at $5,450.5M (2018 base) with Allied Market Research projecting $10,784.4M by 2026 at an 8.7% CAGR, while broader industrial robotics is forecast to reach $163B by 2032 at 12.6% CAGR, making 2026 a transitional midpoint for arc-welding cell spec-out decisions.

China-hosted laser cutting machine makers dominate the 2026 supplier map, with fiber flat-bed and tube cutting systems from Penta Laser alongside Jiangsu and Shandong fabricators driving both heavy-industry and textile/foam niches at US$ 1,800-25,700/set FOB.

Mid-2026 laser cutting machine pricing spans US$2,313-55,000 across 1kW-40kW fiber and 30W-150W CO2 systems, with China-OEM supply dominating advertising, acrylic, and metal-fab segments. Fiber wattage escalation and dual-source CO2/fiber hybrid CNC platforms are the clearest spec movements on curre

Global laser cutting machine market stood at USD 4.12 billion in 2025, with a 5.99% CAGR forecast for 2026-2031 and solid-state sources as the fastest-growing segment. Fiber machines dominate Chinese export listings at USD 7,000-30,000 per unit, while the wider CNC metal-cutting peer set is projecte
The global CNC controller market was sized at USD 3.4 billion in the 2021 baseline, growing at a 9.9% CAGR toward 2026, with APAC holding roughly 42% share. The major vendor categories are Japan-headquartered CNC specialists (Fanuc, Mitsubishi, Yaskawa), German motion-control platforms (Siemens, Bos

The CNC controller market is on track from USD 3.4 B in 2021 to USD 3.4 B by 2026 with hardware plus software stacks, while the parent CNC machine market grows 9.9% CAGR to USD 187.54 B by 2033. Embedded PC-based units using Intel i7 CPUs and Linux/Windows CE dominate new product listings across lat
The global CNC controller market is forecast to grow from USD 2.8 billion in 2021 to USD 3.4 billion by 2026 at a 3.6% CAGR, with APAC holding the largest share, while a separate forecast pegs the broader CNC machine market at USD 96.85 billion in 2026 rising to USD 187.54 billion by 2033 at 9.9% CA
Industrial gearbox sourcing in 2026 splits between established gearbox OEMs with multi-decade installed bases and regional specialists focused on planetary, helical, and worm configurations. Specifiers should weight torque density, gear quality grade per ISO 1328, AGMA 2001 duty classification, and

Industrial gearbox demand in mid-2026 is bifurcating: high-ratio planetary and cycloidal units dominate chemical, food and packaging lines, while worm and helical gear reducers handle general-purpose heavy industry. The 24-company DirectIndustry chemical-gearbox index lists 47 active SKUs, with plan
Miniature ball screws with 8-12 mm diameters and 2.1-8.9 kN load ratings anchor a 2026 market where Chinese suppliers, US rebuilders, and Indian distributors compete on precision grade and lead time.

The global ball screw market is projected to grow from USD 2.32 billion in 2025 to USD 3.26 billion by 2032 at a CAGR of 4.9%, driven by CNC machine tool demand, semiconductor lithography positioning stages, and humanoid robot actuator retrofits through 2026.
Linear guide rail demand is expanding with the global linear motion system market projected to grow from USD 11.74 Bn in 2026 to USD 19.86 Bn by 2033 at a 7.8% CAGR, driven by CNC and automation. HGR/HGH/MGN format families in GCr15 bearing steel dominate new 2026 sourcing, with roller guides re-ent
Top RV reducer companies 2026 are concentrated in Nabtesco (Japan), Spinea (Slovakia/Japan origin), Sumitomo Heavy / Drive Systems (Japan) and a Chinese cluster led by Greenharm, Leaderdrive, Shuanghuan and Qinchuan. The headline trade-off is Japanese accuracy / Torsen-grade backlash below 1 arc-min
RV reducer demand in 2026 is anchored by humanoid-robot joint actuators and heavy-payload industrial robotics, with Chinese OEM pricing clusters of US$50–US$500 per unit and an AGMA-compliant bevel/helical peer set filling adjacent frames.
Harmonic reducer demand in 2026 is anchored by humanoid robotics, semiconductor motion stages, and surgical robots, with strain-wave gear ratios from 30:1 to 160:1 and torsional stiffness above 25 N·m/arc-min as the dominant spec gate. Chinese bearing suppliers and HarmonicDrive CSF-8-30-1U-class un
The global harmonic reducer market is expanding alongside robotics, surgical robotics, and semiconductor wafer-handling automation, with USD-denominated forecasts typically projecting 7-9% CAGR through 2030-2033. Selection hinges on reduction ratio (50:1 to 160:1), backlash grade (under 1 arc-min to

The 2026 servo drive market is led by a tier of established motion-control vendors — Yaskawa, Mitsubishi, Fanuc, Siemens, Bosch Rexroth, ABB, Delta, Kollmorgen, Schneider, and Rockwell — competing on loop bandwidth, EtherCAT/EtherNet/IP support, and integrated safety. Selection should be driven by v

Global servo drive revenue is projected to exceed USD 9 billion by 2026, per a Global Market Insights forecast, while adjacent variable-frequency drive demand is set to grow from USD 24.7 billion in 2025 to USD 32.0 billion by 2030 at a 5.3% CAGR, with servo drives treated as a high-precision VFD su
The warehouse robotics market reached $6.21B in 2025, is set to grow to $7.08B in 2026 (14.1% CAGR), and is projected to hit $11.91B by 2030. North America led in 2025; Asia-Pacific is the fastest-growing region, driven by e-commerce, labor shortages, and AI vision advances.

Warehouse robotics demand is being pulled by e-commerce throughput, retail in-house fulfilment builds, and persistent labor shortages. The segment was valued at USD 4.31B in 2022 and is projected to reach USD 17.29B by 2030, with Asia Pacific leading regional revenue in 2022.

Warehouse robotics demand is on track to nearly double from $6.21B in 2025 to $11.91B by 2030 at a 13.9% CAGR, with 2026 alone expanding 14.1% to $7.08B, driven by e-commerce, labor shortages, and AI vision integration.
The global collaborative robot market reached $1.4B in 2022 and is projected to hit $27.4B by 2032 at a 36.3% CAGR; Universal Robots, KUKA, and Techman remain the dominant 2026 vendors, with Chinese OEMs JAKA and UFACTORY reshaping the mid-payload segment.

Global collaborative robot (cobot) revenue is projected to climb from $2.9B in 2025 to $4.0B in 2026 and $17.2B by 2033, a 23.1% CAGR. Power-and-force-limiting designs, ≤5 kg and 6–10 kg payload tiers, plus automotive and electronics demand, are the four concrete drivers of the 2026 deployment wave.
Global collaborative robot (cobot) market is projected to grow from USD 4.0B in 2026 to USD 17.2B by 2033 at 23.1% CAGR, with parallel trackers forecasting 25.60% CAGR to USD 7.67B by 2030 and up to 36.3% CAGR to USD 27.4B by 2032. Selection is driven by payload, application, and integration risk, n
Humanoid robot commercialization accelerated through 2025-2026, with at least 8 vendor platforms (1X NEO Gamma, Unitree G1/H1/H2, Tesla Optimus, Figure, Agility Digit, Boston Dynamics Atlas, Apptronik) active in pilots. Buyer focus shifted from demos to deployment proof, tendon-driven quiet drives (

The global humanoid robot market is forecast to reach $15.20 billion by 2030 at a 50.2% CAGR for 2025-2031, with APAC leading on the back of Chinese and Japanese manufacturing. Biped motion and healthcare plus education applications remain the dominant segments shaping spec roadmaps.

Top LiDAR sensor companies in 2026 split between automotive-grade units (Luminar, Hesai, RoboSense, Valeo, Innoviz) and industrial/mapping suppliers (Velodyne, Ouster, RIEGL, SICK), with selection driven by range, wavelength, and point rate.
Global LiDAR market reaches USD 3.4B in 2026 on the way to a projected USD 9.0B by 2033 at 14.8% CAGR, with Asia-Pacific holding 38.8% of 2025 revenue and automotive autonomous-driving programs as the lead demand driver.
The global LiDAR market was valued at USD 3.0 billion in 2025, projected to reach USD 3.4 billion in 2026 and USD 9.0 billion by 2033 at 14.8% CAGR, with automotive LiDAR as the fastest-growing slice at 31.7% CAGR.
The global machine vision system market is forecast to grow from $49.7B in 2023 to $159.2B by 2032 at a 13.9% CAGR, with smart cameras and 3D vision segments expanding on Industry 4.0 and AI defect-detection demand through 2026.
Precision air conditioning (PAC) and CRAC units for data centers, cleanrooms, and telecom rooms are dominated by Vertiv, Schneider Electric (Uniflair), Stulz, Rittal, and Huawei in 2026, with Asia-based assembly capacity now exceeding 60% of global unit output. Specifications converge on ±0.1 °C con
Precision air conditioning (PAC) for data centers and cleanrooms grew as a structural segment through 2025-2026, with manufacturers such as Vertiv, Stulz, Envicool and Guangdong Shenling expanding close-control units, EC-fan retrofits and liquid-assisted designs to handle AI-rack heat loads. The art
Global precision air conditioning market is on a 2026 growth path alongside a USD 26.3 B data-center cooling base, with hyperscale builds and inverter CRAC units driving double-digit unit and revenue expansion through 2030.
The 2026 industrial UPS market is led by Vertiv, Schneider Electric (APC/Galaxy), Eaton, ABB, and Delta, each differentiating on topology, modularity, and lithium-ion integration. Specs under IEC 62040-3 separate true online double-conversion (VFI) from line-interactive and standby architectures, wh
Industrial UPS systems are heading to roughly USD 8.9 B by 2030 at a 9.8% CAGR, with modular online/double-conversion designs over 100 kVA leading data-center, BFSI, and healthcare builds through 2026. Procurement should weight lithium-ion retrofit economics and rack density over legacy VRLA ba

Immersion cooling for data centers is scaling on the back of HPC and AI rack densities, with the addressable market projected at USD 2.61 B by 2032 on a 24.2% CAGR (2025-2032). Single-phase systems lead on deployment ease, while dielectric fluid choice and custom tank engineering are now the pr

Immersion cooling is forecast to reach USD 2.61 billion by 2032 at a 24.2% CAGR, with the wider data center cooling market pegged at USD 31.4 billion in 2026 against USD 26.3 billion in 2025. The niche still trails district cooling (USD 29.1 billion 2025 base) but outpaces the broader
Lenovo Neptune, CoolIT Systems, and Koolance are the most consequential data-center liquid-cooling vendors for 2026 specifiers, with Neptune 6th Gen claiming up to 100% heat removal and Koolance shipping a 15 kW ambient CDU on 100-240 V at 700 W draw. Buyer decision turns on direct-to-chip vs rear-d

Liquid cooling in 2026 has crossed the 20 kW-per-rack air-cooling ceiling as 6th-gen Lenovo Neptune, 215 kWh LFP C&I ESS racks, and DLC retrofits spread across AI/HPC and storage sites, with reported efficiency gains of 10-27% over chilled-air baselines.

Liquid cooling systems market is projected at US$9.48B in 2025, growing to US$25.5B by 2034 at a 13.16% CAGR through 2026-2034, with data centers as the dominant end-use segment. Adjacent data center cooling market is set to expand from US$31.4B in 2026 to US$128.3B by 2033 at 22.3% CAGR.

Global data center cooling spend scales from USD 31.4 B in 2026 to USD 128.3 B by 2033 at 22.3% CAGR, with Asia Pacific holding 36.9% 2025 revenue share. Operators cluster into cloud, retail colocation, and wholesale groups, and the top 10 alone run 1,250+ facilities worldwide.
Global data center cooling spend is set to grow from $26.3B in 2025 to $31.4B in 2026 and $128.3B by 2033 at a 22.3% CAGR, with Asia Pacific holding 36.9% of 2025 revenue. Liquid and WUE-driven designs dominate AI/hyperscale procurement.
AI accelerator vendors in mid-2026 split into three concrete cohorts: Chinese edge-AI stick/system integrators shipping USB3.0 + TensorFlow/ONNX/Darknet modules, US platform players such as Datadog and Skillsoft that embed AI into SaaS rather than sell silicon, and spatial-intelligence specialists l

Global AI server shipments are forecast at roughly 3.7 million units in 2026, up 51.3% year on year, with double-digit growth sustained through 2028. Enterprise AI spend is projected to reach $53.06 billion by 2026 at a 35.4% CAGR from 2019.

NAND flash market revenue hit a record $46B in Q1 2026 on AI infrastructure demand, up 3.5x year-on-year and nearly doubling sequentially per Counterpoint Research. The 3D NAND layer race continues, with YMTC's 128-layer QLC/TLC now sampling to controller vendors.
Global NAND Flash demand is projected to grow 18% in both 2026 and 2027, while wafer shipments contract 5% in 2026 and rise only 3% in 2027, leaving the market supply-constrained through 2028-2029 per Mizuho and Bank of America research notes published June 9, 2026.

Samsung, SK hynix, and Micron remain the three dominant DRAM suppliers in 2026, with combined wafer-output capacity reaching 18 million wafers yet still trailing AI-driven demand. Samsung's Pyeongtaek, SK hynix's Cheongju M15X, and Micron's planned 2027–2028 expansions define the supply roadmap.

DDR5 has displaced DDR4 as the JEDEC-standard default for new industrial and embedded DRAM module designs as of mid-2026, with DDR4 LRDIMM/UDIMM supply contracted and LPDDR5x pushing into edge-AI modules. Industrial buyers should pin VDIMM to 1.1 V, PMIC presence, and on-module temperature sensors b

HBM (High Bandwidth Memory) is a JEDEC-standardised stacked DRAM used as the primary accelerator-memory tier for AI GPUs. The 2026 supplier set is led by SK hynix, Samsung, and Micron, with SK hynix holding the dominant share on HBM3E and pre-qualifying HBM4.

HBM (High Bandwidth Memory) stacks DRAM dies with TSV interconnects on a wide-interface architecture; per JEDEC JESD238B.01, HBM3 uses 64-bit independent channels. AI accelerators remain the primary demand driver through mid-2026, with mobile HBM on the roadmap for 2026+ mass production.

The HBM memory market in 2026 sits at the centre of the AI accelerator build-out, with stacked-DRAM demand driven by NVIDIA, AMD, and hyperscaler GPU ramps. Forecasts point toward triple-digit-percent YoY shipment growth through 2026, while supply stays constrained by advanced packaging.

Advanced packaging in 2026 spans two distinct lanes: active/intelligent food-and-pharma packaging led by oxygen scavengers, and semiconductor advanced packaging driven by wafer-level bumping and equipment partnerships. Oxygen scavenger demand is outgrowing other active formats, while the global

Advanced packaging in 2026 splits into two tracks: semiconductor glass-core substrates (TGV) scaling to a projected 50%+ penetration within 5 years and a global IC-substrate market of USD 31.54 Bn by 2029, while bioplastic consumer packaging grows from USD 11.99 Bn in 2026 to USD 27.69 Bn by 2033 at

Global advanced packaging technologies are forecast to expand at a 7.5% CAGR through the 2026 horizon, with bioplastic packaging climbing from USD 11.99 Bn in 2026 to USD 27.69 Bn by 2033 at 12.7% CAGR, and packaging printing rising from USD 452.5 Bn in 2026 to USD 690.6 Bn by 2035 at 4.8% CAGR

Chip packaging demand in 2026 centers on advanced 2.5D/3D integration, chiplet partitioning, and co-packaged optics, with WEPACK 2026 in Shenzhen reporting 120,000 sqm of exhibition space and India presses expanding rPET and laminated paper-foil formats as adjacent supply signals.

Global semiconductor packaging capacity is scaling into 2026 alongside a USD 154.93 billion AI chips opportunity at 24.3% CAGR (2025–2030), while adjacent packaging segments diverge sharply: bioplastic packaging at 12.7% CAGR and medical device packaging at 6.4% CAGR through 2033.

Top wafer fab equipment vendors in 2026 cluster into four groups: lithography (ASML), deposition/etch (Applied Materials, Lam Research, TEL), process control (KLA-Tencor), and supporting tracks (Hitachi Kokusai, Dainippon Screen, Nikon). China's domestic leaders Naura, AMEC, and E-Town Semiconductor

Global wafer fab equipment (WFE) spending is on track to expand by roughly USD 34.7 billion between 2024 and 2029 at a 6.2% CAGR, while 2026 product splits break the market into 7 nm-and-below vs 14/22/32 nm vs 45/65 nm-and-above nodes across foundry, memory, and IDM buyers.

Global lithography equipment market stood at US$ 22.1 Bn in 2022, projected to reach US$ 41.3 Bn by 2031 at a 7.2% CAGR, with advanced packaging, MEMS, and LED applications driving growth through projection, mask aligner, and laser direct imaging technologies.

The 2026 smart meter market is split between telecom-grade AMI vendors (Huawei, Landis+Gyr, Itron, ZTE, Ningbo Sanxing) and metering stack providers (Sagemcom, EDMI, Hexing, Holley, Wasion). Selection hinges on protocol (DLMS/COSEM, IDIS, G3-PLC, RF mesh), IEC 62053-22 accuracy class, and dual-utili
Smart meter shipments in 2026 are pivoting toward AMI 2.0 modules with multi-utility metering, RF-mesh + NB-IoT dual stacks, and edge TOU engines, with China-origin supply scaling to sub-US$3 residential units and US$500-700 industrial power meters bracketing the spread.

ABB and iocharger define the 2026 DC fast charger market split: ABB delivers grid-tied 50-350 kW highway units with OCPP back-end integration, while iocharger's Xiamen-built portfolio spans 30 kW wallboxes up to a 1600 kW megawatt system for heavy fleets. Selection hinges on power class, O

DC fast charger market 2026 splits into two architectures: modular 20-180 kW multi-vehicle units (ABB Terra) and all-in-one 50-200 kW autonomous chargers (KEBA DCA10). Modular designs now dominate fleet and highway sites, with high-voltage battery compatibility becoming the default specification.

The DC fast charger segment is on track to expand from a low-tens-of-billions USD base in 2026 toward a triple-digit-billion USD outcome by 2033, driven by 350 kW+ high-power units, MCS megawatt systems, and OCPP 2.0.1 networking across highway and fleet sites.

Global EV charging station market projected to grow from USD 38.9 BN in 2026 to USD 120.85 BN by 2033 at a 17.7% CAGR, with DC fast charging, V2G, and wireless inductive segments leading expansion. Paren released its Q2 2026 U.S./Canada State of the Industry reports on 2026-07-15, giving buyers week

Global EV charging station market is projected to grow from USD 38.55 billion in 2026 to USD 120.85 billion by 2033 at a 17.7% CAGR. Fixed and Level 3 segments lead; Asia Pacific remains the largest region, with China and the US driving ultra-fast DC and MCS deployment.

The automotive e-axle market reached USD 11.93B in 2022 and is forecast to grow at a 37.7% CAGR through 2030, with oil-cooled motor systems and integrated 3-in-1 architectures reshaping spec decisions for EV powertrain buyers.

Global automotive e-axle market was valued at USD 11.93 billion in 2022 and is forecast to expand at a 37.7% CAGR through 2030, driven by BEV sales and integrated 3-in-1 drive unit adoption across front and rear axle applications.

The global EV traction motor market grew from $17.77B in 2025 to $24.83B in 2026 at a 39.7% CAGR, with Asia-Pacific leading and North America the fastest-growing region. Bosch, ABB, Nidec, BorgWarner and Dana TM4 anchor most 2026 model-year programs.

EV traction motor development through July 2026 is dominated by rare-earth-free and dual-stator architectures, with Nidec's PSA joint venture scaling 800 V oil-cooled drives and IEA tracking 14% global EV market share. Spec engineers should anchor on FOC control, 160-250 kW peak power, and 20,000 rp

The global EV traction motor market sits inside a USD 39.38 billion (2025) automotive motor base projected to grow at 6.22% CAGR through 2031, with permanent-magnet designs still holding above 75% of the car market as rare-earth supply risk and axial-flux/in-wheel alternatives reshape sourcing
Offshore wind foundation orders are tracking a clear 2026 pivot toward larger monopiles and serial-produced floating substructures, with North Sea capacity build-outs and French floating arrays cited as the demand pullers. Monopile, jacket and floating-semi platforms now dominate the spec envelope,

The global offshore wind energy market is projected to expand from USD 39.89 billion in 2023 to USD 110.62 billion by 2032, a 12% CAGR, with foundation engineering demand driven by larger turbines, deeper water, and serial monopile fabrication.
The wind turbine gearbox market in 2026 is anchored by four European drivetrain specialists—ZF, Flender (Siemens Gamesa), Winergy, and Eickhoff—alongside China-based NGC, DHI·DCW, CRRC, and CSSC Haizhuang. Selection hinges on planetary stage count, bearing series, and IEC 61400-4 design-load complia

Wind turbine gearbox demand in 2026 is shifting toward larger rotor drivetrains, condition-monitoring retrofits, and deserization kits, with the global market forecast to grow through 2027. Buyers are grading suppliers on planetary-stage load ratings, bearing temperature telemetry, and gearbox sand-

The global wind turbine gearbox market is forecast to expand through 2027, with growth anchored to onshore and offshore wind build-out, while higher failure rates and replacement-cycle cost keep the aftermarket segment in play. Europe leads installed manufacturer base; Asia-Pacific is the faste

Wind turbine blade development in 2026 centers on three measurable shifts: ACT Blade's textile-membrane ACT100 retrofit secured DEWI-OCC type conformity on 6 July 2026 for the Senvion MM92, delivering 32% weight reduction and 7% LCOE cut versus baseline; Europe's installed pre-2022 blade stock is pr
Grid-scale battery market is forecast to reach $24.5Bn by 2030 at a 22.6% CAGR, with 42 GW added globally in 2023, driven by lithium-ion deployments paired with 500–2500 kW PCS inverters for peak, frequency and black-start duties.

Global energy storage systems are forecast to expand from US$40.53Bn in 2020 to US$73.8Bn by 2031 at 5.6% CAGR, with thermal storage scaling from $25.6Bn in 2023 toward $56.4Bn by 2033 at 8.4% CAGR per 2026-06 tracking.

TOPCon n-type monocrystalline cell output is scaling inside a USD 268.93 B solar-energy market in 2026, while module ASPs at USD 0.082/Wp FOB China (July 2025) and a Feb-2025 First Solar patent suit against Jinko set the price/legality rails for every 2026 procurement decision.
Global steel casting demand is forecast to add USD 9.87 B between 2025 and 2030 at a 5.2% CAGR, with APAC capturing 55.4% of growth and automotive/transportation leading at USD 13.35 B in 2024, per Technavio.

Solar glass demand in 2026 is being driven by a bifurcated supply chain: project-grade float/patterned glass for utility PV, plus specialized low-iron AR-coated cover glass for rooftop and BIPV modules. Top sourcing hubs remain China for tempered, low-iron patterned cover glass (2.0–4.0 mm), with th
Multicrystalline cell FOB on Made-in-China sits at US$0.16–0.25/W with 25-year warranty, mono PERC mobile panels list US$116–130 per 100W piece (2026-06), and the Solar Energy Market Report 2026 values the segment at US$4,490 across 150 pages.
Global solar energy market reached USD 217.51 billion in 2025 and is projected to hit USD 606.18 billion by 2030 at 22.5% CAGR, with solar PV installed base climbing from 2.34 TW in 2025 to 7.23 TW by 2031.
Leading solar inverter manufacturers in 2026 are evaluated across power range, topology, IP rating, efficiency and supply scale. Key procurement nodes include Sungrow, Huawei, Growatt, SMA, Fronius, Solis, and MPP Solar.
Smart solar inverters with grid-support, monitoring and ride-through functions are the 2026 specification pivot, anchored by IEEE 1547-2018 in the US, a 13.3% CAGR global microinverter market (US$311.9M in 2023) and a directory of 5,683 inverter series catalogued by ENF Solar.

Global solar inverter demand is set to track 2.34 TW of cumulative PV installed base in 2025 rising to 7.23 TW by 2031 (19.92% CAGR 2026-2031), with micro-inverters and string inverters split across a $217.51B 2025 solar energy market growing 23.6% YoY into 2026.
Alkaline, PEM and SOEC electrolyzer manufacturing capacity in 2026 is concentrated at fewer than 15 OEMs above 100 MW/yr nameplate, with alkaline still dominating shipped volume while PEM scales for renewables-coupled builds.

Global electrolyzer demand is on a steep 80.8% CAGR path from USD 5.88B in 2025 toward USD 2,196.4B by 2035, with PEM and alkaline stacks dominating and Asia-Pacific as the fastest-growing region.

The global electrolyzer market is on a steep growth curve, projected to reach USD 14.48 billion by 2031 at a 38.2% CAGR, with PEM, alkaline, SOEC, and AEM technologies split across sub-500 kW, 500-2,000 kW, and above-2,000 kW power classes driving hydrogen production, mobility, and grid injection de

Green-hydrogen project spending in 2026 is dominated by a small set of utility-scale developers — Air Products/NEOM, ACME (Duqm), SARCO/Ally, and Air Liquide/Siemens Energy — backed by electrolysis contracts worth $1.67 GW of wind generation and a global electrolyzer pipeline now running into tens o
Global green hydrogen market projected to expand from $2.79B in 2025 to $74.81B by 2032 at 60.0% CAGR; alkaline electrolysis led 2024 with 61.2% value share, while PEM and offshore-wind projects gain ground in 2026 build-outs.

Global green hydrogen market reached $2.5B in 2022 with Allied Market Research projecting $143.8B by 2032 at 50.3% CAGR; production is dominated by PEM and alkaline electrolyzers fed by wind, solar, and hydro power.

PEMFC dominates 2026 fuel cell stack demand at 66.4% BoP share per MarketsandMarkets, with Toyota, Hyundai, Ballard, Plug Power and Cummins anchoring global supply across transportation and stationary segments.

Global fuel cell stack demand tracks a 2026 USD 7.1B market expanding to USD 18.2B by 2036, with PEMFC leading transport and SOFC stationary at 15.7% CAGR through 2033. Stack sourcing decisions now hinge on cell count, BoP accessories and BoM-tier cost gates.

Global fuel cell market is sized at USD 7.1 billion in 2026 and forecast to reach USD 18.2 billion by 2036 at a 9.8% CAGR, with PEMFC holding 52% share and transportation 43% of demand.

Automotive BMS market projected to grow from USD 6,511.6M (2025) to USD 33,793.1M (2035) at 17.9% CAGR; Infineon's HV BMS supports up to 1200 V / 24 channels with ISO 26262 ASIL-D compliance, anchoring the 2026 supplier landscape.

The global battery management system (BMS) market reached $7.5 billion in 2022 and is projected to reach $41 billion by 2032 at a 19.1% CAGR, with Asia-Pacific holding over 45.2% share and the U.S. forecast to grow at 17.9% CAGR through 2032.
Polyolefin separators from Asahi KASEI (Hipore), SK IE Technology, Toray (Setela), Senior, W-Scope and Sinoma Science & Technology still set the 2026 supply map; AGM and PE sleeve suppliers like Heilongjiang JinHan Technology address the flooded lead-acid side, while ceramic-coated grades handle hig

Battery separator market tracker shows 83 syndicated reports listed on Research and Markets as of June 14, 2026, with active 2026 datasets running 181–369 pages and base prices starting below USD 5,000 per license. Across adjacent battery-stack segments, marine batteries are projected at USD 2.

Anode material demand in 2026 is anchored by graphite-dominated LIB cell output with silicon-additive growth, while market sizing remains thinly evidenced; the lithium-ion cathode track reached $21.29Bn by 2025 at a 10% CAGR per IndustryARC, providing a comparable adjacent data point.

Top-tier lithium-ion cathode material suppliers in 2026 cluster in China (LFP/NCM) and Japan/Korea (high-nickel NCA/NCM811), with the broader market forecast to reach $21.29Bn by 2025 at a 10% CAGR, APAC dominant.

33,995 Li-ion and LiFePO4 cell listings from 1,062 China-based suppliers dominate 2026 OEM sourcing, with prismatic LFP at US$7.8-69/piece across 27-340 Ah capacities and 18650 Li-ion cells at US$1.55-2.05.

China primary cell and battery exports hit 193.07M USD in May 2026, up 15.2% MoM from 167.58M USD in April, against a 397-month historical average of 133.98M USD; the global battery technology market is forecast to reach 431.65B USD by 2030 at 11.4% CAGR per MarketsandMarkets.

Global secondary battery demand in 2026 is led by Li-ion across automotive and industrial end-uses, with the marine sub-segment moving from USD 2.10 B in 2026 toward USD 6.11 B by 2034 and redox flow units gaining stationary-storage share.

Solid-state battery developers are moving from laboratory cells to MWh-scale roll-to-roll pilot lines in 2026, with sulfide, polymer and oxide electrolyte chemistries diverging on cost and manufacturability. IDTechEx projects a US$10 billion SSB market by 2036, while BYD's December 2025 disclosure s
Sodium-ion battery shipments in 2026 are led by Chinese cell-and-system suppliers — HiNa Battery, CATL, BYD, Faradion/Reliance, EVE Energy and EAST Group — with 12V SLI, UPS cabinet and energy-storage form factors already in volume. Project pipelines from Shanxi Xinyang (10,000 t/yr) anchor capacity

Sodium-ion battery industry in 2026 is moving from pilot to first wave of grid-scale and UPS deployment, anchored by China Datang's 100 MW/200 MWh Qianjiang storage project and by commercial NaFePO4 UPS modules offering 3000 cycles at 80% DoD and 50 Ah/53 V packs.
Sodium-ion battery shipments are entering a utility-and-start-stop inflection point in 2026, with EAST Group shipping PACK-level fire-suppressed cabinets and NaQTP H5/H6/H7/H9 12V start-stop cells sized 660–1000 Ah for grid and vehicle duty.
Panasonic, Samsung, LG, Sony/Murata, BAK, Lishen and CATL-aligned pack integrators dominate the 2026 lithium pack market, with 18650 cell prices at $0.43-0.86/pc and 51.2V LiFePO4 golf-cart packs at US$542-854 per piece on Made-in-China.com.

China's battery-pack listings on Made-in-China.com (June 2026) span 49,329 Li-polymer SKUs at US$0.8-1,189/piece and 5-12kWh LFP home-storage packs at US$1,079-1,189, with 18650 cell demand from LG, Samsung SDI, Murata (ex-Sony) and Panasonic dominating industrial packs.
Global battery packaging market is forecast to reach $56.00Bn by 2027 at 11.1% CAGR (2022-2027), while the redox flow battery segment is projected to hit $403.0M by 2026 at 15.2% CAGR (2019-2026), with LFP chemistries driving the largest cell-level demand.

Global cobalt market reached USD 16.99 billion in 2025 with a 7.63% CAGR forecast through 2035 (USD 35.44 billion), but the 2026 supply side is dominated by a small cluster of African and Chinese-controlled producers; the competitive map is shaped by DRC mine concentration, Indonesian HPAL capacity
Global cobalt demand is forecast to grow 5.1% CAGR to 410.9kt by 2030, with battery-grade output and DRC production (271.3kt) anchoring supply; the Cobalt Institute's 2024 report flags a 9.6% demand lift by 2030 under Paris-declaration assumptions.
Lithium-ion battery anode demand is on track to reach USD 81.24 billion by 2030 from USD 19.06 billion in 2025, a 33.6% CAGR, with Resonac adding 11,000 t/yr of natural-graphite capacity at Sakaide, Japan from October 2026, reshaping the materials competitive map.

Lithium compounds demand is projected to reach $30.53Bn by 2030 at 8.30% CAGR (2024-2030), while lithium-ion battery anode market expands to $81.24Bn by 2030 at 33.6% CAGR (2025-2030), per IndustryArc and MarketsandMarkets research.

Global automotive Li-ion battery manufacturing is concentrated among roughly a dozen Asian and US players led by CATL, LG Chem, BYD and Panasonic, with Asia-Pacific holding the largest regional share.

Brooklyn homeowners pay $3.31/W for installed residential PV as of June 2026, while Singapore's West region holds 476.4 MWp of solar capacity and global PV costs have fallen 89% over the past decade, reshaping the 2026 competitive landscape across cell architectures, installers and OEM pricing.

Global solar energy market is projected to grow from $268.93B in 2026 to $606.18B in 2030 at 22.5% CAGR, with portable solar panels and recycling forming two fast-moving adjacent segments worth tracking through the decade.
Datacenter CPU demand rebounded in late 2025 as AI training, reinforcement learning and vibe-coding workloads pushed Intel, AMD, Nvidia, AWS, Microsoft and Google to refresh core counts, memory bandwidth and chiplet packaging; the 2026 roadmap centres on 88-91 cores, 1.2-1.5 TB/s memory subsystems,

PassMark's Q1 2026 CPU market-share snapshot, last updated 11 July 2026, shows Intel still leading overall but losing share to Apple in laptops and to AMD in desktops, with Qualcomm a niche mobile factor.
Cross-border shipment records filed with customs (bills of lading, shipping bills, commercial invoices) form the working dataset behind every data center import and export market study, with the 2026 sourcing window shaped by China-origin server, switch and UPS HS-code flows and India/US/UK director

Photovoltaic module and cell import/export flows in 2026 are tracked through customs trade-data platforms, with China-based bonded zones, OEM trading firms, and historical EPIA-style outlooks shaping the reference baseline that procurement teams use to size spec bands and sourcing windows.
Global solar panel trade flows in 2026 are dominated by crystalline silicon PV modules shipped under HS code 8541.43, with China, Vietnam, Malaysia and Thailand holding the bulk of export volume and the EU, India and Brazil leading import demand.

Global electric vehicle import-export data flows remain lopsided in 2026: Chinese OEMs wholesale complete BEVs at US$19,000-21,200/unit FOB while global customs data platforms track over 200 sourcing markets for the same NEV HS-code family.

China's primary lithium cell and battery exports reached 48,171.329 thousand USD in May 2026, up from 46,443.932 thousand USD in April 2026, against a 2003-2026 monthly average of 14,983.595 thousand USD.

MEMS sensor average selling prices in 2026 H1 sit in the USD 0.18-2.50 unit range, with automotive safety 6-axis IMUs at USD 1.10-1.60, industrial pressure die at USD 0.85-1.40, and consumer 6-axis falling below USD 0.30 at 10k+ reels.
China holds the dominant share of global photovoltaic module manufacturing capacity in 2026, with nameplate output above 500 GW and provincial hubs in Anhui, Jiangsu and Guangdong; IEA projects total global capacity will clear 1.5 TW by 2035.
Global air compressor market is projected to reach USD 40,149.6 million by 2033 at 4.0% CAGR, with China holding the largest production base, followed by Germany, the US, Japan, and Italy as the five dominant hubs.

Global LNG terminals saw a Feb 2026 market-trend report land at Allied Market Research, with the liquefaction and regasification tech split tracked through residential, commercial and industrial end users; ICIS flagged a 2024 rebalance after the 2022 Russian gas shock, and Deloitte's 2026 outlook pu

Consumer-grade quadcopters with 1080P HD cameras are clearing FOB Shenzhen at roughly US$25 per unit at 20-piece MOQ, with one manufacturer listed at 600,000 PCS/month capacity. AliExpress retail roundups in 2026 highlight a four-model shortlist spanning toy, camera, GPS and brushless tiers.
Global additive manufacturing (AM) production capacity is concentrated in a handful of national clusters, with the United States, China, Germany, and Japan leading metal powder bed fusion (PBF) and directed energy deposition (DED) install bases, and India, the UK and South Korea expanding polymer/in

Global industrial valve output is dominated by China, the United States, Japan, Germany and Italy, with China holding the largest production base by volume and the US, Japan and Europe retaining strength in high-pressure, cryogenic and specialty alloy valves per 2025-2026 industry data.

Bearing price bands on Made-in-China.com on 2026-07-10 sit at US$ 5–20 per piece for general ball bearings (1 pc MOQ) and US$ 100–1,000 per set for slewing/turn-table bearings, with raw-material drags from BDO and bearing-steel surcharges keeping 2026 H2 quotes firm.

China's machine-tool exports took 21.6% of the 2025 global share, overtaking Germany at 16.7% for the first time. Japan and Germany still lead on CNC penetration rate inside their own plants, while India and China dominate retrofit/entry-level capacity additions through 2026.

Chinese mid-tier CNC machines are now quoted at US$12,800-45,000 per piece on made-in-china.com, while 4-axis controllers fall to US$360-785; with the global CNC market forecast to reach USD 60.8 billion by 2031, entry-level hardware costs are decoupling from system-level growth.
Global desalination capacity exceeded 115 million m³/day of contracted new-build between 2020-2025, with Saudi Arabia, UAE, Israel and China leading installed and forward-project pipelines. China holds a dual role as a major EPC hub and a fast-growing build-own-operate market alongside Chile, India

China's petrochemical build-out is the dominant 2026 capacity story: its 2025 startup of the world's largest single-site olefin plant shifts global ethylene, propylene and derivatives tonnage further eastward, while GCC operators report an 8% energy-intensity reduction over two years.
Qatar, the United States, and Australia together control the majority of operating global LNG export capacity as of late 2025, with US, Qatar, and US-led Mozambique/Russia expansion tracks shaping 2026-2028 supply additions.

Global aerospace manufacturing in 2026 stays concentrated in the United States, China, France, Russia and the United Kingdom across fixed-wing, rotorcraft and space segments, with the US and China alone covering the majority of airframe and engine output and Europe anchoring the wide-body twin-aisle

Heat pump price bands split sharply by capacity and application in 2026: residential central units sit at US$8,000–15,000 FOB-equivalent, commercial pool/spa R32 units cluster US$698–2,941 per set, while dairy hygienic plate heat exchangers run US$20,000–50,000 per set. The market rep

China remains the dominant electric motor manufacturing base as of June 2026, with Zhejiang and Shanghai leading AC induction, BLDC and gear motor production capacity, while automotive micro-motor demand pushes new sub-supply chains globally.

Power semiconductor pricing into 2026 is being pulled in two directions: AI-related compute demand is straining silicon capacity, while a 2019 demand-cycle case shows that IDM destocking can flip the market from shortage to surplus within quarters. Procurement should track 600V/1200V IGBT and 650V S

SEMI's 2019 forecast put worldwide MEMS and sensor fab capacity on a 25% growth path to 4.7 million 200mm-equivalent wafers per month by 2023, with China and the Americas leading the build-out; the actual 2026 country split and utilisation remain driven by 6"/8" fab conversions and IDM packaging dom

Global mined copper output reached roughly 22 million tonnes in 2024, with Chile, Peru, the DRC, China and the United States leading production. Refined capacity is concentrated in China, and a structural deficit emerged after the 2023 Cobre Panama closure.

Global lithium production capacity is concentrated in Australia (hard-rock spodumene) and the China-linked conversion hub, with Argentina and Chile holding the dominant brine reserve base. As of 2026, the supplier map splits into three tiers by chemistry and geography.
Fuel-cell system price for mobility and stationary use tracks hydrogen LCOH more than stack hardware cost; 2026 outlook hinges on electrolyser capex decline and platinum-group metal loading per kW.
Global lithium-ion cell production reached roughly 2,950 GWh of nameplate capacity in 2025, with China holding an estimated 75-80% of that footprint, followed by the U.S., South Korea, Japan and a fast-rising European cluster. Cell formats split LFP at about 48% and NCM/NCA near 47% of 2025 shipment

Global AI chip production capacity is concentrated in Asia, which held 86.80% of the semiconductor foundry market in 2025 per Fortune Business Insights, with Taiwan, South Korea, China and Japan controlling leading-edge logic and memory nodes.

China leads global nuclear power capacity combining operating and prospective fleets, with the United States holding the largest operating fleet at roughly 95 GW and France ranking second among operators, while Russia and India round out the top five prospective builders per the Global Nuclear Power

Nuclear levelised cost sits in a 2–4× band against gas+CCUS and onshore wind on the 2026 market-research baseline, with PWR capacity still accounting for roughly 70% of global fleet and a January-2026 market report re-issuing the outlook at US$4,490.
Global operational offshore wind capacity hit 80.9 GW in mid-2025, a 15% year-on-year rise, with China leading installed base, the UK and Germany dominating European capacity, and the US trailing despite pipeline depth.

Global natural gas marketed production crossed 4 trillion cubic meters in 2024, with the United States, Russia and Iran leading country-level output; Indonesia's marketed gas fell to 65,097.7 million cubic meters in 2025 from 65,190.0 in 2024, while China scaled single-field capacity past 50 billion

Henry Hub front-month natural gas settled at 3.28 USD/MMBtu on 8 July 2026, up 0.50% on the day, 4.50% on the month and 2.09% year-on-year, with weather-driven cooling demand and LNG export pull anchoring a modestly bullish near-term curve into Q3 2026.
Industrial connector FOB prices on Made-in-China.com in May 2026 cluster in two bands: USD 0.183-0.203 per piece for IP67 solar connectors, and USD 0.46-1.47 per piece for 2.00 mm pitch side-entry PCB headers, while tooling such as 16-400 mm² hydraulic crimpers sits at USD 249-410 per set.
China-made cable and wire spot-quote bands for 2026 span US$0.05/m for drop fibre up to US$60,000/set for recycling lines, with conductor and shielding copper driving mid-band product pricing between US$1.00–10.00 per metre.

China-sourced industrial valve FOB bands cluster at US$0.17–2,150 across control, ball, gate and floating types as of June 2026, with MOQ-driven floors and material/actuator cost as the dominant price levers heading into H2.

Industrial pump FOB prices in mid-2026 show centrifugal units holding US$34.99–35.53 per piece at 100-piece MOQ from Zhejiang suppliers, while heavy submersible sewage pumps range US$500–50,000. Raw-material pass-through and a 17.8% YoY jump in US industrial leasing activity are the two biggest 2026

Air compressor factory-gate price bands in mid-2026 span US$1,600-70,000 per set on Made-in-China listings, with 40HP fixed-speed rotary units near US$1,600, 55kW oil-less screw compressors at US$3,200-52,890, and 6-stage AC centrifugal packages up to US$70,000.
Pneumatic component pricing in mid-2026 shows a clear bifurcation: low-end commodity rods and tire casings sit at USD 0.10-0.72/piece at 1,000-piece MOQ, while integrated pneumatic tube systems as a market are projected to grow from USD 2.50 billion in 2024 to USD 5.50 billion by 2036 at a 6.7% CAGR

Global machine tool production capacity in 2026 is anchored by China, Japan, and Germany, with IFR-tracked industrial robot sales of 542,000+ units in 2025 and a ~13% share for ABB alone signalling where upstream CNC and cutting-machine demand concentrates. Sourcing decisions now depend on coun
CNC milling centers list at US$40,000-70,000 FOB China on audited-supplier platforms, while mid-tier vertical lathe/turning cells cluster near US$50,000 and sheet-metal press brakes anchor around US$33,200-33,600, defining the 2026 import-price floor for machine tools.
Global mining-equipment production remains concentrated in four manufacturing hubs — China, the United States, Germany/Japan, and Australia/Canada — with China leading on installed volume of dump trucks, roadheaders and underground auxiliary equipment in 2026.

Mining equipment price trend 2026: large underground trucks in the $300k-$1.2M band, surface drills $5k-$18k at the entry tier, services market on a 5.2% CAGR to $103.4B by 2030, with China-led OEM supply and refurbished Cat AD30/Epiroc MT42 stock pulling the floor.

Seawater desalination capital cost in 2026 sits in a USD 1,700–9,868 per-piece band for Chinese containerised RO skids, while LCOW for new SWRO plants still ranges 0.5–1.2 USD/m³, driven by energy, membrane and EPC prices.

China domestic propane held around 5,750 yuan/mt while FOB propane was 73.64 USD/barrel, with international FOB values ranging 76.91 to 84.55 USD/barrel per ECHEMI snapshots dated 2026-06-20. The Business Research Company lists a 2026 global petrochemical report at US$4,490 covering ethylene, propyl
Global satellite manufacturing capacity in 2026 is dominated by the United States, China, the European Union, and a small cohort of second-tier producers (Japan, India, Israel, Russia), with the top three regions accounting for the vast majority of commercial and government throughput.
Satellite hardware price bands in 2026 span five orders of magnitude, from US$0.025 crystal resonators to US$950 GNSS RTK receivers and US$4,490 full market reports, with C/Ku/Ka band split and L-band resilience driving procurement decisions.

Global drone manufacturing capacity is concentrated in China's Shenzhen-Dongguan-Guangzhou industrial cluster, with single-factory monthly throughput benchmarks visible at OEM/ODM lines and a clear pipeline feeding U.S. and EU service operators. Producer-side capacity disclosures and integrator serv

OLED panel pricing through 2026 is being pulled in two directions: large-area OLED TV panels hold premium price bands (LG OLED TV line still marketed as the brand's flagship display technology), while small/medium OLED monitor adoption is widening as PCWorld documents a "transformative" upgrade
China holds the dominant share of global display-panel production capacity, with South Korea's LG Display ranked as the world's largest LCD panel maker. Mannst's breakthrough OLED coating equipment order in January 2025 signals accelerating domestic substitution in China for advanced display to
Flat-panel display ASPs are rebounding in 2026 after a multi-quarter trough, with March 2025 reference data showing 65-inch TV panels at $177, 27-inch IPS monitor panels at $62.7, and 23.8-inch IPS at $49.4. The global display market sits at $124.1B in 2022 and is projected to reach $244B by 2032 at

Chinese LED chip suppliers are projected to hold 54% of global production capacity in 2017, per LEDinside, with Aixtron shipping an AIX G5+ C MOCVD cluster to UK-based Plessey Semiconductors in Q3 2016 to expand LED fab output.

LED spot FOB prices in mid-2026 span extreme ranges — P2.5 curved booth panels at US$650-840, IP66 street fixtures at US$19.14-35.78, beauty panels at US$779-911 — while TrendForce's 2026-06 panel report shows TV/notebook flat and monitor panels rising.

China dominates global heat pump production capacity in 2026, with Qingzhou (Shandong) factories like Lucy Solar shipping 500-unit MOQ air-cooled solar PV heat pump units; Midea's Italy base anchors EU build-out.

Global battery energy storage production is dominated by three Chinese cell makers — CATL, BYD, EVE — supplying roughly two-thirds of LFP cell output, with South Korea's LG and Samsung SDI holding the high-end nickel-rich chemistry tier. Cell capacity scales 280-314 Ah per prismatic LFP unit in 2026

Battery energy storage system (BESS) pack pricing in mid-2026 sits in a US$877–946/piece band for Chinese OEM LiFePO4 cabinets, with LFP cells holding flat through late 2024 and a modest 2025 uptick flagged by TrendForce as the supply baseline for 2026 procurement.

China-made industrial electric motor FOB bands span roughly US$ 4 for small BLDC fan units to US$ 15,000 for 200 kW crane YZR slip-ring units as of 2026-06-05; the July 2026 sourcing picture is a wide spread driven by power class, frame, duty cycle, and magnet content.

On 2026-07-07, China-made industrial IGBT rectifiers for water treatment, electroplating and rare-earth smelting list at US$4,280–5,500/piece on Made-in-China.com, with no clear downward or upward bias in 2026 Q2 quotes.

Global power semiconductor production capacity is geographically concentrated: mainland China leads on assembly and module packaging, Taiwan dominates foundry wafer capacity for 200mm/300mm, Japan retains leadership in IGBT and SiC substrate materials, while the US and Europe focus on design IP and
PCB spot prices are decoupling from upstream panel and BDO chemical benchmarks in mid-2026, with design-software spending on track for $7.90B by 2031; sourcing teams should anchor on copper-clad laminate indexes and yield-driven lead times rather than headline board quotes.

Global silicon-wafer production capacity reached roughly 974.2 GW by end-2023, up 46.7% year-on-year; the country mix remains anchored by East-Asia-based producers, with China expanding share in both photovoltaic and 150-200 mm semiconductor wafer lines.

Mono 300mm prime wafers from Chinese suppliers cluster at US$10-100 per piece for MOQ 25, while 300mm listing pages on Alibaba sit in the wholesale rack and LONGi maintains a daily updated silicon price index. Volatility, not price level, is what defines the 2026 wafer market.

CBCIE tracked 1# scrap copper and waste-copper cable prices in Hubei and Yunnan through June 2026, with China domestic price tabs updated on a daily cadence; the live series gives buyers the only clean read on the cathode-to-scrap spread that sets procurement budgets through Q3 2026.
China produced 37.08 million tons of primary aluminum in 2020, a 4.9% year-on-year increase that reversed a 0.9% decline in 2019 and confirmed its position as the dominant national producer. Brazil's Albras held 460,000 t/yr of nameplate capacity as of 2017, averaging 406,000 t/yr across 33 yea
Aluminum spot in China tracks two divergent feeds in early June 2026: Hebei scrap quotes show raw miscellaneous aluminum (Fe<3%) at 16,420 RMB/ton on June 5, while downstream fabricated goods like aluminum sunroom glass houses span US$76.86 to US$388.00 per square meter FOB Guangdong.
Global crude steelmaking capacity tracked by Global Energy Monitor reached 3.7 billion tonnes across plants in 2026, with China holding roughly half of installed blast-furnace and basic-oxygen output capacity and India the second-largest national base.

Steel prices in mid-2026 are anchored by Made-in-China listing bands: Q215/Q345 round bar at US$0.45–0.78/kg, C75/1075 saw coil at US$0.91–2.53/kg, MOQ 500 kg, with 2026 H1 driven by rare earth, nickel and antimony feedstock swings.
LME nickel held near US$15,000/t in early July 2026, far below the 2022 short-squeeze spike above US$100,000/t, while Chinese Ni≥22% nickel-sulfate averaged around RMB 27,000/t on the Shanghai spot market per CBCIE.

Cobalt chloride and concentrate prices held flat in the week of 8–10 June 2026, with CBCIE Metal reporting a stable trend and balanced supply-demand. Cobalt-based alloy product prices on Made-in-China.com range from $8.20 to $125.00 per kg depending on grade, signalling that downstream cobalt commod
China still controls the majority of global rare earth production and refining capacity, with US$ 14.1 B 2025 market value and 7.4% CAGR through 2036 driven by EV and clean-energy demand, while eight producing countries split the remainder.

Global hydrogen fuel cell production capacity is concentrated in three manufacturing clusters: the US (DoE-supported stack assembly), Zhejiang, China (PEM/generator OEM/ODM volume), and Korea/Japan (vehicle programmes). IPHE membership reached 30+ countries by July 2026, with Kenya joining 15-Jun-20

Additive manufacturing is on track to exceed US$44 billion in annual revenue by 2033, per IDTechEx's June 2026 webinar forecast. Material and printer pricing in 2026 is being driven by uptake in jigs, fixtures, and tooling, not consumer hype.

China's 3D printer exporters ship roughly one machine every eight seconds to overseas buyers, anchoring a global production base where Chinese FDM/FFF desktop units dominate by volume while the US and Germany lead industrial metal-powder bed fusion capacity.

3D printer pricing in 2026 spans US$0.05–0.30 per 3D postcard unit at Chinese wholesale level and US$4,490 for a full 150-page global market report, with system price bands shaped by printer type (desktop vs industrial) and technology (FDM, SLA, SLS, DMLS, PolyJet, inkjet). Per-part c

Global industrial robot output is dominated by Japan, China, Germany, South Korea and the US, with mainland China holding the largest installed base and a 13.7% CAGR projected through 2034 (USD 23.71B → USD 85.63B).

China-made industrial robot price floor dropped to roughly US$6,000 per unit for delta/pick-and-place SKUs in May 2026, while the global automation market report priced at US$4,490 tracks a multi-year 2026-2035 outlook. Expect continued downward pressure on Chinese SCARA/delta and on cobot entry tie
Server hardware global production is concentrated in US-OEM assembly, Taiwanese ODM/EMS board and chassis build, and Mainland China PCB/connector sourcing, with rack, tower and blade form factors split by application class.

Northern Virginia, the Phoenix metro, the Dallas–San Antonio corridor and the Øresund region (FLAP-D) anchor hyperscale data-center floor space today, while the US Data Center Operations & Maintenance Service Market is tracked at roughly $40B in 2023 with a forecast to $75B, per Verified Industry In
China held about 60% of global wind turbine production capacity in 2023, with onshore and offshore units anchoring national output; price competition of roughly 30% is reshaping where OEMs place factories and which control-system suppliers feed them.
IEA forecasts global PV module manufacturing capacity will clear 1.5 TW by 2035, with China holding the dominant share of monocrystalline silicon, glass and downstream module output. CBCIE tracks 2025 capacity for mono-Si, PV glass, silicon carbide and silicone DMC.
As of June 2026, U.S. residential solar sits near $3.01/W installed, with mono cell spot FOB prices clustered at $0.14–0.22/W and 320W modules on the wholesale line at $0.21–0.22/W from Chinese OEM factories.

Global EV production capacity is led by China, with BYD surpassing Tesla in 2023 by selling over 3 million vehicles; the EV plastics market is projected to grow from USD 3.9B in 2025 to USD 45.8B by 2035 at a 28% CAGR, with BEVs holding 38.2% share.
China-made 2024-model EV passenger cars were quoted at US$15,000-16,000 for Xpeng Mona M03 610-702 km range trims on Made-in-China.com listings dated 2026-06-11, while 2024 MG Cyberster long-range BEV started near US$41,000 on the same platform.
Global EV battery production capacity is concentrated in China, with the United States, South Korea, Japan and Germany holding secondary shares; the lithium-iron-phosphate (LFP) chemistry has overtaken nickel-cobalt-manganese (NCM) in unit volume since 2022.
Battery-grade lithium carbonate 99.5% and graphite anode powder sit at the center of the 2026 Li-ion price stack, with Chinese domestic Li2CO3 spot and MOQ-1 cell-pack quotes at US$542-854 anchoring the procurement reality on 2026-07-03.
Global CPU production capacity in 2026 is concentrated in Taiwan (TSMC ~67% of leading-edge logic), South Korea (Samsung Foundry), mainland China (SMIC, Hua Hong, YMTC adjacent) and the United States (Intel, GF, Micron), with the boundary drawn by EUV-class lithography, mature-node wafer counts and

China leads 2024 fab construction with 18 new facilities as global wafer-start capacity climbs 6.4% to over 30 million wpm, reshaping the global semiconductor production map into 2026.
Global LNG is entering a supply-driven super-cycle, with roughly 40.7 million tonnes of new liquefaction capacity expected in 2026 and a cumulative 2026-2030 build-out of about 202 Mt; the US and Qatar now anchor roughly 70% of incremental volumes.
Intel and AMD dominate 2026 desktop CPU retail rankings, with AMD's Ryzen 7 9800X3D at ¥3,799 and Intel's Core Ultra 9 285K at ¥4,799 leading China's mainstream hot-CPU charts as of June 2026.
Vale, Tsingshan, Glencore, BHP and Norilsk Nickel remain the dominant Class I nickel producers in 2026, supplying the LME-grade cathode and NPI/briquette feedstocks that drive stainless, battery and nickel-alloy markets. Mid-tier players Sherritt, Eramet, Anglo American and South32 round out the mer
The "top IGBT companies 2026" question is not answerable from any of the eight supplied sources, which cover Colorado sports firms, US web hosts, SEO agencies, Colorado nanotech, news/AI/coupon/3D-printing companies only — zero IGBT, power-semiconductor, or inverter content.
Global EV battery demand continues to expand sharply, with Statista projecting the lithium-ion battery segment to cross into the triple-digit-billion-dollar range by 2032 from a 2023 base, while the EV on-board charger segment — a downstream telltale for battery-equipped vehicle production — is
Boeing ranks as the largest aerospace employer on Built In Colorado's 2026 design-company list with 170,000 staff across 33 offices, while Oracle E-Business Suite and the MDPI journal Aerospace shape the supporting 2026 tooling and research landscape.
Copper demand in 2026 is being reshaped by four hard engineering vectors: marine MGPS anodes, mining power cables, building wiring, and decorative wire for color-of-the-year finishes. China-origin supply dominates across all four, with MOQs from 100 m to 1,000 t and price bands from US$0.13/kg to US
Hyundai Electric's Alabama transformer facility anchors a 2026 capacity build-out for US grid and data-centre demand; distribution-transformer market sat at US$ 20.1 B in 2023, with digital monitoring and eco-fluids reshaping spec choices.
Global satellite antenna market is on track to reach USD 7.5 billion by 2026, satellite remote sensing services hit USD 7.5 billion in 2026, with active phased-array, LEO constellations and Earth-observation demand driving growth.
China-based PCB makers PCBASIC and LST anchor the 2026 short-run and one-stop EMS segments, with NextPCB leading process education; selection hinges on layer count, turnaround, and assembly integration.
Nickel demand in 2026 is being reshaped by Indonesia's HPM ore policy, battery-grade nickel price competition among Chinese cell makers, and a nickel superalloy market on track past $10B with 6.7% CAGR (2020–2026). Stagnant stainless output forces miners to defend margin through grade
As of June 2026, the global satellite industry is led by SpaceX (Starlink LEO broadband), Eutelsat-OneWeb, Amazon Project Kuiper, SES, Iridium, Viasat-Inmarsat, Telesat Lightspeed, China SatNet and GuoWang, with throughput, terminal cost and orbital altitude as the three dominant decision criteria.
Refined copper demand is tracking a structural lift through 2026 driven by grid, EV and data-centre build-outs, with multiple commercial market reports placing 2026 global market value in the high-tens-of-billions USD range and long-horizon forecasts to 2050 from Benchmark Mineral Intelligence.
Server hardware is a USD 130+ billion installed base in 2026, with management-software spend alone scaling from USD 6.40B (2025) to USD 13.89B (2036) at a 7.3% CAGR; growth is driven by AI workloads, ARM penetration, and edge build-outs.
Public-domain LED market research published 2026 places the 2026 global LED market in the low-to-mid tens of USD billions depending on scope, with packaged + lighting + automotive + display sub-segments each on their own CAGR curve.
Bearing demand in 2026 is anchored by two concrete forecasts: sliding bearings for rail projected at USD 1,531 million by 2027 (CAGR 6.4%) and precision ball bearings sized for a USD 4,250-report market study; bearing-isolator aftermarket is forecast at USD 1,584.44 million by 2030.
Mining-equipment demand is on track to roughly double between 2026 and 2032, with the wider earthmoving segment projected at USD 76.27 Bn (2026) to USD 115.5 Bn (2033) and crawler/wheeled excavators alone set to hold 35% of that share.
Global natural gas market was valued near USD 1.0 trillion in 2025 and is projected to grow at a 6.1% CAGR through 2034, with Asia-Pacific leading demand. Compressors — a downstream equipment segment — sat at USD 20.78 billion in 2025 with a 4.63% CAGR to 2031.
IGBT & thyristor market tracked by MarketsandMarkets covers 7,500+ surveyed firms, with the IGBT segment forecast to expand at mid-single-digit CAGR through 2036, anchored by EV traction inverters, industrial drives, and renewable power conversion. SiC displacement begins above ~650 V automotive and
Top battery energy storage companies in 2026 are split between Chinese cell-and-system integrators (QINKUAL, Ganfeng LiEnergy) and second-life specialists (Connected Energy), with BESS container formats, LiFePO4 chemistry and sodium-ion pilots dominating new product pages as of June 2026.
Silicon nitride hybrid ceramic bearings, EV drive-motor lubrication regimes, and air-bearing Industry 4.0 retrofits dominate 2026 bearing procurement shifts, with the China International Bearing Industry Exhibition (Dec 9-12, 2026, Shanghai) anchoring 1,000 exhibitors and 60,000 visitors.
Hydraulic system industry trends for 2026 are anchored by the fracturing segment moving from a USD 58.5B 2025 base to a USD 63.2B 2026 forecast on the way to USD 93.9B by 2033, with cylinders, power units and valves pulling the broader industrial hydraulics market along.
Global electric motor demand is tracking a 2025-2035 forecast on Transparency Market Research, while hub and in-wheel EV motors are sized at $4,395M by 2026, anchoring spec-driven sourcing for industrial buyers in mid-2026.
Fuel-cell hydrogen reached a market size of $14 B by 2030 at a 19% CAGR, with 105+ years of filtration know-how now repurposed for stack air intake, calorific value of 140 MJ/kg driving mobility pilots like BMW iX5 Hydrogen.
Industrial valve demand in mid-2026 is anchored by petrochemical, water and power upgrades, with API 6D/API 600 gate and ball valves and 4-20 mA/HART electric actuators leading spec activity. Sourcing remains China-led.
Server hardware in 2026 is defined by uniform node sizing for clustered workloads, cryptography-accelerated mainframes, and tight minimum-resource envelopes; OEMs like Oracle and IBM publish 1-2 GB RAM, 300 MB disk, and 16-coprocessor ceilings as the floor.
Industrial pneumatic systems in 2026 are dominated by a tiered vendor set spanning Festo, SMC, Parker Hannifin, Emerson (ASCO), and Camozzi, with Chinese OEMs like Aignep, AirTAC and Ningbo Pneumatic capturing mid-tier share across cylinders, FRLs, fittings and tubing.
No GPU-vendor ranking was found in 2026-06-23 research; available data covers Colorado AI, sports, 3D printing, and news companies, none of which is a discrete GPU manufacturer. This article therefore maps the AI-accelerator and industrial-graphics ecosystem using adjacent facts only.
Mining equipment market 2026 forecasts converge above USD 1 trillion cumulative revenue through 2035, with underground fleets and electric/hybrid powertrains the highest-velocity segments. Procurement should anchor spec sheets on equipment class, power source, and regional build-out signals.
Toyota, Plug Power, PowerCell, Ballard, Cummins and Doosan lead the 2026 hydrogen fuel cell vendor map across automotive, stationary, and heavy-mobility segments per industry directories and OEM disclosures.
Sanan, Cree, Nichia, Osram and Lumileds remain the five LED chip vendors that dominate 2026 spec sheets, while PPA- and AlGaInP-packaged top-chip SKUs from China suppliers cluster at US$0.016–0.99/piece MOQ 200–10,000.
EV charger market is consolidating around AC Level 2 and DC fast charging, with Asia-Pacific holding the largest installed base and Level 2 chargers leading unit volume. Hardware buyers should anchor DC fast-charger spec on CCS2/NACS connector compatibility, 150–350 kW power modules, OCPP 1.6/2.0.1
The global air compressor market hit $28.4B in 2021 and is on track to reach $46.2B by 2031 at a 4.9% CAGR; 2026 lineups show centrifugal, oil-injected screw and high-pressure breathing-air builds dominating the spec sheet, with permanent-magnet VFD and oil-free rail piling on efficiency gains.
CRU's Wire & Cable Connections Summit 2026 (23-25 June, 20th edition) drew the global metallic wire community to map demand, while Made-in-China lists 1,000+ wire/cable machinery SKUs at US$9,999-60,000 set-level MOQ, defining the 2026 sourcing map.
Four flagship wire and cable trade events — wire 2026 Düsseldorf, wire China 2026, wire India 2026 and CRU Wire & Cable Connections Summit 2026 — converge in 2026 to frame an industry pivot toward energy-transition cabling, stainless steel conductors, AI-driven production lines and ASEAN capacity bu
Top air compressor companies 2026: Atlas Copco, Ingersoll Rand, Kaeser, Sullair, Gardner Denver, Elgi, Doosan and CompAir dominate industrial sales, with Chinese exporters like Ziqi Compressor listing 40HP rotary units at ~US$1,600-5,972 FOB Shanghai.
The hydrogen fuel cell market is valued at USD 7.1B in 2026 and is forecast to reach USD 18.2B by 2036 at a 9.9% CAGR, with PEMFC, SOFC, PAFC, MCFC and DMFC types competing across stationary, transport and portable applications per the June 2026 outlook.

Spot semiconductor pricing on Made-in-China lists a 60 V/64 A N-channel MOSFET (BSC066N06NS) at US$ 0.40–15.00 per 10-piece MOQ and an FGH60N60SFDTU 600 V/120 A field-stop IGBT at US$ 0.001–0.10 per 10-piece MOQ as of June 2026.
Global additive manufacturing market is forecast to reach $35,244.3 million by 2026, with laser processing, the upstream enabler, projected to hit USD 30,862.1 Mn in 2026 at 10% CAGR through 2033.
LEO mega-constellations, flat-panel user terminals, and HTS capacity are reshaping the 2026 satellite industry: a 7.4% CAGR lifts satellite network equipment to USD 42.6 billion by 2026, with satellite antennas forecast to USD 10.5 billion.
Global rare earth metals market is valued at US$ 14.1 Billion in 2025, projected to reach US$ 30.9 Billion by 2036 at 7.4% CAGR, driven by NdFeB magnets, EVs, wind turbines and defense demand.
Global industrial pump market is tracked across centrifugal, positive-displacement, hydraulic and heat-pump variants; 2026 forecasts show hydraulic pumps alone projected to grow through 2035, industrial heat pumps adding $805.4 Mn in opportunity 2025-2030, and broader process-equipment dem
Global hydraulic-pump spend is set to scale from USD 11.46 Bn in 2026 toward USD 17.81 Bn by 2035 at a 5.0% CAGR, with Asia Pacific holding the dominant regional share. Adjacent hydraulic segments — fracturing fleets and turbine installations — pull the same upstream supply chain, reshaping 2026 sou
Shandong-origin Chinese industrial aluminum extrusion profiles are listed at US$3,100–3,500/tonne MOQ on Made-in-China as of June 2026; the same portal indexes industrial aluminum tube supply alongside container-house prefab structures in the US$1,500–3,000/set band. ALUMINIUM Düsseldorf r
Global steel market tracking for 2026: steel casting demand is set to add USD 9.87 B at 5.2% CAGR through 2030, with APAC accounting for 55.4% of growth, while alloy, silicon and stainless steel sub-segments diverge sharply by end-use.
Global electric-motor demand in mid-2026 is bifurcating: industrial induction units from Chinese suppliers cluster at US$5.15–5.35 for fractional-HP fans and US$350–450 for 1–10 piece MOQ industrial sets, while EV traction programmes per IDTechEx's 2026-2036 report chase rare-earth reduction, axial
Nuclear power procurement in 2026 is dominated by ASME/ASTM-governed forgings, Class 1 sealing stacks and NDT calibration blocks; Chinese plants Qinshan, Daya Bay, Ling'ao, Tianwan, Sanmen, Hongyanhe and Fuqing set the working reference list.
Global air compressor market reached $28.4B in 2021 and is projected to hit $46.2B by 2031 at 4.9% CAGR, with North America alone at $5,754M by 2023 and India tracked separately for portable vs stationary splits.
No GPU-specific market sizing, vendor-share, or shipment data was published on 2026-07-03 in the supplied research feed; the four sources attached cover fish protein, exterior car accessories, interactive displays, and Nano RAM instead. The article below therefore relies on 2026 baseline market figu
Floating wind turbine market is forecast to grow from $3.2 billion in 2019 to $30.6 billion by 2027, while offshore wind installation vessel and small-wind reports refresh through Feb 2026.
Global Li-ion EV battery-pack demand continues climbing through 2026, with IDTechEx projecting sustained pack-volume growth across road and non-road EVs (2026-2036 horizon). 2026 also marks the first US sub-$30k EV class with multiple entries, the cheapest near $20,000.
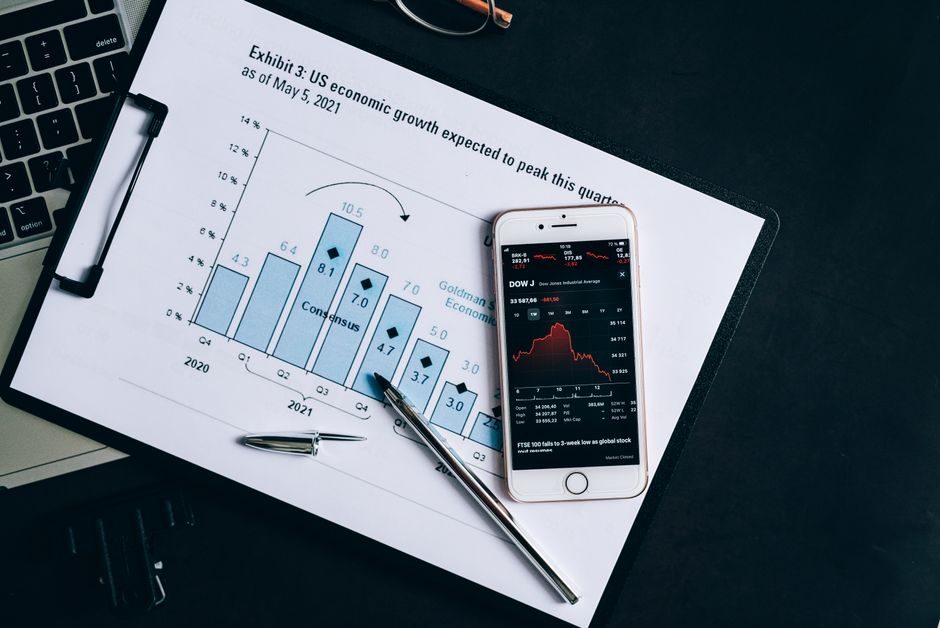
Global lithium-ion battery demand is forecast to push the market past $400 billion by 2032, up from roughly $50–60 billion in 2023; lithium hydroxide feedstock, mobile packs and forklift traction packs are the three side-bets shaping 2026 procurement.
2026 LED display market is projected at USD 12.176B globally and CNY 95B+ in China, with fine-pitch P1.0–P1.8 plus Mini/MicroLED COB packages leading the spec shift from price competition toward one-stop, scene-driven solutions.
Delivery drone market is projected at USD 1.01 Bn in 2026, scaling to USD 12.33 Bn by 2033 at 42.9% CAGR, with multi-rotor wings holding 48.7% share; HAPS and BVLOS rulemaking are the 2026 spec gates
Hyperscale build-out, AI workload power density, and secured-power joint ventures are reshaping the data-center sector in 2026, with KKR's Helix platform and a $17.5bn Amazon AI loan anchoring deal flow on a market now projected past $600bn.
2026 marks the inflection point of the global LNG super-expansion cycle, with ~40.7 Mt/yr of new liquefaction capacity coming online and cumulative 2026-2030 additions of ~202 Mt (+40% over 2025, ~6.8% CAGR). Supply growth first systematically outpaces demand growth since 2020, while US, Qatar, Cana
Offshore wind is scaling into multi-GW North Sea and Norwegian Sea build-outs, with 96.8 MW reference projects like Aberdeen EOWDC operating, May 2026 German onshore awards at 5.06 ct/kWh, and ecosystem events running through 2026.
Top transformer manufacturers in 2026 split across three sourcing tiers: global Tier-1 OEMs (ABB, Siemens Energy, Hitachi Energy, Schneider Electric, GE Vernova, Mitsubishi Electric, Toshiba, Eaton) anchored in EU/J/US/KR/JP capacity; mid-tier system builders (Hyosung, Weg, Elsewedy, TMEIC, TBEA, XD
Global rare earth metals market reached US$ 14.1 Bn in 2025 and is forecast to hit US$ 30.9 Bn by 2036 at a 7.4% CAGR, with US, Canadian and Australian processors scaling non-China supply.
Globally, the steel sector in mid-2026 is anchored by integrated producers shipping to automotive, construction and energy supply chains; spec-heavy buyers compare makers on ASTM grade families, mill capacity and traceable documentation.
Verified aluminium industry directory data for June 2026: ScrapMonster lists active aluminium suppliers, OMANYP indexes 260 verified companies in Oman, and the global market continues to segment across primary smelting, extrusions, castings, and downstream window/door and veneer systems.

EV fast-charging station hardware in 2026 splits between 30-360 kW DC fast chargers, 7-22 kW AC Level 2 units, and 350 kW+ high-power charging (HPC) systems, with FUERD Group among the 2026 listed solution providers. Spec priority shifts to OCPP 1.6/2.0.1, CCS2 and NACS connector support, IP54/
Global nuclear capacity is expanding as 2026 trade events surface across Italy, Turkey, and beyond. Top nuclear power companies 2026 span state-owned reactor vendors, fuel-cycle firms, and EPC contractors driving new-build and SMR pipelines worldwide.
The 2026 top additive manufacturing companies cluster into four technology families — metal powder-bed fusion, polymer/FDM, large-format thermoplastic extrusion, and AM software — and the ranking field now spans OEM machine builders, powder makers, software vendors, and service bureaus tracked by So

Global silicon wafer production capacity reached 974.2 GW at end-2023, with Chinese manufacturers holding 97.9% share of new global capacity additions and the top 10 producers controlling 85.5% of installed capacity and 84.8% of output.
The global power generation market in 2026 is segmented across hydroelectricity, fossil-fuel, nuclear, solar, wind, geothermal and biomass sources, with on-grid and off-grid architectures as the two structural splits. Power cable demand — the wire-and-cable slice that physically links generatio
Germany's May 2026 onshore wind tender cleared at 5.06 ct/kWh, South Korea awarded 1.8 GW in H1 offshore wind, and Vena Energy closed a USD 965m facility for Australian solar-plus-storage, signalling capital is still flowing into wind and storage adjacencies.
The global lithium-ion battery market is projected by Statista to surpass USD 400 billion by 2032, up from roughly USD 60 billion in 2023, a compound trajectory reshaping battery-grade lithium demand, supply contracts and cell sourcing for B2B buyers in 2026.
The 2026 server-hardware vendor ranking consolidates around five OEM groups (Dell PowerEdge, HPE ProLiant, Lenovo ThinkSystem, Cisco UCS and Supermicro), with three structural shifts: ARM64 mainstreaming, NVMe-oF fabric adoption, and DC-MHS / OpenBMC disaggregation.
The global CNC machine market is valued at USD 96.85 Bn in 2026 and is projected to reach USD 187.54 Bn by 2033, growing at a 9.9% CAGR, with lathe machines leading segment share. Parallel data places the wider machine vision system market at USD 49.7 Bn (2023) tracking toward USD 159.2 Bn by 2032 a
Global power grid market grows from USD 326.52B (2025) to a projected USD 487.55B by 2031 at 6.91% CAGR (TechSci, 2026-05-21), driven by aging-asset replacement, rising demand, and renewable integration.

Polished monocrystalline silicon wafer spot listings on 2026-06-02 cluster at US$10–100 per piece at 25-piece MOQ from Chinese suppliers, while SEMI's 2015 baseline put global area shipments at 10,434 MSI and reclaimed/reclaim services remain a parallel procurement lane.
State Grid Corporation of China and the State Power Investment Corporation anchor the Asia-Pacific utility landscape into 2026, with grid digitalization, HVDC interconnects, and a 33rd EP Shanghai expo set for 3-5 December 2026 defining procurement timing.
EV traction motor demand is reshaping the global electric motor landscape in 2026, with axial-flux and direct oil-cooled units displacing legacy induction designs; Nidec anchors an EPS brushless cluster in Changzhou while Made-in-China listings expose the $5 to $30,000 industrial-motor spread.
Global electric vehicle (EV) charger market was valued at USD 7.2 billion in 2022, projected to reach USD 91.2 billion by 2032 at a 29.3% CAGR (2023–2032). EV plastics is set to grow from USD 3.9 billion (2025) to USD 45.8 billion by 2035 at 28.0% CAGR, with BEV holding 38.2% share.
Global PCB market is tracking toward USD 85-90 billion in 2026 with mid-single-digit CAGR through 2030, driven by AI server substrates, HDI for smartphones, and EV power modules; multilayer and HDI segments lead by volume, rigid-flex by growth rate.
Cobalt sourcing in 2026 is dominated by DRC Artisanal and large-scale operators plus Indonesian MHP projects, with Glencore, CMOC, Huayou, ERG, and Umicore the recurring names on every credible supply ranking.
China dominates 2026 LED and transparent display panel sourcing, with Made-in-China listings showing 1-piece MOQ at US$ 390-600 for full-color HD video wall panels and RoHS-certified transparent displays from vetted manufacturers.
CNC machine global market is valued at USD 96.85 billion in 2026 with a 9.9% CAGR to 2033 per Coherent Market Insights, while CNC metal cutting machines track a separate USD 53.07B-to-83.36B trajectory at 4.2% CAGR through 2030, framing divergent growth paths for spec-driven buyers.
SourceBySpec's 2026 drone manufacturer map ranks DJI, Skydio, Parrot, Autel and JOUAV by payload class, autonomy stack and certification status, with industrial buyers advised to weight EN 4709, MOC 2511 and DO-308 compliance before price.
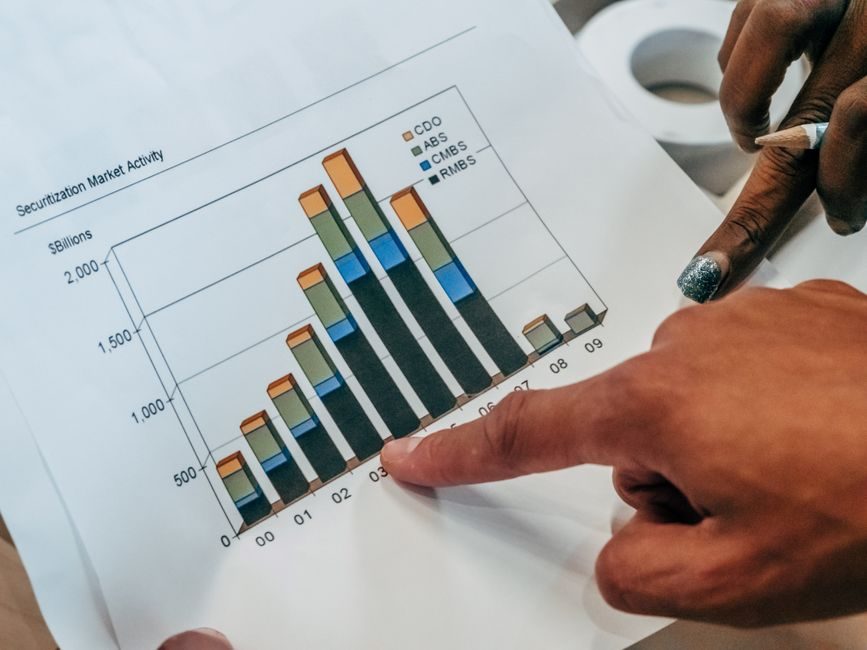
Global data center generators are projected to grow from USD 8.57 B in 2026 to USD 9.79 B by 2031 at a 2.7% CAGR, while edge data centers expand at 20.44% CAGR through 2034, reshaping power and sensor demand for downstream industrial buyers.
Codelco, BHP, Freeport-McMoRan, Glencore, Anglo American and Aurubis head the 2026 copper producer-refiner map; CRU's 13-15 April 2026 Santiago World Copper Conference set the price-floor context.
Global steel plate, coil, pipe and stainless availability in 2026 is being reshaped by Japanese CNC export restrictions driving an 8.3% system-price spike and scrap-supply volatility extending plate lead times across 2026 H1.
Fanuc, Yaskawa, ABB, KUKA and Kawasaki Heavy Industries form the established core of the industrial-robot OEM market, joined by Japanese rivals Epson and Denso and the Chinese cohort Estun, Inovance, Siasun and STEP, with selection pivoting on payload class, repeatability, controller openness and af
Global 3D printing market tracked USD 21.31B in 2025 and projects expansion toward USD 116.96B by 2031 at ~33% CAGR, with industrial printer demand led by DMLS and SLA in aerospace, medical, and automotive tooling.
Connector demand in 2026 is shaped by 5G/AI data-center bandwidth, EV high-voltage powertrains, and miniaturized industrial IoT, with supply chains recalibrated for chemicals, aerospace and process-control OEMs. 2026-07-02.
European Heat Pump Association confirms the Heat Pump Forum & Awards 2026 for 1 December 2026 in Brussels; IGSHPA published its 5th Research Conference proceedings on 5 June 2026; China-sourced industrial CO2 heat pumps now list at US$3,000–37,000 across 60 kW–1800 kW capacity bands.
The global aerospace and defense market is the parent envelope for several 2026-forecasted sub-segments: aerospace 3D printing tracks USD 4.40B (2025) to USD 18B by 2035 at ~15% CAGR, laser processing serving aerospace applications grows from USD 30,862.1M (2026) to USD 62,075.1M by 2033 at 10%
Global PV market is projected to reach USD 968.32 billion by 2030, with SNEC PV+ 2027 (Shanghai, June 2-4, 2027) anchoring the 20th edition of the flagship industry exhibition and IEA PVPS continuing to track deployment trends.
CATL, BYD, LG Energy Solution, EVE Energy, Tianneng, and Green Cubes anchor the 2026 industrial lithium battery supplier map; cell formats split between NMC prismatic for EV and LiFePO4 for ESS/forklift, with pack-level safety covered by UN 38.3, IEC 62619, and UL 1973.
Global petrochemical market tracked at USD 641.01 billion in 2024 with a 7.3% CAGR to USD 973.10 billion by 2030; ethylene, propylene and methanol anchor the product mix while Asia Pacific sets the regional tempo for 2026 capex.
The global intelligent wind turbine market is forecast to reach $25.39 billion by 2026 at a 4.38% CAGR (2021-2026), with offshore turbines driving demand for vibration-resistant, ATEX/IECEx-classified sensors, condition-monitoring retrofits and sub-component standards.
Top 3D printing companies in 2026 cluster around polymer and metal AM systems, materials, and contract manufacturing; the buyer-facing shortlist is shaped by 7,500+ vendor inquiries tracked by MarketsandMarkets and regional operator directories such as Built In Colorado.
No verified 2026 figure for global cobalt market size, supply, or price exists in the editorial feed dated 2026-07-03; coverage is limited to a USD 12.8B coating additives forecast (2026).
Global wind power is being driven by a 2026-06 Düsseldorf blade-manufacturing congress, CE-certified China-supplied micro/utility turbines (US$400-35,000 FOB), and a components market in brisk growth, with leading OEMs defined by capacity, blade length and offshore capability.
Global nuclear electricity market sizing reports published January 2026 put installed-generation value in the multi-hundred-billion USD range, with 2026-2030 CAGRs clustered in the low single digits and a clear shift toward SMR and Gen III+ capacity additions.
Future Market Insights sized the global OLED display market at USD 54.5 billion in 2025 and projects USD 59.2 billion in 2026, a ~8.7% YoY lift. The category splits across TV panels, smartphone AMOLED, automotive HMI and emerging micro-OLED near-eye applications.
Global industrial robotics market valued at USD 23.71 billion in 2024, projected to reach USD 85.63 billion by 2034 at 13.7% CAGR, with 2026 specification pivoting toward collaborative arms and mobile logistics integration.
2026 marks the pivot year of the LNG super-expansion cycle, with ~40.7 Mtpa of new liquefaction capacity arriving; North America and the Middle East reshape the supply map and five majors (Shell, QatarEnergy, ExxonMobil, BP, Cheniere) anchor the upstream league table.
Cobalt supply is being rewired in 2026 by DRC export quotas, Indonesian HPAL ramp, and LFP cathode substitution, with battery-grade nickel-cobalt price floors anchored near $15-22/lb and EV energy-density thresholds keeping NMC chemistry dominant above 250 Wh/kg.
LED fine-pitch P1.95 panels quoted at USD 1,000-1,200/m² MOQ 1 m² on Made-in-China, while automotive HUD demand scales to USD 2.2B in 2026 and IP65 12.2" industrial panel monitors hold a USD 248-285 band on the same trading channel.
Global desalination capacity is on track to exceed 120 million m³/day of installed nominal production by the end of 2026, with seawater reverse osmosis (SWRO) accounting for the majority of new contracted capacity in the Gulf, North Africa, and the Chinese coastal provinces.
Global petrochemicals market valued at USD 641.01 billion in 2024, projected to reach USD 973.10 billion by 2030 at 7.3% CAGR; Asia Pacific holds 46.9% share with China at 35.4%, as 2026 is shaped by oversupply, decarbonization and feedstock restructuring.
Additive manufacturing in 2026 is shifting from prototyping to serial production: Formnext Frankfurt (17-20 Nov 2026), Pratt & Whitney GTF engine repairs, electrification-driven motor demand, and peer-reviewed work in Additive Manufacturing (ISSN 2214-8604) anchor the year's industrial moves.
Global power transformer market is projected to reach USD 45.82 billion by 2033 at a CAGR of ~6.8% from a 2026 base, while the upstream transformer core segment hits USD 13.5 billion by 2030 at 4.3% CAGR. Specification and sourcing decisions now hinge on voltage class, core steel grade, an
Top AI chip companies in 2026 are led by NVIDIA, AMD, Intel, Qualcomm, Broadcom, and a Chinese cluster of Huawei HiSilicon, MediaTek, and Horizon Robotics, with ASIC specialists gaining share.
Datacenters.com lists 1,610 data center, colocation and cloud providers in 2026; the global top tier is led by hyperscalers AWS, Microsoft Azure, Google Cloud, Meta and Oracle, with colocation majors Equinix, Digital Realty, Iron Mountain, NTT DATA and CyrusOne filling the retail/wholesale floor.
Global industrial robotics market is projected to grow from USD 38 billion in 2020 to USD 163 billion by 2032 at a 12.6% CAGR, with parallel segments including warehouse robotics, harmonic drives, vision-guided robotics and electric linear cylinders all expanding on automation demand.
South Korea awarded 1.8 GW in its H1 2026 offshore wind auction on June 30, while Vena Energy closed a USD 965m financing deal in Australia on July 1 — two of the year's strongest project-finance signals for the global offshore wind OEM and developer lineup.
The MEMS sensor supplier landscape in 2026 is dominated by a handful of IDM-style vendors — Broadcom, Bosch, STMicroelectronics, Infineon, Qorvo, NXP, Honeywell, and Murata — competing on wafer scale, automotive-grade qualification, and one-stop module integration rather than on bare-die price alone
Top 2026 EV makers now span China's Zeekr 9X at US$70,000-80,000 list price, North-American fleet players like Columbia, and India cargo-EV specialists such as Etrio, while the global EV market is projected to hit USD 823.75 billion by 2030 from a 2020 base of USD 163.01 billion.
Global desalination system capacity is expanding across thermal and membrane segments through 2026, with seawater reverse osmosis (SWRO) dominating new orders and multi-effect distillation (MED) holding the high-salinity niche.
Global nickel demand is being reshaped in 2026 by stainless-steel consumption, EV battery cathode mix, and nickel-alloy industrial spec growth, with the nickel-alloys segment tracked at a 2024 base of $4.2 B scaling toward 2030.
Chinese lithium battery price tracking for May 2026 shows lithium manganate (LMO) cells at a 2.5-4.2V nominal window, while Q2 2026 wholesale listings on Made-in-China.com show 3.7V LiPo packs for power-bank/UPS at US$1.20-2.00/pc and 100-200kWh HV cabinets at US$1,200-1,384.
The 2026 global lithium leaderboard is still dominated by Albemarle, SQM, Ganfeng, Tianqi and Livent, with battery-grade lithium carbonate spot prices hovering near RMB 70,000-80,000/t on 2026-06-25 after a 12-month correction from the 2022 peak.
U.S. residential solar install pricing sits at roughly $2.59/W in Louisiana as of June 2026, with leading installers including Elevation, Sunrun, Blue Raven, Palmetto and Venture Solar; India's top module makers such as Goldi and Citizen Solar anchor the manufacturing side.
Global heat pump demand is forecast to grow 5.9% CAGR through 2030 on industrial efficiency mandates, with the industrial segment alone adding USD 805.4 million in opportunity and Europe accounting for 34% of regional growth.
Global UAV market sized at USD 30.18 BN in 2025 with 9.2% CAGR to USD 40.56 BN by 2030, while delivery drones hit USD 1,013.7 Mn in 2026 growing 42.9% CAGR to USD 12,335.3 Mn by 2033.

TSMC held the dominant share of the global semiconductor foundry market in Q4 2025, with Samsung in the second slot; Nvidia led the broader semiconductor universe by market cap on 2026-06-03, ahead of Apple, Microsoft, and Alphabet.
The global CPU market sits in a mid-cycle reset in 2026: client and server demand is being re-priced around AI-accelerated SKUs, while legacy x86 and ARM-based general-purpose parts absorb the inventory correction that began in 2024.

Global valves market reaches USD 99.6B in 2025, projected to USD 153.5B by 2036 at 4.0% CAGR; oil & gas, water treatment and smart-actuated flow control lead 2026 demand drivers.
Global connector market sizing for 2026 sits in a fragmented analyst band of roughly USD 80-95 billion baseline, with automotive, telecom/datacom and industrial automation driving 4-7% volume growth and high-speed/high-power segments outpacing the average.
Lithium battery market 2026: cathode materials projected at USD 21.29 B by 2025, energy storage pulling demand, prices rebounding, while chloride trading stays range-bound. Sourcing shifts to non-Chinese brine and chloride routes.
The 2026 industrial connector supplier map spans three tiers: TE Connectivity, Amphenol and Molex at the top, Harting, Phoenix Contact, JST, JAE and Yazaki on the mid-tier, and a long tail of regional mould-and-assembly houses in Shenzhen, Dongguan and Suzhou.
The pneumatic systems market is pivoting hard in 2026: pneumatic conveying is on track for USD 48.36 B by 2030 at 5.8% CAGR, while solenoid-valve architectures, CFM-leak economics, and software-defined factory integration reshape the buying criteria for cylinders, fittings, and tubing.
Global photovoltaic (PV) market tracking converges on a multi-hundred-GW install base by 2026, with rooftop and tracker sub-segments growing double-digit through 2031-2033. Spec-driven procurement now hinges on technology mix, deployment type and geography.

Silicon wafer market demand rebound is visible in 2026 with global revenue tracking back toward 2022 peaks, driven by 300mm logic/foundry wafer area, advanced-node ramps, and HV CMOS/SiC power adjacencies; supply remains concentrated among five wafer makers.
The 2026 ranking of top petrochemical companies is led by US integrated majors ExxonMobil, Chevron and Dow alongside Saudi Aramco and China's Sinopec, with combined downstream capacity above 5 million barrels per day and 2025 capex above 60 billion USD.
Global AI chip market is on track to add USD 154.93 B between 2025 and 2030 at a 24.3% CAGR, while the broader AI market hits USD 601.93 B in 2026 and USD 1,236.47 B by 2030 at 32.9% CAGR.
Global semiconductor and related devices market is on track from a 2022 base of USD 48.9 billion in power devices alone to USD 263.1 billion in foundry revenue by 2034, with seven sub-segments now tracked at the USD 16-200B scale.
Global solar PV installations continued to expand through mid-2026 with residential 13.86 kW systems in Tennessee averaging $43,271 before incentives, 405 W monocrystalline modules dominating retail listings at $37.22 V open-circuit, and floating-PV, portable-PV and solar-vehicle sub-segments all ru
Industrial humanoid robots, warehouse AMRs, and physics-AI simulation stacks are the three robotics segments rewriting capex line items through 2026, with Chinese vendors raising billions in embodied-AI rounds and Western integrators shipping NVIDIA Isaac Sim 5.0 bridges into live cells.
China's machine tool market exceeds RMB 200 billion (~US$27.86B) with steady domestic output growth, but high-end CNC dependence on imports persists; 2026 buying hinges on five-axis, linear-guide, and servo-spec trade-offs.
Global aluminum market tracked at USD 162.0 billion in 2023 with a 5.9% CAGR projection to USD 285.4 billion by 2033, while end-use subsegments (casting, automotive, foil) carry their own 2026 baselines and forecast windows. Buyers should size purchases against processing route, end-user mix and reg

Global power semiconductor market reached $48.9B in 2022 and is projected to hit $79.9B by 2032 at 4.9% CAGR, with 1200V-1350V IGBT modules, SiC/IGBT dual sourcing, and EV traction inverters driving the 2026 demand mix.
Mazak, DMG MORI, TRUMPF, Makino and Okuma anchor the global machine tool top tier through 2026, with 5-axis simultaneous, automation integration and energy-efficiency retrofits driving spec decisions for buyers.
Global CNC machine supply in mid-2026 is split between dedicated job shops (e.g. 160,000 sq ft Noble-X in Wisconsin, 12,000 sq ft Phoenix Companies LLC in Virginia) and high-tech OEM builders like Ningqing Aerospace (35+ years, Nanjing) and LEADCNC (founded 2007, aluminium-profile systems).
Battery energy storage in 2026 is anchored on lithium iron phosphate (LiFePO4) cells with 500 kWh–5 MWh cabinet footprints, copper-aluminium composite busbars and liquid-cooled rack layouts as the dominant hardware spec choices.

Power semiconductor market tracked at USD 48.9 billion in 2022, forecast to reach USD 79.9 billion by 2032 at 4.9% CAGR per Allied Market Research; silicon carbide and gallium nitride are reshaping material mix through 2035.
Crystalline silicon PV modules are now listed on Chinese B2B portals at US$ 0.075–0.12/Wp for 25-year-warranty 144-cell panels, while hybrid solar systems pair 5–12 kVA inverters with 48 V lithium storage. The market is structurally bifurcating: utility-scale on-grid crystalline plus off-grid thin-f