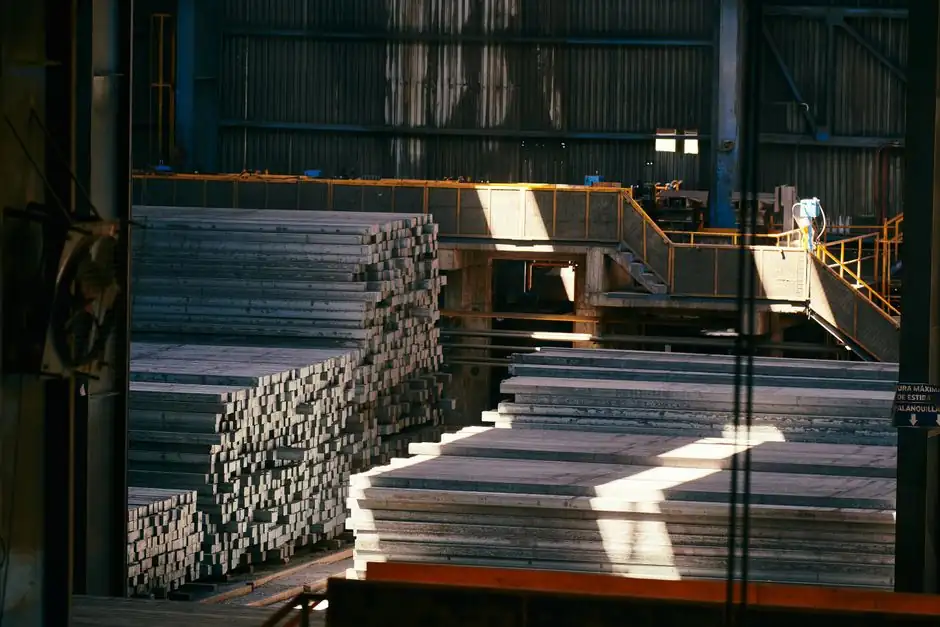
Carbon steel prices were anchored by rising raw-material costs in August 2026, while finished-product prices reached $1,213 per ton for hot-rolled coil and $1,360 per ton for plate in September 2026 [S2][S3].
Scrap is the primary metallic input for electric-arc furnace steelmaking, iron ore is the principal raw material for blast-furnace steelmaking, and neither index alone sets the final carbon steel purchase price [S1][S4].
Scrap and iron ore set different cost floors
Carbon steel scrap is a major input for new steel and cast-iron production, and the US steel industry has recycled scrap for more than 150 years. Remelting scrap requires less energy than producing steel from iron ore, making scrap availability and price central to electric-arc furnace economics [S1].
The producer price index for carbon steel scrap declined from 551.083 in June 2026 to 543.238 in July and 537.551 in August [S3]. That movement shows that a lower scrap index does not automatically produce an equivalent decline in finished carbon steel prices.
Iron ore benchmarks influence the blast-furnace route, but steel pricing also absorbs electricity, electrodes, refractory materials, labor, freight, financing, mill utilization, conversion costs, and regional scarcity. S&P Global therefore separates iron ore, steel products, steel scrap, and metallurgical coal within its ferrous market data framework [S4].
Finished form changes the price per ton
Carbon steel is not one purchasable price. In September 2026, hot-rolled coil averaged $1,213 per ton, cold-rolled steel $1,446 per ton, coated steel $1,551 per ton, and plate $1,360 per ton [S2]. The $338 per ton spread between HRC and coated steel demonstrates why a generic carbon steel quote is unsuitable for budgeting.
Plate represented a $147 per ton premium to HRC in September 2026, while cold-rolled steel carried a $233 per ton premium [S2]. Carbon steel surface finish: hot-rolled versus cold-rolled becomes relevant when comparing these prices because finishing, processing, inspection, and delivery requirements differ.
Mill utilization, inventory, and lead time can outweigh a modest raw-material change. US raw steel production was 1,818,000 net tons for the week ending August 29, 2026, at 78.7% capacity utilization, versus 1,764,000 net tons and 78.2% utilization one year earlier [S2].
Compare the main carbon steel price components
Scrap benchmarks are most relevant to electric-arc furnace material, iron ore benchmarks to blast-furnace material, HRC to uncoiled hot-rolled products, and plate to heavy flat products. The selection question is not simply which raw-material index falls, but whether mill availability and finished-product demand tighten faster. [S1]
On cost exposure, scrap reacts directly to the metallic charge of electric-arc furnaces, while iron ore acts through blast-furnace burden costs. On processing exposure, HRC has less downstream processing than cold-rolled or coated material. On delivery exposure, plate can carry a mill premium, and some mill lead times were already extending into early 2027 as of September 2026 [S2]. On availability, service-center inventories were at their lowest level since 2021 [S2].
The CRU Index supports a cleaner market comparison. It is derived from weekly actual transactions on a free-on-board mill basis using a volume-weighted price, and it is referenced in more than 95% of physical US HRC contracts [S5].
Purchase price and total cost move separately
A buyer should separate raw-material cost from mill conversion cost, product specification, order size, delivery timing, and working capital. The September 2026 Nucor consumer spot price for HRC was $1,185 per ton, $28 below the $1,213 market average, demonstrating that producer pricing and benchmark averages are not interchangeable [S2].
Volume affects the mill offer, but freight, unloading, handling, inspection, and storage can erase an apparent per-ton saving after delivery. A lower benchmark quoted free on board at the mill does not lower the installed cost unless freight and logistics are also favorable. For long-lead plate, early mill allocation can matter more than a small movement in scrap or ore.
Scrap can reduce energy and raw-material demand compared with ore-based production, but this advantage must be evaluated with mill capacity and product availability. A service center buying HRC for fabrication does not capture the full scrap economics unless it can use the available form at the required specification and delivery date [S1].
Use formulas and leading indicators in procurement
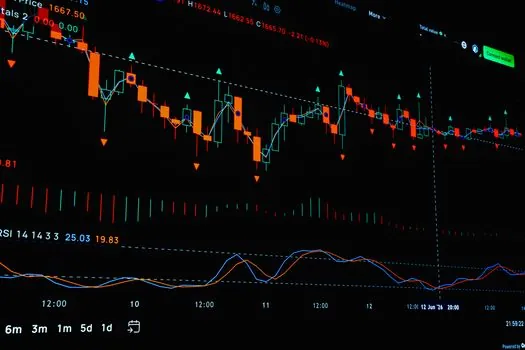
A sound carbon steel budget should track at least four reference points: the carbon steel scrap PPI, iron ore, the applicable finished-steel benchmark, and regional mill or service-center availability. The CRU benchmark is a physical HRC assessment, not a universal carbon steel index, and its mill-basis methodology should be matched to the quoted delivery terms [S5].
Procurement teams should also record the quoted specification, quantity, delivery location, freight basis, payment terms, and validity period. A per-ton price without those fields is not comparable. The same discipline applies when evaluating the carbon steel cost drivers associated with iron ore and scrap rather than relying on a single commodity quote.
For general material background, carbon steel covers the manufacturing context relevant to sheet, plate, and structural product comparisons. Cast iron is a related scrap-consuming material, but its casting economics and product market must not be treated as interchangeable with rolled carbon steel.
Market structure determines the next price move
September 2026 pricing remained supply-driven because service-center inventories were low, spot allocations were constrained, and mills favored contract volumes. Mill utilization reached roughly 80%, compared with 76% one year earlier, while some plate lead times extended into early 2027 [S2].
International benchmarks confirm that regional basis matters. World export HRB was $490 per tonne in the April 2026 price history, while US HRC averaged $1,213 per ton and plate averaged $1,360 per ton in September 2026 [S2][S8]. Freight, tariffs, trade policy, and domestic supply can therefore separate a US price from an export reference by a substantial margin.
On October 23, 2026, the cited steel benchmark stood at 3,051 CNY per metric ton, down 0.16%, while iron ore stood at 90.83 per metric ton, up 0.11% [S6]. The opposing moves in that session illustrate the point: finished steel does not track iron ore one-for-one because scrap, conversion, supply, and product demand remain independent variables.
For the next purchasing decision, record the delivered price alongside the scrap PPI, iron ore assessment, finished-product benchmark, mill lead time, and local availability. A sustained fall in raw-material indexes without improved mill allocation is a weaker buying signal than falling indexes combined with shorter lead times and ample service-center inventory.