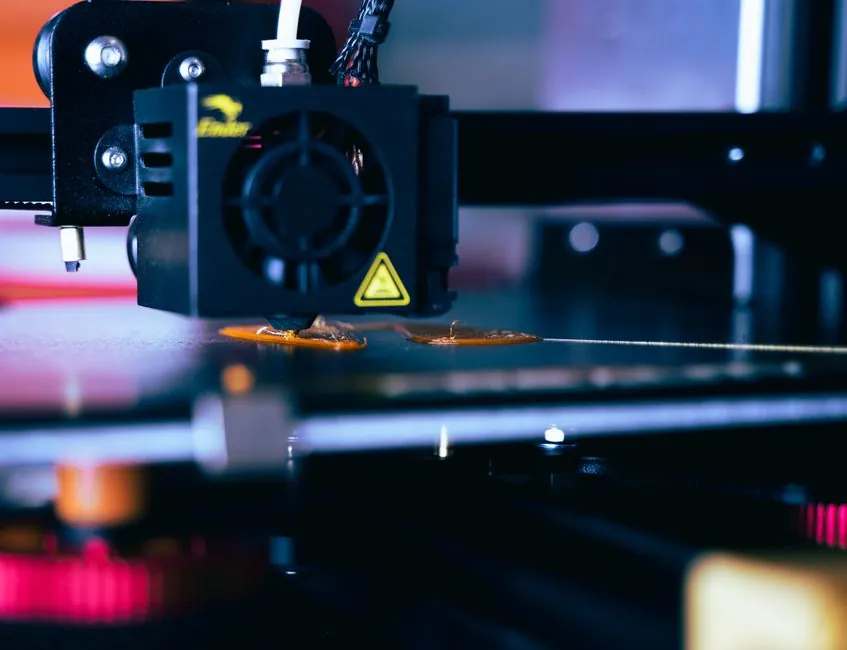
Consumer FDM 3D printing in 2026 is a stratified three-tier market, with the $150-300 budget segment holding 60% of unit sales, the $300-600 speed segment at 30%, and the $600+ professional tier at 10%, per a 23 February 2026 industry landscape audit [S2].
Within those tiers, the structure is sharper than the marketing suggests: Creality anchors the budget tier, Bambu Lab owns the speed narrative with a $299 base unit running 250 mm/s sustained, and Prusa plus Ultimaker hold the professional workflow ecosystem, with the Bambu X1 Plus at $999 proving a $1,000 prosumer price point is viable [S2].
Market Segmentation: Three Tiers, Clear Winners
The $150-300 budget tier is saturated, with prices stabilizing at roughly $229 as the minimum viable price for a reliable FDM printer, below which units technically work but frustrate users [S2]. Creality dominates this band on brand momentum rather than feature innovation, and the analyst forecast calls for only 2-3 major players remaining by 2028 as the field consolidates [S2].
The $300-600 speed tier is the fastest growing band and the one where genuine product differentiation happens. Bambu Lab's A1 line established that users will pay a $100-200 premium above budget pricing for throughput, with sustained print speeds in the 250 mm/s range becoming the new baseline expectation [S2]. Artillery is positioned as the quality alternative here, while Creality is structurally hampered by its budget-brand identity, which makes it hard to credibly re-position upward [S2].
The $600+ professional tier separates prosumer from professional, exemplified by the Prusa MK4S at $599, the Bambu Lab X1 Plus at $999, and the Ultimaker S5 above $3,500. In this band, the purchase decision is no longer driven by hardware specs alone, with workflow integration, cloud services, and support quality acting as the primary differentiators as the hardware itself becomes commoditized [S2].
Technology Plateau: What Has and Has Not Improved Since 2020
FDM print quality at equivalent layer heights has effectively flatlined since 2020, with the 0.2 mm layer height ceiling, the 0.4 mm brass nozzle, and the PLA/PETG/ABS material set all still standard in 2026 [S2]. Budget printer throughput remains in the 100-150 mm/s realistic band, and incremental hardware gains no longer translate to step-change quality improvements [S2].
What HAS changed is reliability, ease of use, thermal management, and speed on premium machines. Automated bed leveling is now standard across most new units, enclosed chambers are common above $400, and Bambu's premium models are pushing 350 mm/s sustained throughput [S2]. For buyers, the practical consequence is that 2020 hardware is largely equivalent to 2026 hardware on output quality, which makes the used market a rational option for cost-sensitive buyers [S2].
The plateau also reframes competition. Once stringing, bed adhesion, and thermal consistency are solved at the firmware and mechanics level, the next gains require fundamental changes such as new extrusion systems, new polymer chemistry, or redesigned motion platforms, and those arrive on multi-year cycles [S2]. For a process engineer, that means specifying a printer is now more about firmware maturity and service network than about headline spec sheets.
AI, Multi-Material, and Sustainability: The 2026 Differentiators
Speed, AI-driven design, multi-material capability, and sustainable materials are the four vectors defining the 2026 product roadmap, per a 1 March 2026 industry mega-guide [S1]. High-speed firmware paired with vibration compensation is now treated as a baseline expectation rather than a premium feature, and the guide flags AI-enhanced slicers that can predict print failures before they occur as one of the more significant workflow gains of the year [S1].
Multi-material and full-color printing has moved from boutique to mainstream, with systems that combine soft and rigid polymers, multiple colors, and varied finishes in a single build now affordable and reliable enough for intermediate users, not just labs [S1]. The practical consequence is lighter, stronger functional parts in a single operation, which closes the gap with injection molding for low-volume production.
Sustainability is being marketed as a core industry priority, with eco-friendly materials and greener production methods promoted across vendor channels in 2026 [S1]. Buyers should treat those claims as a procurement filter, not a substitute for mechanical property data, since PLA, PETG, ABS, and TPU remain the workhorse materials with Nylon still niche due to printing difficulty [S2].
Filament QA: The Real Battleground as Hardware Plateaus
With FDM hardware largely commoditized, filament quality has emerged as the meaningful variable in 2026. A 13 March 2026 empirical comparison benchmarked Numakers, Prusament, Polymaker, and SigmaFilament PLA and PETG across laser micrometry, tensile testing, and impact testing, treating dimensional accuracy, high-speed printability, and mechanical strength as the three decision criteria [S3].
Dimensional accuracy is the primary lever for high-speed print reliability, because tight diameter tolerance directly affects extrusion consistency on CoreXY machines that are tuned for premium throughput [S3]. Material purity correlates with mechanical strength, so batch-to-batch consistency matters more than nominal spec sheets for any project where the part will see load [S3]. The economic equation is that the true cost of a cheap filament includes the cost of failed prints, which is why a $5 savings on a spool can turn into a $50 loss once a 12-hour build is scrapped.
For buyers, the takeaway is that filament selection should be matched to the printer kinematics. A spool that runs flawlessly on a slow bed-slinging machine may fail on a high-speed CoreXY, which is why the same study recommends empirical testing against the specific motion system rather than relying on brand reputation alone [S3].
Industrial Crossover: Where Consumer 3D Printing Stops and Process Control Begins
Consumer 3D printing's 2026 trajectory has direct implications for industrial specifiers, because the same AI slicer logic, vibration compensation firmware, and multi-material heads that show up in prosumer units also feed into factory floor additive cells. Engineers sourcing flow meters, pressure transmitters, and PLCs for plants that host 3D printing workcells should expect tighter integration between the printer's monitoring stack and the plant's industrial Ethernet layer, which is itself consolidating around specific protocols and cabling specs in 2026 [S2].
For buyers evaluating printers in the $600+ tier, the procurement question has shifted from "what is the print speed?" to "what is the cloud API, what is the service contract, and does the vendor publish MTBF data?" Hardware is no longer the bottleneck, with the 0.4 mm nozzle and 0.2 mm layer ceiling both still standard, and the industrial valve and pressure sensor supply chains that feed process instrumentation follow a similar commoditization curve on the hardware side, with software and support as the live differentiators [S2].
Consolidation Forecast and What to Track Next
Two signals are trackable through 2027. First, the budget tier is forecast to consolidate to 2-3 major players by 2028, with Ender 3 variants persisting on brand loyalty and Anycubic growing regionally in Asia while other entrants fade [S2]. Second, the professional tier is forecast to grow as small businesses adopt 3D printing, with software and cloud services becoming the primary value proposition as hardware commoditizes, and support quality becoming the differentiator [S2].
A third trackable signal is Bambu Lab's international expansion, which is currently Asia-heavy per the 2026 landscape audit and will reshape the speed tier if the brand reaches the same distribution density in Europe and North America that Creality already holds in the budget tier [S2]. For an industrial buyer, the practical procurement plan is to standardize on one printer platform across a workcell, lock in a filament QA protocol, and treat the slicer and cloud API as the long-term service contract rather than the printer frame.
Background reading: GPU Demand 2026-2030: Data Center Acceleration Outpaces the Rest.