Global steel demand is projected to rise 0.4% to 1.8 billion metric tonnes in 2026, providing a firm demand foundation for manganese ore as constrained seaborne availability tightened the market in the first quarter [S8][S2].
Manganese ore prices reached a 2025 high of US$4.48 per metric ton, while the global manganese price averaged US$1,869 per tonne in Q1 2026 and US$1,903 in Q2 2026 [S4][S6].
Steel demand is the primary transmission mechanism
Steelmaking represents nearly 90% of global manganese consumption, so changes in crude steel output, finished-steel consumption and blast-furnace utilization directly affect demand for manganese ore and its principal alloys, ferromanganese and silicomanganese [S2].
The 2026 demand baseline follows an estimated 2.6% contraction in global steel output during 2025. A projected 0.4% increase to 1.8 billion metric tonnes in 2026 is modest, but its directional effect matters because ore buyers must also absorb restricted seaborne supply, higher freight costs and supply-chain disruption [S8][S2].
India illustrates the link more clearly. India’s steel consumption reached 14.4 million tonnes in September 2026 [S3].
India’s manganese ore prices increased by 2.6% in September 2026, supported by stronger steel consumption and sustained demand from ferroalloy manufacturers [S3].
Supply constraints magnify the steel-demand effect
Steel demand is necessary but not sufficient to explain the 2026 price move. Tightening global supply, resilient steel production and firm ferroalloy demand pushed manganese ore prices upward during Q1 2026, while limited seaborne availability drove the strongest gains in Asia-Pacific [S2].
Asia-Pacific recorded the strongest regional gains in Q1 2026 due to limited seaborne availability [S2]. Asian-Pacific pricing was supported by limited availability, while North American and European assessments also firmed as steel production remained healthy and imports faced restrictions [S2].
The supply side includes disruption-specific risks. Cyclone damage at South32’s GEMCO mine and labor unrest in Gabon tightened ore availability and encouraged Western buyers to secure long-term contracts. Alloys accounted for 67.75% of the manganese market in 2025, and the overall market was forecast to grow at a 4.21% CAGR from 2026 to 2031 [S5].
Grade availability therefore matters as much as the headline tonnage. A steel mill can face adequate manganese units but still pay a premium for ore with the required composition, particle characteristics or impurities profile.
Price benchmarks differ by scope and unit
The quoted manganese prices are not directly interchangeable. The global manganese benchmark averaged US$1,869 per tonne in Q1 2026 and US$1,903 in Q2, a 1.8% quarterly increase, whereas the Chinese port assessment was approximately US$187.33 per metric ton and rose 22.98% quarter over quarter [S6][S2].
The unit distinction is critical for procurement analysis.
Procurement comparisons should therefore fix four variables before ranking a price: physical tonne versus contained-manganese unit, ore grade, freight and insurance terms, and delivery basis. Mixing a US$190 per physical tonne port assessment with a US$4–5 per manganese-content unit creates a false price comparison.
Steel output alone does not set ore prices
Four intermediate variables separate steel demand from the ore transaction: ferroalloy operating rates, raw-material inventories, ore quality and competing supply. These factors determine how much additional steel production becomes incremental manganese demand rather than a drawdown of alloy-maker stocks [S3].
MOIL’s manganese ore production reached 181,000 tonnes in September 2026, up 19% year on year from 152,000 tonnes, while sales increased by 15.5% to 164,000 tonnes from 142,000 tonnes a year earlier [S3].
Cumulative April-to-September FY2026–27 production reached 961,000 tonnes, up approximately 1.8% from 944,000 tonnes in the corresponding period of the previous financial year, while sales rose approximately 9.6% to 778,000 tonnes from 710,000 tonnes [S3]. September production exceeded sales by 17,000 tonnes, but that difference alone cannot establish an inventory build without opening-stock and other movement data.
India’s manganese ore prices increased by 2.6% in September 2026 despite improved domestic mining activity, alongside higher steel-sector purchasing requirements and sustained demand from ferroalloy manufacturers [S3].
Cost drivers extend beyond the ore invoice
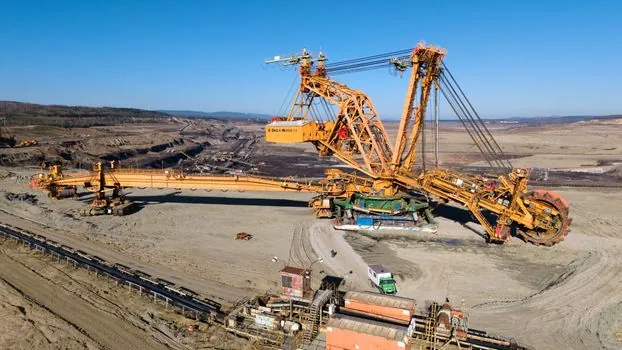
The largest price drivers in 2026 were ore availability, grade scarcity, steel-linked purchasing, seaborne freight, mine operating costs and inventory replenishment. Limited cargo availability raised export offers, while higher logistics expenses and rising mining costs reinforced the landed-price increase [S2].
Long-term contracting adds a cost dimension rather than merely reducing unit volatility. Buyers faced price, quantity, quality and delivery commitments, so a lower spot quotation did not necessarily produce a lower total cost when the supplier could offer dependable seaborne cargoes, consistent grade and fewer emergency freight premiums [S5].
Total cost of ownership for steelmakers includes ore procurement, ferroalloy conversion, freight, insurance, inventory financing, yield loss and the cost of interrupted melts. A mill that substitutes lower-grade or off-spec ore may preserve furnace continuity but raise conversion losses; a mill that secures high-grade ore on a contract may pay more upfront but reduce alloy consumption and process instability [S1][S3].
MOIL raised official prices across all manganese ore grades by 5% for October 2026 deliveries, while higher domestic production and improved availability created a countervailing risk that further price increases could be limited [S3]. That is the core procurement tension: steel demand supports the market, but expanding supply determines how much of that demand reaches the ore price.
Steelmakers are the main users, batteries are the secondary market
Steelmaking is the appropriate market for anyone forecasting manganese ore tied to construction, automotive, infrastructure and heavy engineering. These sectors support blast-furnace steel production and therefore demand for manganese alloys used to improve strength and wear resistance [S2].
High-purity manganese, manganese sulfate and other battery materials create a separate demand pool. The broader manganese market was valued at US$32.26 billion in 2025 and is expected to reach US$33.62 billion in 2026, with alloys accounting for 67.75% of the 2025 market [S5].
Battery demand is structurally relevant but too small and qualification-dependent to replace the steel cycle in a short-term ore forecast. Lithium-manganese-iron-phosphate cathodes can use more manganese than lithium iron phosphate, but battery projects require chemical purity, traceability and contracted production. These requirements make battery-grade supply more segmented than standard metallurgical ore [S5].
For buyers, the decision is therefore clear: use steel production, finished-steel consumption and ferroalloy operating rates as the primary demand signals, then adjust for ore grade, inventory, freight and supply disruption. The manganese market outlook is more relevant to structural battery-manganese expansion than to spot ore purchasing tied to steel mills.
Signals that can change the 2026 price balance
Four trackable variables can confirm or weaken the link between steel demand and manganese ore prices: monthly finished-steel consumption, ferroalloy output, seaborne cargo availability and port inventory. India’s 14.4 million tonnes of September finished-steel consumption, 2.6% monthly ore-price increase and 19% year-on-year rise in domestic ore production provide a useful monitoring template [S3].
China remains the pivotal market because Asia-Pacific represented 54.20% of global manganese demand in 2025. Chinese steel utilization, port stocks and import tenders therefore carry more weight than an isolated producer-country price change [S5][S2].
The near-term balance is supported but not guaranteed: projected global steel demand growth of 0.4% to 1.8 billion tonnes, Indian finished-steel growth of 8% in September and tight seaborne availability point upward, while higher Indian mine production and expanded supply from established exporters create room for prices to soften if purchasing fails to absorb additional material [S8][S3][S2].
Procurement teams should avoid treating one index or one country’s steel statistic as a standalone price forecast. The defensible process is to combine steel output with ferroalloy operating rates, contained-manganese unit prices, grade-specific cargo availability, freight and inventory. That chain captures the real transmission from construction and manufacturing activity to manganese ore cost.