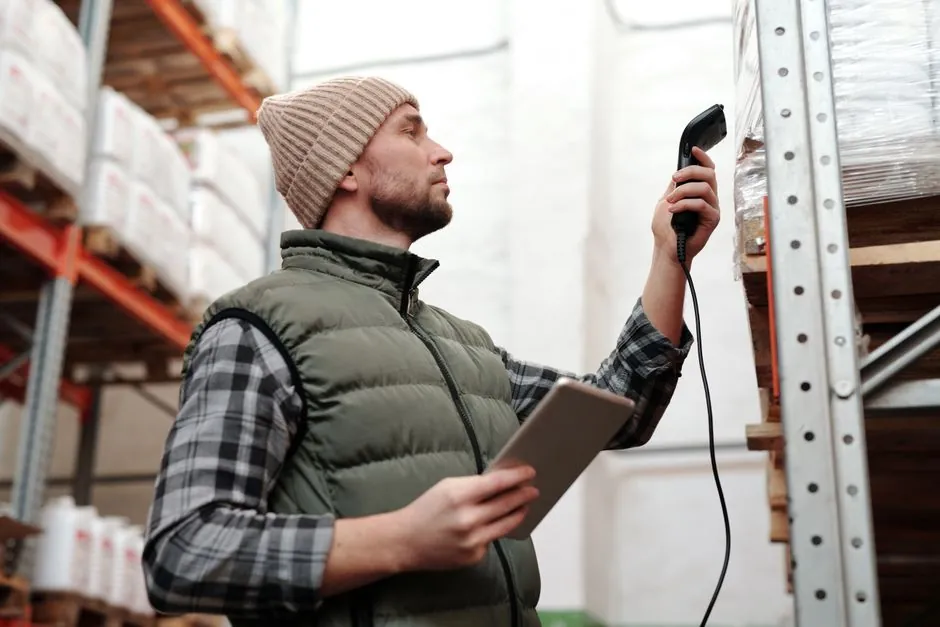
Across 10 detailed retailer case studies, RFID lifted item-level inventory accuracy from a 65-75% starting point to a 93-99% steady state, with the gain tied directly to tag coverage, reader density, and process redesign rather than the radio link alone [S2].
The business case hinges on what that accuracy buys: fewer cancelled online orders, leaner safety stock, shorter cycle counts, and lower shrinkage, all of which are the financial levers the RFID programme has to move before tag and infrastructure cost are recovered [S2][S3].
What the accuracy numbers actually mean
The 65% figure quoted for barcode and manual counting is the industry-average reference point used by RFID vendors, and it sets the floor against which the 93-99% RFID range is measured [S3]. ECR Loss Prevention's 10-retailer study reports the same accuracy band after RFID rollout, but stresses that the post-RFID number is a function of process change, not a guaranteed outcome of the technology [S2].
For apparel, footwear, and general merchandise where every item carries a tag, the upper end of that range is achievable with fixed overhead readers plus handheld sweep units; for case-level or pallet-level tagging, accuracy gains compress because the SKU is identified at the carton, not the piece, and inner-unit errors stay invisible to the reader [S3]. A robust business case therefore separates item-level from case-level coverage and prices the two tiers separately.
Cost drivers that move the price
Tag unit cost is the single largest line item and the most elastic: passive UHF inlay tags in volume sit in the low single-digit cents to roughly 10-15 cents each, while higher-function tags with sensor, tamper-evident, or hard-case features climb into the 0.50-2.00 USD band and dominate per-asset use cases such as tool tracking [S6]. Reader and antenna infrastructure scales with coverage area: a typical retail back-of-house and sales-floor portal deployment uses 4-12 antennas per zone, while a warehouse with dock-door portals may need 20-40 antennas per site [S1][S4].
Software and integration is the most under-estimated line. Middleware that cleans raw RFID reads, deduplicates tag reads, and reconciles them with the WMS or ERP is where most overruns happen, and where the 93-99% accuracy number is actually earned; without it, raw read rates of 95-99% still produce usable inventory accuracy in the 80s [S2][S3]. Tag application labour, either at source or in-store, is the second hidden line and often matches the tag hardware cost over a multi-year horizon for retailers tagging at the item.
When the cost case closes fast
Retailers with high SKU counts, high unit value, and a measurable rate of cancelled online orders typically see payback inside two to three years, because the operational savings (reduced safety stock, fewer markdowns, lower shrinkage, faster cycle counts) compound across millions of tagged units [S2][S5]. River Island's documented ten-year RFID programme is the cited example of how stock confidence changes buying behaviour: the retailer reportedly shifts replenishment and markdown decisions once the record can be trusted at item level [S2].
For an industrial tool-tracking or asset-tracking deployment, the cost case flips: tag unit cost is higher, SKU count is lower, and the savings are concentrated in lost-tool replacement and audit labour, so payback horizons stretch and ROI depends heavily on the cost of a single lost tool versus the recurring tag-plus-reader spend [S6]. See how a similar cost-stack logic plays out in air impact wrench pricing, where the drive size and torque class dominate the per-unit bill in a comparable way.
When RFID is the wrong tool
For low-SKU, high-throughput bulk operations where case-level visibility is sufficient, passive UHF RFID adds cost without lifting the metric that matters (load confirmation, dock-door throughput), and a barcode plus WMS workflow can match the operational outcome at a fraction of the per-unit cost [S1][S4]. Metallic or liquid-dense environments also erode read reliability unless tuned tags and high-performance antennas are specified, which pushes per-tag and per-reader cost up before any accuracy gain appears [S4].
For pilots under roughly 50,000 tagged items per year, the fixed software and integration overhead rarely amortises against tag savings alone, and the verdict is usually to defer or to rent the capability through a managed tagging service rather than capitalise it. A parallel pattern shows up in nickel and chromium surcharges stretching alloy steel lead times past 7 months: the headline per-unit cost is the easy number, the real exposure sits in schedule and integration risk.
Total cost of ownership: the line the business case misses
True TCO splits into four buckets: tag consumables, infrastructure (readers, antennas, cabling, PoE switches), software and integration (middleware, WMS hooks, label printers, applicators), and ongoing operations (tag application labour, read-rate tuning, hardware maintenance, tag replacement on damaged goods) [S2][S4][S6]. A defensible RFID business case writes each bucket out for a five-year horizon and links each to a measurable operational lever, not to the technology itself [S2].
Energy draw of a fixed RFID infrastructure is small relative to the rest of the stack (a portal reader typically runs 5-15 W), so it does not move the case the way it does for, say, a glass fiber roving line; the real TCO swing is in the tag-application labour line and in the read-rate tuning work that has to happen every time the store or warehouse layout changes. A useful benchmark: many retail RFID programmes report a five-year TCO per tagged item of 0.10-0.30 USD, of which roughly half is tags and half is everything else.
Comparison: RFID vs barcode vs manual count on the four criteria that decide it
On inventory accuracy, barcode and manual counting cluster around 65% industry-average, RFID item-level reaches 93-99% in deployed retail case studies, and case-level RFID sits between the two, typically 85-92% depending on inner-pack error rate [S2][S3]. On read speed, RFID reads 100-1,000 tags per second in a portal sweep versus single-item line-of-sight scans for barcode, which collapses cycle counts from days to hours [S1][S3]. On unit cost, barcode labels are fractions of a cent, passive UHF RFID inlays in volume are low single-digit cents to 10-15 cents, and rugged or sensor tags are 0.50-2.00 USD, so the price premium is 10-100x before any infrastructure is counted [S3][S6]. On infrastructure, barcode needs no fixed hardware, RFID needs a portal or handheld fleet plus middleware, which is the bulk of capex for a small deployment [S1][S4].
Process and data integration: the part vendors under-quote
An RFID read event is raw data, not an inventory record: duplicate reads, stray reads from adjacent zones, and missed reads all have to be filtered before the WMS treats the result as a true stock movement, and that middleware layer is where 93-99% accuracy is actually produced [S2][S3]. Without it, the system reports a high read rate but a low usable accuracy, and the business case quietly fails on the operational lever it was sold on.
Where the gain does appear, the broader plant context is converging: headcount is holding while skill mix tilts toward data and integration work, a pattern tracked in Industry 4.0 plant roles, and the same logic shows up in VLM tray height optimisation, where the right data window, not more lifting, is what unlocks throughput. RFID follows the same rule: the winning case is the one where the data window is the bottleneck, not the scan rate.
Signals to track over the next 12 months
ECR Loss Prevention's analysis of 25 major retail case studies is a reference dataset that retailers can benchmark against when building an RFID business case [S2]. Tag unit cost in the 5-10 cent band is the second signal: any sustained drop below 5 cents at volume materially shifts the crossover point where RFID beats barcode-plus-WMS on a per-SKU-per-year basis, and the chip-and-inlay supply chain (Impinj, Alien, NXP silicon) is the place to watch for that move [S1][S6].
Spec-level background on the components involved: pressure transmitter, flow meter, and industrial valve.