
IEC 62443 vs NIST CSF vs ISO 27001 for Plants
For plants, use NIST CSF 2.0 for governance, IEC 62443 for engineering and assurance, and ISO/IEC 27001 for certified ISMS management.
Read →Industry News · Category
For plants, use NIST CSF 2.0 for governance, IEC 62443 for engineering and assurance, and ISO/IEC 27001 for certified ISMS management.
Read →
Use IEC 61511 to engineer the safety instrumented system, and IEC 62443 to secure its OT environment. Integrate both lifecycles through shared risk, requirements, verification, and assurance.
IEC 62443 security levels range from SL1 for accidental misuse to SL4 for sophisticated, well-resourced attacks.
SIL verification under IEC 61511 confirms that each safety instrumented function meets its target PFDavg, architectural and systematic-capability requirements using failure-rate data.
Device makers own product-level IEC 61508 evidence, while integrators own application design and the system safety case.
IEC 61499 separates portable control logic from vendor-specific runtimes, but execution equivalence requires formal verification and compliance profiles.
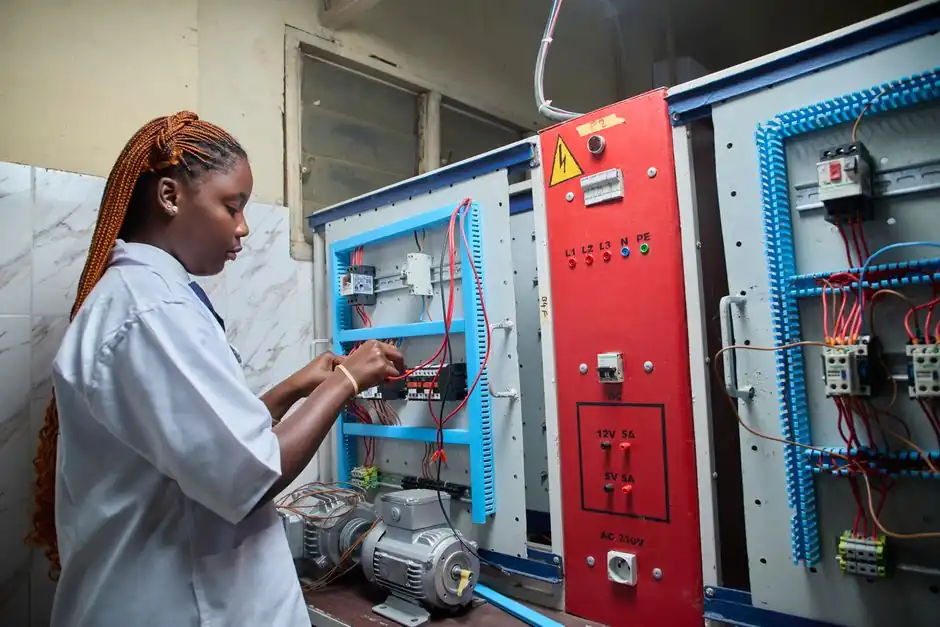
IEC 61439 applies to low-voltage assemblies up to 1,000 V AC or 1,500 V DC, with Part 3 covering distribution boards operated by ordinary persons.
Use IEC 61131-3 for established scan-based PLC control; choose IEC 61499 when event-driven, distributed function blocks and runtime reconfiguration are core requirements.
Choose Ladder Diagram for readable discrete control and Structured Text for calculations, loops, arrays, and data handling within one IEC 61131-3 project.
Industrial standby losses can reach 15–25% of plant energy, while an idle injection molder may draw 40–60% of full-load power. Meter by circuit before controls change.
Ideal cycle time is the sustained benchmark for producing one good part. In OEE, it directly scales performance and can materially change the reported effectiveness of a line.
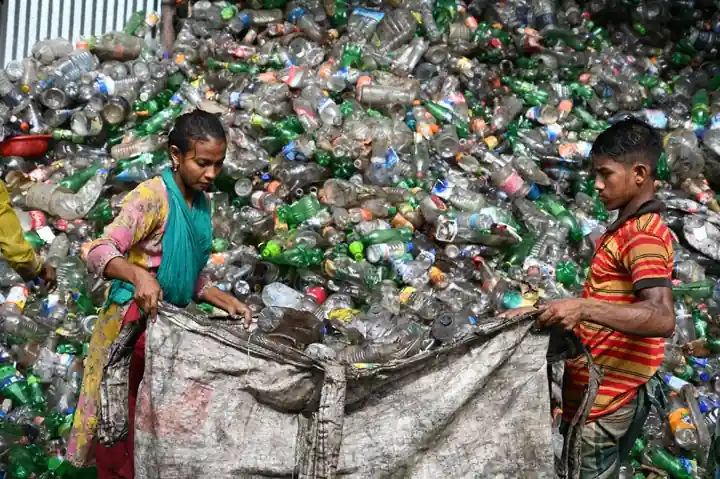
Hyperspectral imaging identifies food and plastic by spectral signature, supporting automated sorting where color or standard NIR is insufficient.
Hybrid digital twins combine physics-based simulation with machine learning to improve prediction, maintenance, and control, but data quality, model coupling, and validation determine deployment success.
Cleanroom HVAC energy can fall 10%–25% through verified air-change reduction, heat recovery, and adaptive control while preserving contamination control.
Validate a vision gauge with bias testing, a crossed Gage R&R study, and predefined acceptance limits before production release.
Validate a predictive maintenance model with precision, recall, lead time, false positives, missed failures, and closed work-order outcomes, not accuracy alone.
Retrain a vision model after verified product or process changes cause measured drift, then validate a candidate against the deployed model before release.
Patch live PLCs through controlled runtime changes, offline validation, redundancy, and staged cutovers, not emergency reboots or untested firmware updates.
Measure predictive maintenance ROI as net verified benefits divided by program cost, with 12 months of baseline data and conservative payback testing.
Measure machine utilization without an MES using CNC controller data, production logs, cycle counts, and operator timestamps, with a defined time denominator.
Connect each validated condition alert to a CMMS work order containing asset ID, severity, sensor readings, diagnosis, procedures, parts, and ownership.
A USB-to-Ethernet adapter adds an RJ45 port to a legacy machine, preserving a wired link through Cat5e or Cat6 cabling and avoiding wireless bridges.

Calculate inspection resolution as pixels per millimeter by dividing pixel count by a known physical distance, then invert it for millimeters per pixel.

Calculate a safety function’s PL in two stages: determine the required PL from the ISO 13849-1 risk graph, then verify the achieved PL from design parameters.
Achieve full product genealogy by capturing lot consumption, production events, quality records, and signatures at each step, then linking them bidirectionally.
Exclude scheduled non-production time from OEE, but count planned changeovers and maintenance against planned production time.
Set vibration-data collection frequency according to the progression of relevant failure modes and the equipment and circumstances, with more frequent collection where needed.
Safety function proof tests typically run every 1 to 5 years, with functional checks monthly or quarterly. Set each interval from design, failure data, service conditions, diagnostics, and applicable recommendations.
Choose the sampling frequency based on how much and how often data need to be collected.
Digital work instructions can reduce training time, simplify documentation, and reduce errors.
Virtual commissioning can cut PLC commissioning time by 40–75%, while published examples reduce on-site startup from eight weeks to four days.
A plant sensor can generate 500 GB per day, equivalent to 182.5 TB per year before replication, backup, and metadata. Actual storage depends on sample rate, payload, retention, and analytics design.
Cybersecurity spending among organizations with fewer than 100 employees ranges from $8,500 to $78,000 annually, with significant variation by industry and region.

For financial forecasting, use at least 12 months of data to capture a full annual cycle, with 24 months helping distinguish one-time events from recurring patterns and 36 or more months revealing multi-year cycles and robust trends.
In food plants, switching from manual tracking to automated measurement typically causes the reported OEE to drop by 15–25 points because the automated system captures losses the manual process misses.
Plan for 12–18 months of operational data and multiple labeled failures, then validate against held-out events before deployment.
Lowering compressed-air pressure by 1 bar can cut compressor power consumption by roughly 4–8%, depending on the system and operating conditions.

Leaks can sometimes waste 20–30% of a compressor’s output, and the annual cost for a 1/4-inch leak is $8,382 based on an electricity rate of $0.05 per kWh and constant operation.
Advanced process control can contribute to energy conservation by optimizing continuous-process operations.
A modeled 16,000 m³ battery dry room required about 400 kW, while clean and dry rooms can account for 26%–53% of plant energy use.

Poor quality typically costs manufacturers 15% to 20% of sales, though broader estimates range from 5% to 30% of gross sales.
Unplanned downtime costs manufacturers an average of $260,000 per hour across all sectors, while automotive plants face costs exceeding $2.3 million per hour.
OEE monitoring offerings range from $30–$100 per machine monthly for entry clip-on sensors and $50–$150 per machine monthly for mid-market sensor platforms, while dedicated OEE SaaS commonly costs $500–$5,000 per line annually, making total cost more useful than list price.
Brownfield plant laser scanning usually costs $10,000–$100,000+, while scan-to-CAD and scan-to-BIM are separate model-creation charges.

Manufacturing data costs about $0.00099–$0.023 per GB-month before retrieval, transfer, replication, and API charges.
Plan for IEC 62443 certification as scoped engineering, readiness work, audit fees, remediation, and training, not a single universal price.
MES systems cost from €850 per month at SYMESTIC, including the platform plus five machines and billed annually, to over $250,000 upfront for on-premise deployments, depending on architecture.
Plan about $200–$800 per wireless sensor point, plus shared gateway, software and installation costs. Budget roughly $300–$1,200 per machine for typical coverage.
A typical digital twin pilot for a single production line costs $200,000–$500,000, while enterprise multi-site product-twin deployments cost $250,000–$500,000 or more.
A 2026 machine vision inspection station typically costs $30,000–$200,000 fully deployed, while entry-level checks start near $3,000.

CMMS software typically costs $20–$150 per user per month, while per-asset plans can reach $5 per asset monthly.
A basic Industry 4.0 upgrade for a 50-machine shop typically costs €75,000–€300,000, covering connected sensors, networking, monitoring, and dashboards.
Industrial automation system integrators typically charge $100–$200 per hour in North America, with specialized programming and field service reaching $222–$292 per hour.

Real-time vision inspection needs compute sized by workload, not camera count: a 100 units/minute line requires sub-100 ms end-to-end latency, while 300+ fps cameras demand fast data transfer.

Design a smart plant network for measured peak traffic, 30–40% headroom, deterministic latency and secure segmentation, not a single headline speed.

A PLC OPC UA server can handle 3 to 100 clients depending on the platform, but subscriptions and CPU load determine practical capacity.

Automate metal post-processing when manual support removal, finishing, and inspection exceed 30–70% of part cost and lead time.

A plant manager should review 3-5 daily KPIs initially, or 5-7 on a daily management board, with every metric tied to an action and owner.
A typical MES needs 3–8 production-critical integrations, but the defensible range depends on equipment, ERP, quality, and traceability needs.
A CNC cell can run unattended for 8 hours, overnight, or 30 days; the practical limit is process reliability, automated handling, monitoring, and fire protection.
Accept no universal false-alarm rate: target below 15% initially, then 5–10% for a mature program, with critical assets held to stricter thresholds.
Use 5–8 top-level reason categories and keep 15–20 choices visible per level, with deeper root causes added after the event.
Start with 50–100 images, then scale toward 30–100 real defect examples per class for a proof of concept and 100–500+ for production.
A multi-plant analytics program typically needs 4–8 data engineers: 1 platform lead, 2–3 pipeline engineers, 1–2 data quality engineers, and 1–2 modeling or ML-data engineers.

NFPA 79 (North America) and IEC 60204-1 (Europe) both govern electrical equipment of industrial machines, but diverge on North American-only Type MTW conductor rules, AHJ/UL listing paths, operator-interface color codes, and protective-bonding thresholds, so a single design must satisfy two parallel
For steady-state operation, use fewer than 6 alarms per operator-hour as the working target; 12 per hour is the practical upper limit.
Size an AMR fleet from workload, not a fixed robot-per-line rule. A line-side system commonly needs two delivery units plus one container position for each resupply cycle.
Keep raw sensor data for 7–30 days for troubleshooting, then downsample into minute, hourly, and daily layers while preserving full-resolution records for critical events.
A mid-size plant typically reaches predictive-maintenance payback in 8–14 months, with deployment economics determining whether results arrive sooner or later.
A useful manufacturing-line digital twin takes 3–6 months for basic machinery, while pilot-to-plant rollout commonly spans 9–12 months.
An MES implementation usually takes 6–24 months, with 12–24 months common for a traditional multi-system deployment. Plan around scope, integration, validation, training, and rollout.
A prepared manufacturer can restore critical operations in days, while an unprepared plant may face three weeks or more than one month of disruption.
A battery cell line typically needs 3–9 months to develop, while production-line installation and commissioning can take 3–6 months. Yield reaches production viability at 70–80%.
Wireless vibration sensor batteries can last 1 to 5 years, but duty cycle, temperature, radio retries, and sample length determine real service life.
Industrial PCs can support 10-year-plus equipment lifecycles, but forced redesigns begin when CPUs, storage, firmware, and software support end earlier than the machine.
VR trains hazardous-process operators on plant-specific tasks, emergency response, and abnormal conditions in a controlled digital environment, reducing live-asset exposure.
Computer vision monitors workers by detecting PPE violations, falls, unsafe behavior, restricted-zone entry, and vehicle conflicts from camera feeds.
A two-shift machine shop can expect a CNC machine-tending cobot to pay back in 6–8 months when deployed costs and added output are modeled correctly.
IE4 and IE5 motor upgrades typically repay their premium in 6 to 36 months on continuous-duty drives, with 8,000 annual operating hours shortening the return.
Process plants can reduce onsite operators substantially through remote monitoring, but the defensible limit depends on automation, connectivity, staffing, and site-specific risk.
RCM sets task intervals from failure behavior, consequences, and task effectiveness, not from a universal calendar rule. It combines MTBF, P-F timing, economics, and field data.
Reinforcement learning optimizes process control by learning action policies that maximize cumulative reward from measured states, rewards, and process outcomes.
Real-time SPC detects process drift during production, while end-of-shift reports analyze completed data, making intervention hours or shifts earlier.
Real-time production data turns daily meetings from retrospective report-outs into focused exception reviews, with alerts, ownership, and faster corrective action.
OEE converts rated capacity into realistic effective capacity: multiply available hours by availability, performance, and quality before committing production schedules.
Mobile maintenance software raises technician productivity by shortening response time, removing paper entry, and giving field teams 24/7 access to work orders, histories, parts, and procedures.
ISA-95 maps enterprise assets through seven levels, from company and site to area, process cell, unit, equipment module and control module, within Levels 0–4.
An MES manages rework and repair as controlled loops, routing failed units through repair, retest, disposition, and traceability while recording every iteration.
Transformer manufacturing combines core preparation, winding, insulation processing, assembly and testing. These are design-specific work packages, not a universal five-step recipe: process settings and acceptance limits must come from the approved design and inspection plan.
A URS for an automated cell is built from individually numbered, verifiable, business-driven requirements covering scope, throughput, interfaces, safety, and lifecycle cost, and it must be version-controlled and approved before supplier evaluation.
Validating a machine learning model for a regulated process follows GxP and FDA AI/ML guidance: lock training data, run K-fold cross-validation, test on held-out data, then monitor drift in production. Protiviti's four-pillar framework (conceptual soundness, process verification, ongoing monitoring,
Tuning hundreds of PID loops efficiently requires a four-step method (sign check, P-only, add I, add D) plus a plant-wide assessment tool such as PlantTriage. The four-step method covers roughly 80% of loop performance problems; the remaining 20% benefit from automated loop-scanning software that be

Track scrap by cause automatically on a production line by capturing every reject event at the machine or workstation with a short standard cause code, the line, shift, part number, and operator. The captured data drives a Pareto of causes, feeds the Quality factor of OEE, and is used in weekly revi

Recycled-content tracking through production batches requires batch-level chain-of-custody records, declared specification limits, and minimum-percentage allocation recipes, since auditing the CoC is more reliable than testing the finished material.
OEE reason-code gaming is stopped by removing scorecard incentives, auto-classifying PLC-detected stops, capping the code list at 6-8 high-level categories, and gating corrections to a 5-15 minute window. OEE is used as a diagnostic, not a bonus metric, so operators no longer have motive to mis-tag
Start a shop-floor AI project with limited data by using quotes, job history and purchase records you already have, then layer IIoT and MES capture on top. Proven path: pick one problem, build a data foundation, run a 60-90 day pilot, expand.
Sizing an industrial edge server for plant analytics is a four-step engineering exercise: profile the workload (ingest tags/s, model type, frame rate), size CPU+RAM+GPU+storage to peak duty with 30-50% headroom, harden the chassis to the cabinet environment (temperature, vibration, dust), and valida
A CMMS asset hierarchy is a five-level parent-child structure: Site, Facility, System, Asset, Component. Build it by inventorying critical equipment, applying ISA-95 or ISO 14224 naming, then charging work orders to the lowest level for accurate cost rollup and FMEA.
Vibration alarm thresholds set without a baseline-relative, multi-sensor configuration generate the false alerts that erode technician trust and cause real failures to be ignored. Engineering-grade practice uses two-tier limits, ISO 20816/10816 for overall velocity, adaptive baselines, and seven pre
Plant cybersecurity starts with network segmentation: place every machine on an isolated subnet behind an industrial router or dual-NIC PLC, use VLANs to split IT, OT, and machine networks, and restrict firewall rules to only the traffic MES, SCADA, or remote service genuinely need. NAT hides intern
Tiered daily management runs as a four-level cascade (Tier 1 frontline, Tier 2 supervisory, Tier 3 value stream, Tier 4 plant) of short standing meetings, each anchored by a digital SQCDM board that surfaces deviations, escalates unresolved issues, and assigns actions with owner and due date[S5
A bad model update on the shop floor is rolled back by freezing the running model, verifying the last known-good artifact, then promoting the previous version through the same promotion path used for any production change. The procedure depends on a pre-update snapshot, model registry tags, and a do
Automated Scope 1 and 2 reporting links plant meters (PLCs, sub-meters, utility APIs) to a carbon ledger that applies GHG Protocol factors in real time, replacing spreadsheet accounting. The shift is driven by California SB 253 (disclosure due 2026-08-10, penalties up to $500,000/year) and EU CSRD l
Digital work orders cut MTTR by 30-40 percent by stamping every repair-cycle stage and replacing paper handoffs with mobile, parts-linked workflows. Only 11 percent of typical MTTR is the actual wrench time; the rest is detection, dispatch, diagnosis, and parts wait, all of which a CMMS compresses.
New product line ramp compresses from months to weeks by stacking three digital layers: validated idea-to-launch automation, AI-driven sales onboarding, and CRM-native ramp workflows. Skip the layers and ramp drifts past 5 months; use them and 30% faster productivity is a documented outcome (2026).
Prioritizing manufacturing AI use cases requires scoring business value, technical feasibility, and data readiness on a single matrix, then sequencing from lowest-effest, highest-ROI projects toward more ambitious ones. Gartner peer consensus in 2025 framed this as impact, feasibility, and lifespan,
Plan an automation project budget contingency in four moves: build a high/medium/low confidence base estimate, size the reserve at roughly 5-10% of base cost for low-risk work and 15-30% where vendor or technology risk is high, log every dollar against a named risk in a register, and release funds o
AMR route planning around forklifts and people hinges on layered controls: data-driven conflict-zone mapping, segregated pedestrian walkways, zoned speed limits, V2V coordination, and ANSI/A3 R15.06-2025 risk assessments. Bolt-on sensors alone fail because each vendor runs its own safety logic, prod
For a first cobot cell, start with payload (3-30 kg), reach, repeatability, and ISO/TS 15066 PFL compliance; match the arm to a task that is repetitive, low-risk, and tolerant of ±0.02 mm. Skip the hardest job and use a 6-axis arm in the 6-12 kg class for the fastest payback.
Migrating MES data without losing traceability history requires an export audit first, vendor-validated field mapping, a parallel-run reconciliation window, and a small-scale test that proves genealogy links and audit-trail records survived intact.
Industry 4.0 maturity is measured by scoring a plant against defined dimensions (process, technology, organisation) on a 1-5 scale using frameworks like SIRI, IMPULS, or acatech. The score exposes which dimension is lagging so investment is targeted, not guessed. A structured assessment beats gut fe
Connected worker program ROI is measured by quantifying annualised financial gains (productivity recovered, downtime avoided, quality scrap reduced, onboarding time compressed) against total program cost (licensing, devices, integration, change management), then dividing net benefit by cost. The con
Connected torque tools improve assembly quality by capturing every fastening event as timestamped digital data, enforcing torque and angle targets, and pushing results into QA networks for traceability, error-proofing, and standards compliance.
EtherNet/IP and PROFINET each hold roughly 30% of the global industrial Ethernet market, about 60% combined, with PROFINET IRT reaching 250 µs cycle times and EtherNet/IP typical scans of 0.5–10 ms. Pick by PLC lineage: Siemens shops run PROFINET, Rockwell/Logix shops run EtherNet/IP, with each prot
Energy monitoring for injection molding machines is anchored on specific energy consumption (SEC) in kWh/kg of shot weight; GB/T 30200-2023 defines the Chinese test method, while 2024-2026 field data show hydraulic presses running 0.5-0.75 kWh/kg versus all-electric machines below 0.30 kWh/kg, depen
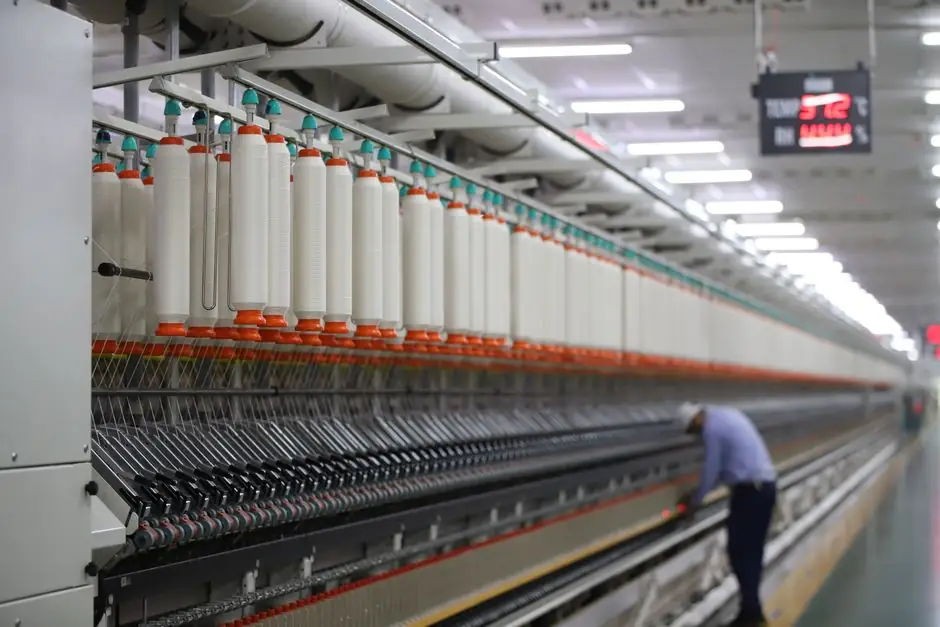
Injection molding energy benchmarks put variable load at 0.9–1.6 kWh/kg and base load at 20–40% of plant use, with ~30% discretionary savings available. All-electric and hybrid drives, plus R²-tracked process parameters, deliver typical 7–13% reductions per shift.
ASHRAE Level 1, Level 2, and Level 3 energy audits differ by rigor, data collection depth, and cost: Level 1 is a walk-through with rough-order-magnitude savings, Level 2 adds energy surveying and financial analysis, and Level 3 delivers detailed capital-project engineering with sub-metering[S2
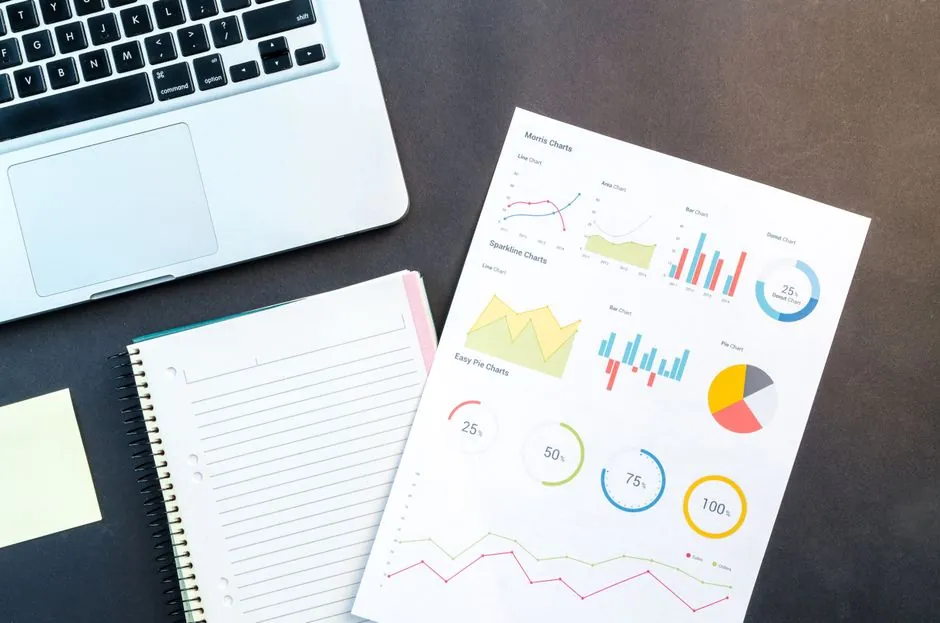
End-of-line test data analytics converts the final quality gate into a yield-improvement engine: streaming test results against unit-level identifiers expose first-pass-yield drift, bin-pattern shifts, and station-level root causes that paper-based logs miss. Best-fit stack pairs per-unit traceabili
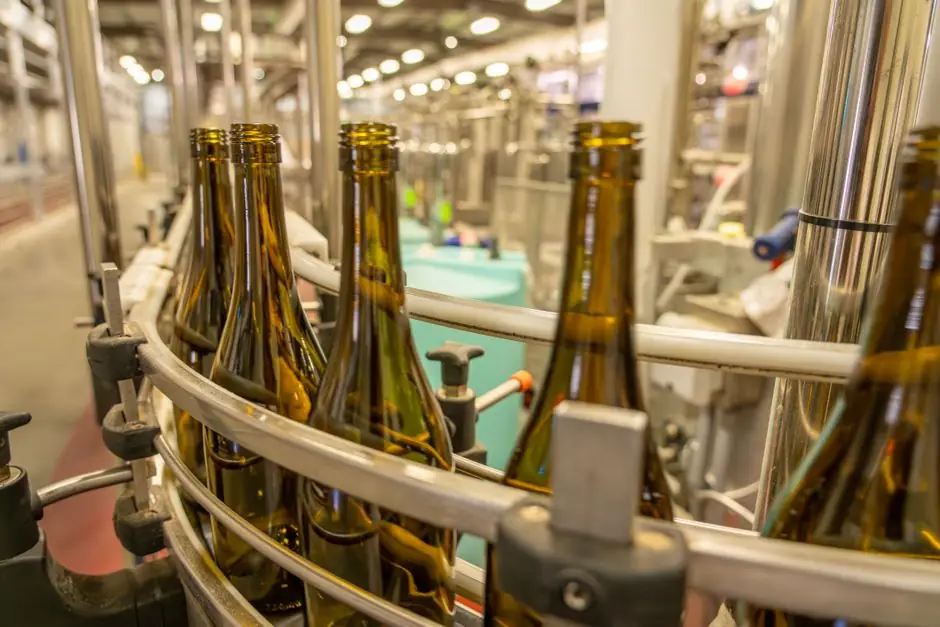
End-of-line packaging automation combines case packing machines, stretch wrapping machines, robotic palletizers, and conveyors into one cell, with market estimates rising from $6.6B in 2025 to $9.9B by 2034.
End-of-arm tooling (EOAT) costs range from $200 for entry-level plastic tools to over $8,000 for custom designs, and quick-change systems can cut changeover lead time from 20 days to 3 days while reducing per-tool cost by up to 94%.
In-line electrode coating thickness control in lithium-ion battery production relies on non-contact sensors (laser triangulation, confocal chromatic, X-ray, beta) to measure wet or dry coating in real time, with closed-loop feedback to the coater gap or speed to keep coating weight within tight ±1–2
RFID beats barcodes for work-in-process tracking where multiple items, hidden tags, or sub-assemblies must be captured without line-of-sight, with reported read rates of 99.5% and dozens of tags read per second. Barcodes remain the lower-cost choice for single-item scans, small parts, and tight unit
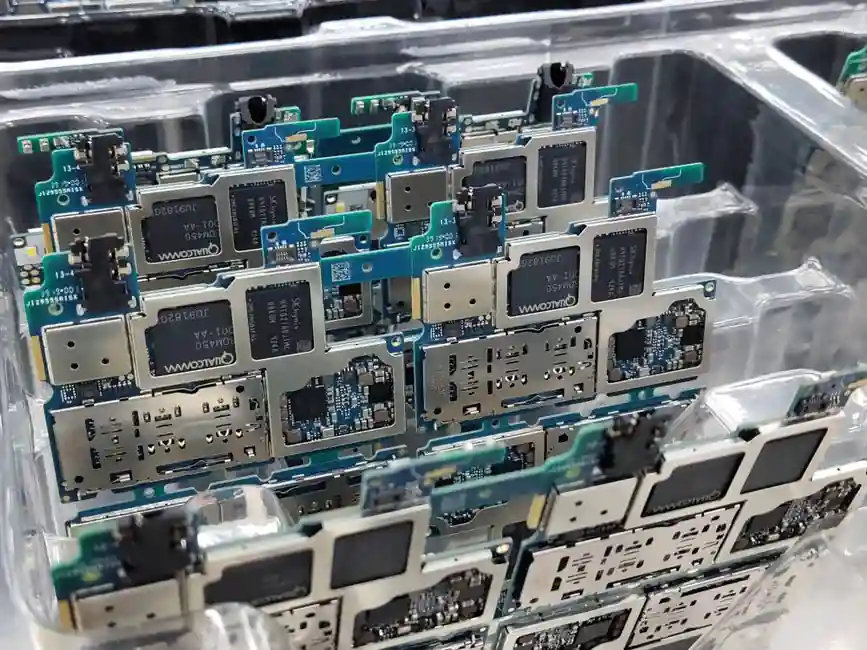
Box build assembly automation hits hard limits at cable routing, harness dressing, and final electromechanical integration, where hand work and vision-guided cobots still dominate. EMS providers in 2025-2026 use robotics, AGVs, and AI vision for PCB mounting, screwing, and inspection, but enclosure-
Electronic travelers replace paper routing packets with station-level digital capture, cutting keying labor, accelerating traceability from days to seconds, and supporting ISO 9001 and IATF 16949 audits. For job shops under 50 people, pilot on one value stream over 4–6 weeks before retiring paper.
Electronic logbooks replace paper shift books with timestamped, searchable entries that cut handover errors in continuous 24/7 plants. Over 40% of plant incidents occur at shift change, and structured digital logs enforce templates, photo evidence, and signed acknowledgement to close the handover ga
Electronic batch record (eBR) modules inside pharmaceutical MES compress QA review cycles from days to hours, enforce the master batch record at execution, and must meet 21 CFR Part 11 with full electronic signatures and data integrity.
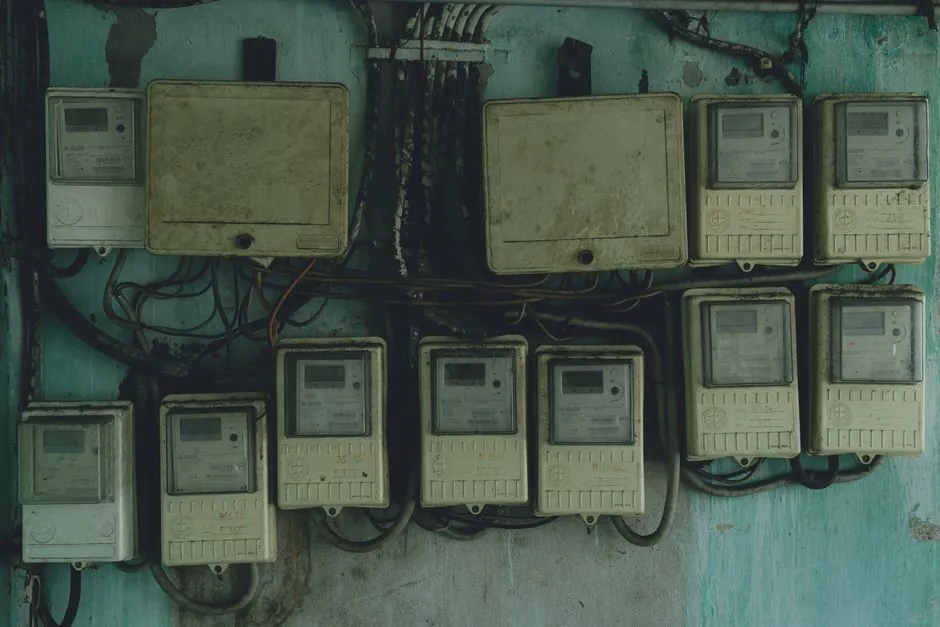
Continuous temperature monitoring of busbars and breaker contacts inside medium-voltage switchgear is now standard practice, using fiber optic, infrared, or RTD sensors to catch loose joints and hotspots before arc flash events. Most field failures trace to joint resistance, oxidation, or thermal cy
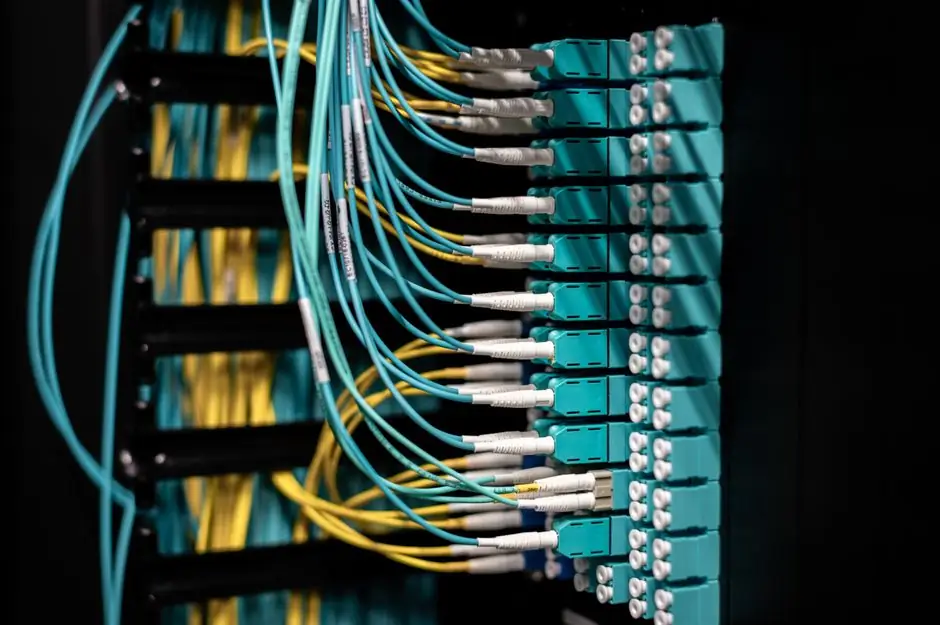
Edge gateways are selected when the task is protocol conversion plus local buffering, filtering, and security segmentation; a serial converter only does network access, while an IoT platform handles long-term device operations. Choose by scenario-driven protocol count (often 300+), compute tier, rug
Edge device fleet management unifies OTA firmware updates, zero-touch provisioning, and remote diagnostics across distributed industrial endpoints, with platforms like ZEDEDA, Fleet (fleetdm.com), EdgeIQ Symphony, and FleetTrackr delivering CI/CD-integrated, FOTA-capable orchestration at scale[
Edge analytics typically delivers sub-1 ms latency for high-frequency vibration data, while cloud analytics offers greater processing depth at the cost of 10-50 ms or more round-trip time. For condition monitoring, edge handles FFT and anomaly detection locally, with cloud reserved for fleet-level t
Drones inspect live flare stacks, storage tanks, and chimneys without shutdown, with collision-tolerant frames entering 24-inch manways and 4K + thermal + LiDAR payloads. Compared to rope/scaffold at $50-100/man-hour, UAV campaigns cut cost by 60% and platform downtime from days to single shifts.
Drive-based condition monitoring uses current and speed signals already measured inside the variable-frequency drive to detect motor, bearing, and alignment faults without external vibration sensors, cutting retrofit cost on multi-motor lines.
Drive parameter backup reduces VFD swap-and-recommission time from one to four hours to under 30 minutes when a verified parameter file exists. Best practice is a tiered approach: keypad copy, manufacturer software, removable media, plus a PLC/SCADA snapshot, refreshed after commissioning, befo
Automated downtime tracking detects machine stops from PLC tags, current sensors, or cycle pulses, then prompts operators for a reason code from a short, two-level taxonomy. Plants that replace paper logs with this signal-plus-confirm pattern typically cut unplanned downtime 20 to 50% within six mon
RFID inventory systems typically lift accuracy from a 65-75% barcode baseline to 93-99% based on 10-retailer evidence, but the cost case depends on tag price, reader count, and software integration depth. Total-cost-of-ownership swings the verdict: high-SKU retailers usually see payback; low-SKU or
Industry 4.0 does not collapse headcount outright; it shifts the worker from a hands-on operator to a systems supervisor, with the World Economic Forum's 2018 employer survey putting automation-driven workforce reduction at 50% of respondents but 38% also planning to extend their workforce into new
Augmented reality assembly guidance reduces complex-assembly errors and cycle time, with DHL's vision-picking program reporting 15–25% productivity gains and industrial XR shipments growing over 40% year-over-year in 2025. Gains depend heavily on task complexity, hardware maturity, and content autho
Small plants with simple, low-volume runs can rely on ERP for finance, purchasing, and inventory, but once real-time shop-floor visibility, lot traceability, or OEE tracking matter, an MES becomes the practical add-on rather than a replacement.
Lean and Industry 4.0 complement each other when integrated as "Lean 4.0": a 2023 systematic review of 41 papers found positive synergy between the two paradigms, with a follow-up 2026 review confirming the consensus while flagging that most research over-emphasizes technology and under-covers human
Industrial exoskeletons reduce back, shoulder, and arm musculoskeletal loading on assembly lines in published studies, yet most trials enroll fewer than 15 participants in lab settings, leaving workplace injury-rate evidence inconclusive as of October 2026.
Cobots can run without a safety fence only when the application passes a documented risk assessment against ISO 10218-1/-2 and ISO/TS 15066, with the 2025 ISO 10218 revision folding collaborative guidance into the main standard. In Europe the Machinery Regulation (EU) 2023/1230 replaces 2006/42/EC o
Distributed manufacturing networks pair a governed digital work-order layer with qualified local capacity, cutting lead time and inventory risk when files, routes, and quality context travel intact. Practical fit signals are regional service parts, low-volume spares, maintenance operations, and emer
Discrete event simulation pairs with line balancing to expose real bottlenecks, with documented cases showing 12% throughput gains, 30% efficiency-deficit removal, and a $50M avoided investment by replacing queue-length intuition with stochastic event modelling of cycle time, failure, and buffer int
Digital work instructions cut assembly errors by 55-60% and reduce build time by 12-20% versus paper, directly raising first-time quality on the line. The 23% of manufacturing downtime and 80% of quality defects attributed to human error make a digital, step-confirmed workflow the highest-leverage f
Digital spare-parts warehouses, where CAD files replace physical stock and parts are 3D printed on demand, raise unresolved IP, product-liability, and product-safety questions: patent exhaustion, design rights, trademark and copyright exposure, and who carries defect liability when a decentralized n
A digital twin is a persistent, live-data mirror of one specific physical asset, while a simulation is a bounded, hypothesis-driven model that runs once and stops. Pick simulation for design-phase "what if" questions on cost 0 to 50000 USD; pick a digital twin only when you can sustain 1 Hz plus sen
A digital model is a static representation with no automated data link, a digital shadow adds one-way real-time data from physical to digital, and a digital twin closes the loop with bidirectional automatic data exchange. Choosing between them depends on whether you need visualization, monitoring, o
Digital twin monitoring reaches 85 to 96 percent failure-prediction accuracy on modern industrial platforms, while standalone anomaly detection scales cheaper but flags raw signal deviations without root-cause context. A digital twin is the right call for high-criticality rotating equipment; statist
Digital twin update frequency and data latency are application-driven control parameters, not one-size-fits-all values: 2025-2026 literature shows frequencies from sub-second to multi-minute, with end-to-end tail latencies above 500 ms in production. Selection depends on control loop type, with clos
A plant digital twin programme requires four cross-functional roles: process/data engineering, 3D and simulation, IIoT/OT, and AI/ML analytics, structured as a hub-and-spoke team led by a DT programme owner. Hiring profiles should target physics, data science, and instrumentation skills mapped to IS
Digital twin deployments in discrete manufacturing are widely cited with throughput gains of 15-25% and end-of-line test reductions of up to 98%, but 2026 guidance stresses build-vs-buy discipline and high-fidelity PLM integration over aspirational ROI claims. The market is projected to grow from $2
A digital twin of a battery cell production line is a multi-layer cyber-physical model that fuses real-time sensor data with electrode, assembly, and conditioning simulations to predict defects, throughput, and yield. The EU BATTwin project (Dec 2023 to May 2027) targets the 15-30% ramp-up defect ra
Digital twin licensing for industrial deployments divides into per-seat (per named user) and per-asset (per modelled equipment or tag) models, with cost outcomes driven by user count, asset count, and feature tier. Per-seat dominates in engineering workstations, while per-asset scales better for pla
Throughput, yield, and energy per unit are the three KPIs most often used to quantify digital-twin ROI on production assets. A 2023 study proposes four quantitative KPIs for measuring DT performance, while ROI guides stress baseline-locked measurement of production yield, energy per unit, and waste
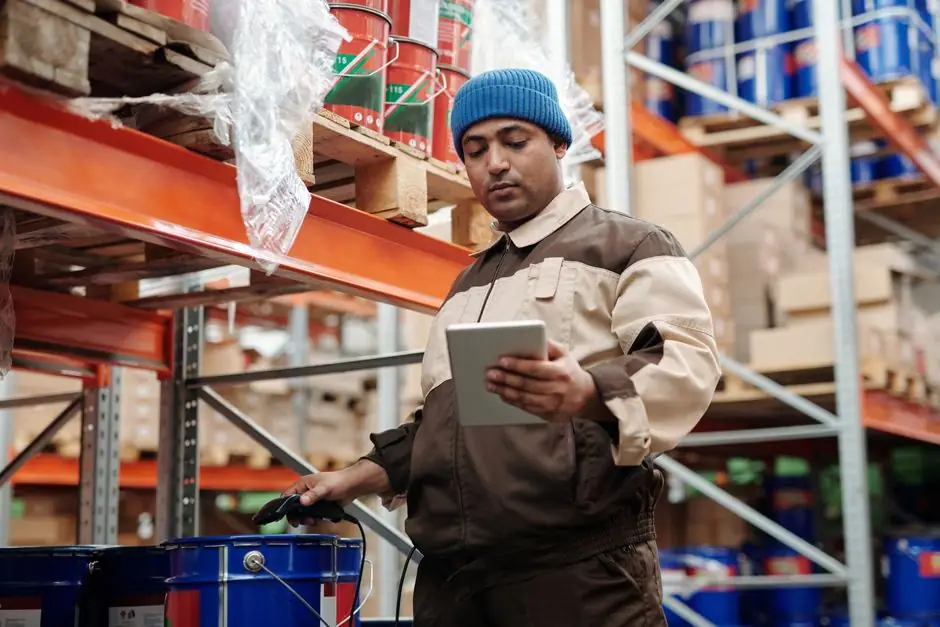
Warehouse digital twins now link WMS, WES, RTLS and AMR fleet telemetry into a live replica for slotting, labor, dock and wave planning. AI-enhanced twins drive path planning, task allocation and storage assignment in real time, with computer vision closing the inventory-accuracy gap. Limitations re

A digital twin for semiconductor fab scheduling is a real-time virtual replica of tool sets, WIP flow, and dispatch rules that predicts cycle time and dynamically re-assigns lots; published studies report up to 20% higher on-time delivery, 25% shorter cycle times, and 14% higher factory output from
Digital twin validation for robot cell layout and reach studies pulls reach, collision, and PLC handshake checks forward into simulation, cutting late mechanical rework on new cells. A 2024 NIST method paper and 2026 RDT review document how IIoT, ROS, and physics engines support this.
Process-plant digital twins (steady-state/continuous dynamics, DEXPI/OPC UA stack) and discrete-plant twins (event-driven, PLC/MES-driven) diverge sharply in data rate, model fidelity, and payback window. Continuous plants prioritise first-principles simulation and 6-18 month deployment cycles.
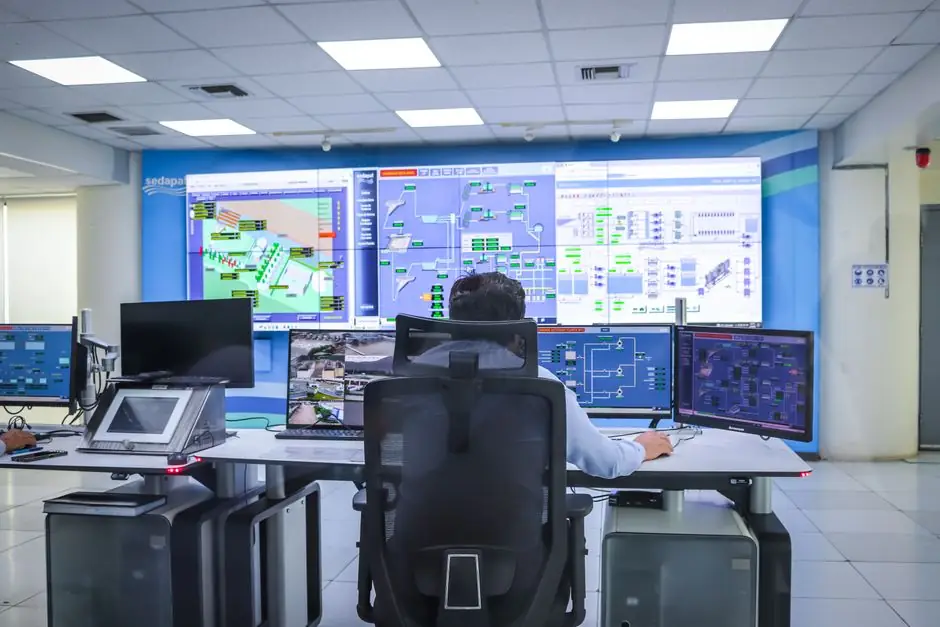
A digital twin used during pre-CAPEX layout review can compress development time by up to 50%, validate a $5M line build or a $500K equipment relocation in simulation, and recover 15-30% of capital outlay that would otherwise be locked into rework once concrete is poured.
A digital twin for injection molding maps fill, pack, and cool stages into a simulation that mirrors the real process window, letting engineers sweep injection speed, mold temperature, and holding pressure before cutting steel. The credible value in 2025-2026 is upstream DOE on a virtual mold, not a
Digital twin technology for utilities and HVAC delivers 5–35% plant energy savings, 18–35% building energy reductions, and 10–15% peak demand cuts, with payback typically 6–24 months. Adoption hinges on physics-based modeling, real-time IoT data, and ASHRAE Guideline 14 calibration.
Digital twins for CNC cutting are now used to model chatter, tool wear, and thermal error in real time, with documented implementations built on the ISO 23247 framework. Recent reviews and shop-floor case studies show error reductions of around 50% and full-lifecycle mapping from G-code to compensat
Discrete-event digital twins on filling and packaging lines identify the true bottleneck station in real time and quantify the OEE gap to target, with field benchmarks of 52% downtime reduction and 14% OEE uplift on a canned-beverage line.
Digital twin fidelity is no longer a single number, it is a stack of spatial, temporal, behavioral, semantic and statistical dimensions, each with its own metric. Optimum, not maximum, fidelity is the engineering target, and high-fidelity modelling pays off when the use case is safety-critical, dyna
ISO 23247 is a four-part manufacturing digital twin framework (Parts 1 to 4 published 2021, Part 6 added since) that defines a layered reference architecture, unique asset identity, and information-exchange rules for linking physical assets to live digital models via OPC UA and MTConnect.
Digital twin architectures stack six recurring layers from physical assets to visualization, using bidirectional data flow, edge sensors, and AI-driven analytics. Industrial deployments report 75% adoption and over 10% ROI, with ISO 23247 governing manufacturing implementations.
Digital twin and PLM integration for engineering changes now routes real-time IoT data into the EBOM, MBOM, and ECN workflow, with enterprise platforms from Siemens, PTC, and Dassault Systèmes anchoring the stack. By 2024 roughly 25% of large manufacturers ran an active digital twin program, up from
Digital twins integrated with MES/MOM systems report 35% faster root-cause analysis, 28% less unplanned downtime, and 20% higher OEE in 2026 deployments. Five integration patterns dominate: real-time process twin sync, predictive scheduling, closed-loop quality, predictive maintenance, and digital t
Digital TPM boards replace paper operator rounds with mobile, checklist-driven inspections that feed live readings into CMMS or SAP, cutting manual transcription and surfacing slow drift 24-72 hours earlier. Tablets, photo evidence, and acceptance criteria are now standard in autonomous-maintenance
Digital thread and digital twin are not competing concepts in manufacturing. A digital thread is the data highway linking every product lifecycle artifact, while a digital twin is the dynamic model that rides on it. Pick thread first for traceability; add twins for real-time simulation.
Digital permit-to-work (ePTW) systems replace paper forms with electronic workflows for hot work, confined space, electrical isolation, and other high-risk tasks, with vendor pricing starting at roughly $97/month for SMB tiers and enterprise plans reaching $9,100/year per site. They target process p
Digital and electronic kanban replace physical cards with barcode, RFID, sensor, or software triggers that fire replenishment signals to ERP/MES/WMS in real time. E-kanban is sized by the formula N = ((Daily Demand × Lead Time) + Safety Stock) / Container Quantity, and becomes mandatory once SKU cou
Digital FMEA-to-control-plan linkage is replacing spreadsheet workflows in automotive and aerospace plants: tools like Relyence, DataLyzer Qualis, and iFactory now sync PFMEA rows directly to control-plan characteristics, and IATF 16949 auditors flag disconnected documents as missing risk-based evid
Digital APQP and PPAP document management replaces Excel and email-based submission packages with cloud platforms that automate 18 AIAG PPAP elements, IATF 16949 traceability, and FMEA/Control Plan linkages. Suppliers using tools like Net-Inspect, High QA, and Omnex now configure AS9145 and AS13100
A well-configured digital Andon with mobile escalation holds first-acknowledgment under 90 seconds and average response at roughly 4 minutes, versus about 22 minutes for stack-light-only systems, a 5x gap that defines the 2026 benchmark. A 58% reduction in response-to-resolution time and 34% unplann
High-pressure die casting porosity in aluminum and magnesium alloys is being cut through three converging methods: vacuum-assisted cavities, multi-stage injection profile control, and X-ray/CT analytics with machine-learning pore characterization. Process data on shot pressure, fill velocity, melt t
Hard-coded credentials in industrial devices are factory-baked strings in firmware that survive password rotation, granting attackers persistent privileged access. Default passwords are a different, weaker class: change them at first login and the risk closes. EN 18031 and IEC 62443-4-2 now govern h
For a hybrid process plant in 2026, the practical answer is rarely DCS-or-PLC-or-SCADA: it is PLCs at the machine or unit level, a DCS-grade process-control layer for interacting continuous loops, and SCADA-style supervision over both. The choice between a traditional DCS (Emerson DeltaV, Honeywell
Sensor data quality rules for flatlines and gaps typically combine range checks, persistence/stuck-value tests, max-gap duration flags, and statistical anomaly detection, with raw channels preserved and edited channels flagged separately for audit. This applies across environmental monitoring, IIoT,
A data lakehouse merges open object storage, ACID table formats, and warehouse-grade metadata to give manufacturers one governed platform for time-series OT data, BI, and AI/ML. Open table formats such as Apache Iceberg, Delta Lake, and Apache Hudi now anchor most plant deployments, with medallion l
Data historians and time-series databases are complementary, not interchangeable: historians handle OT-side tag acquisition via OPC-UA/Modbus with quality codes, while TSDBs handle IT-side SQL analytics at IIoT scale. Most plants now run both in parallel.
Data governance for manufacturing binds data ownership, quality, lineage, and access to ERP, MES, SCADA, and IoT outputs. Verdantis 2023 reports 51% of manufacturers face significant MRO data quality issues. Core framework: stewards, master data, and OT/IT integration.
Raw PLC tags like DB1.DBD4 or 16,124 carry no unit, asset, or threshold, so a historian receives numbers that cannot be interpreted. Industrial data contextualization layers engineering units, asset hierarchy, timestamps, and operational bounds onto those values, turning noise into the structured in
EU Cyber Resilience Act (EU 2024/2847) reporting duties are live since 11 September 2026, with the full essential cybersecurity requirements binding on all new products with digital elements placed on the EU market from 11 December 2027, reshaping compliance for machine and component makers.
Clamp-on current transformers (CT clamps) split into a hinged core, snap around a live conductor without breaking the circuit, and induce a proportional secondary current for non-contact machine state monitoring, load profiling, and energy metering. Split-core iron-core units cover 5 to 1000 AAC RMS
In-line CT now inspects EV cells in roughly 3 seconds per scan at 20 parts per minute, while offline CT remains the choice for R&D and failure analysis where higher resolution and longer scan times are acceptable. Plants choose in-line for closed-loop production control and offline for first-article
Crane anti-sway and positioning automation combines VFD motion shaping, encoder/gyro feedback, and PLC trajectory planning to suppress pendulum swing on overhead and automated transfer cranes. Gyroscope-based sway angle feedback and laser ranging deliver sub-degree residual swing, with retrofittable
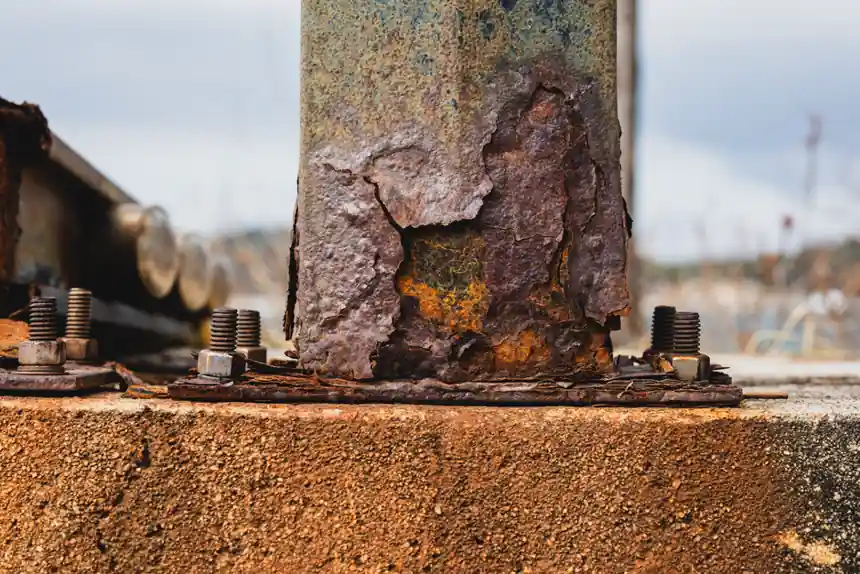
Wireless corrosion sensors split into two camps: battery-powered active nodes (LPR, UT thickness, ER probes) for plant water and pipework, and fully passive LC or chipless RFID tags for harsh high-temperature and embedded structural use. Specification hinges on measurement principle, environment, da
For industrial sites weighing a corporate (offsite/virtual) PPA against onsite solar, the deciding factors are roof/land availability, capex appetite, and contract tenor. Onsite PPAs (15-25 yr, €1 buyout typical) fit credit-constrained operators; offsite/corporate PPAs suit multi-site buyers needing
A control plan is a row-per-characteristic table that links each spec, gauge, sample frequency, and reaction step, and digitizing it ties reaction plans directly to the live SPC chart on the operator screen, cutting containment time on out-of-spec events. Electronic capture, e-signatures, and live d
UL 508A 3rd Edition, ANSI-designated on 2025-06-26, is the binding North American standard for industrial control panel construction, covering components, SCCR per Supplement SB, wiring, markings, and 120 Vac/250 Vdc control circuit limits. Compliance requires every component to be UL Listed or Reco
Control loop audits consistently find that 70–80% of PID loops need retuning and roughly one in three carries a mechanical fault, with oscillation the most visible symptom. Audit findings split into tuning deviations, hardware issues, and disturbance pathology, each requiring a different corrective
Sizing enclosure cooling starts with a two-part heat load: internal dissipation from components plus external conduction/radiation through the cabinet walls. Use watts x 3.41 = Btu/hr, add surface-area heat transfer, and select fans, heat exchangers, or air conditioners with 20-30% margin.
Real-time optimization (RTO) re-tunes process operating conditions on cycles typically measured in hours, sitting above model-predictive control and below plant-wide economic planning. On a refinery hydrocracker case study, integrating RTO with MPC targeted the maximization of an economic objective
End-to-end continuous manufacturing (CM) in pharma cuts cycle time from months to days and trims QC effort by 50–70%, but it requires higher upfront capex and full revalidation of the control strategy. Batch remains the lower-risk default for low-volume, high-potency, or multi-product facilities. Ch
Conformal coating inspection under IPC-A-610 and IPC-CC-830 confirms coverage, thickness, and keep-out compliance on PCB assemblies using UV-A (320–400 nm) fluorescence, white-light visual, and 3D AOI inline methods, with rework decisions routed through a documented accept/reject/touch-up framework.
Condition-based, predictive, and reliability-centered maintenance are distinct strategies, not synonyms. CBM is threshold-triggered, PdM is trend-based, RCM is the decision framework that picks the right strategy for each failure mode under SAE JA1011.
In hydraulic systems, 70% to 90% of wear and failure is contamination-related, so ISO 4406 particle counts taken by light-blockage or dynamic-imaging sensors drive the maintenance decisions that separate reactive from informed service. The practical decision in 2026 is sensor type (light-blockage vs
FDA issued the final Computer Software Assurance (CSA) guidance on February 3, 2026, replacing the prior CSV paradigm with a risk-based, least-burdensome approach for medical-device production and QMS software. CSA retains 21 CFR Part 820 obligations but slashes scripted-test documentation in favor
Centrifugal compressor anti-surge tuning centers on a measured surge control line offset 10 to 15 percent above the actual surge line, with sub-200 ms recycle valve response and adaptive gain scheduling to keep operation safe. API 617 governs the surge test method used to build the performance map,
A compressed air audit is a structured data-logger assessment that typically recovers 15–35% of system energy cost, with single 1/4-inch leaks costing $2,500–$8,000 per year and every 2 psi of over-pressure adding roughly 1% to compressor energy use. Suitable for any plant spending significant share
Composable MES (cMES) is an orchestrated set of independently deployable, API-addressable services (MACH: Microservices, API-first, Cloud-native, Headless) sharing a canonical data model, while monolithic MES is a single seated application with a top-down data model, rigid workflows, and deployment
Reel-level (per-component, per-board) MES binding cuts suspect-board population from 2,300 to 47 in a documented PLC backplane case. Lot-level binding fits commercial assemblies; reel-level or unit-level is the floor for IEC 62443 and Machinery Directive 2006/42/EC scope.
Collaborative welding robots, commonly called cobot welders, are a practical fit for job shops running batches as small as five pieces, with typical payback reported in 12 to 24 months and no-code teach pendants removing the need for dedicated programmers.
Cobot palletizers cap out around 25 kg payload and 6-13 cycles/min, suiting low-volume, mixed-SKU lines; industrial palletizing robots handle 300+ kg and 10-20 cycles/min for sustained high-volume production. Pick the architecture by payload, throughput, and risk-assessment outcome, not by category
Power and force limiting (PFL) cobots cap the tool center point at 250 mm/s during collaborative operation, with force derived from joint torque sensors or motor current and a stop time under ~250 ms. ISO 10218-1/-2 plus ISO/TS 15066 remain the governing documents, with R15.06-2025 lifting PFL compl
Cobot screwdriving cells now routinely hit 99.9% placement accuracy when the workpiece fixture, datum scheme, and torque controller are engineered together, not when the cobot is picked first. On tight-tolerance joints the real accuracy ceiling is set by the fixture and the screw-feeding head, not t
A cobot risk assessment, run under ISO 12100 and required by ISO 10218-2 before commissioning, uses five iterative steps: define machine limits, identify hazards, estimate risk, evaluate it, then apply the three-step reduction hierarchy (inherent safe design, safeguarding, training).
CMMS and EAM both run a predictive maintenance program, but they answer different questions: a CMMS drives asset uptime through work orders, PM triggers, and sensor-based condition alerts, while an EAM wraps that work inside a full asset-lifecycle system covering procurement, risk, and disposal. For
CMM robot loading typically pays back in 18-36 months for mid-volume shops, with fully burdened labor displacement, throughput gains, and scrap reduction each contributing documented shares of the ROI. Volkswagen Foundry Kassel reports 30% metrology-time savings from integrated loading, while a 5-DO
Edge and cloud are not competing options for manufacturing analytics; they split cleanly by latency budget. Edge AI delivers sub-10 ms inference and cuts 5-year TCO by 30–50% on high-volume, low-latency workloads, while cloud AI wins on cross-site model training and variable workloads where pay-as-y
Cloud MES typically deploys in weeks with lower upfront cost and automatic vendor updates, while on-premise MES offers sub-millisecond latency and full data control at the price of 6-18 month rollouts and full-stack validation. Choose cloud when multi-site visibility and OpEx budget dominate, on-pre
Cloud ERP to shop floor integration breaks into three architectural patterns: continuous-sync cloud, edge-buffered with offline store-and-forward, and asynchronous batch. Latency ranges from 15 seconds for direct event capture to multi-hour batch posting, with offline modes preserving 99.2% yield da
Closed-loop CNC machining uses a spindle-mounted probe to measure the part mid-cycle, compare it to the CAD model, and update tool offsets before the next pass, with Renishaw SPRINT scanning at ~1,000 points/sec and Blum touch probes under 1 µm repeatability now standard. Cycle-time cost is small ve
Optimized CIP programs in food, beverage, and pharmaceutical plants routinely cut water use by 15-25% and trim cleaning time by up to 23%, with single-circuit reductions of 15 minutes per cycle and total cleaning-time savings as high as 20%. The biggest gains come from real-time end-of-soil detectio
Choose a condition monitoring interval at no more than half the asset's P-F interval, weighted by criticality and detection technique. A 6-week P-F window means checking every 3 weeks or more often.
Chiller plant optimization cuts cooling energy 20 to 40 percent in multi-chiller manufacturing plants, with documented PNNL cases at 35 percent and payback under five years at $0.11/kWh. Savings stack from chiller sequencing, VFD pump control, and condenser-water reset strategies.
SMED cuts changeover time 30 to 60 percent in structured programs, with Toyota-origin case data averaging 94 percent reduction, and each 10 minutes of setup removed adds measurable OEE availability, smaller batches, and lower WIP without new CAPEX.

Changeover Time is the lost window from last good unit to first good unit of the next product, and SMED programs typically target a 95%+ reduction versus the original baseline. KPI dashboards track it alongside OEE, throughput, and schedule adherence, with dataPARC and PlanetTogether confirming its
AI kiln control cuts cement fuel use 6-15% and stabilizes free lime without hardware swaps, with peer-reviewed models showing 3-9% net energy and CO2 reductions after IT load.
Virtual commissioning catches PLC safety logic errors, robot path collisions, and race conditions against a functionally accurate digital twin before physical equipment is built, cutting commissioning time 40-75% and reducing on-site troubleshooting cost 15-25%, per a March 2026 industry analysis [S
OEE can be applied to continuous process industries, but the discrete-built framework of Availability, Performance, and Quality needs adaptation: throughput replaces unit count, losses are defined per shift, and OPE variants are often a better fit for chemical, paper, and refining lines.
MQTT cannot replace OPC UA in brownfield plants because the two protocols solve different problems: OPC UA defines typed industrial data and semantics, while MQTT only moves messages. Real deployments pair them via OPC UA Pub/Sub over MQTT or a gateway, with the choice driven by existing fieldbus, l
Motor current alone can predict some motor failures, but not all. MCSA catches broken rotor bars, eccentricity, and stator shorts 60-180 days ahead, yet bearing defects and mechanical faults often need vibration data alongside current for reliable early warning.
AI can automate maintenance scheduling end-to-end, from work order generation and technician dispatch to PM interval optimization, cutting admin time by 40-60% per OxMaint 2026 data. The realistic scope covers pattern recognition, priority scoring, and skill matching; high-stakes decisions like crit
Generative AI can accelerate PLC coding by 30 to 50 percent, but only when wrapped in vendor guardrails and human-in-the-loop review; generic LLMs hallucinate logic and lack hardware context, so ungrounded AI is unsafe for live control code.
AI can adjust industrial process setpoints in closed loop, but human-in-the-loop approval stays mandatory for any high-risk or safety-significant change under current process-control governance frameworks. The 64% operational-versus-judgment gap identified in a 2026 enterprise survey defines where a
Digital twins can substitute for some physical process development trials, specifically as virtual control arms and in-silico optimization steps, but they do not fully replace physical testing. They cut cost and accelerate timelines (one biotech saved roughly €30 million and three years), and pair w
Calibration management software centralizes instrument records, automates reminder intervals (commonly 30/14/7 days), and stores NIST-traceable certificates to replace spreadsheet and paper tracking. ISO 17025, ISO 9001, and 21 CFR Part 11 are the three standards that most govern selection. It is th
Calibration intervals can be extended when instrument diagnostics and as-found reliability data prove consistent in-tolerance performance, using ILAC-G24/OIML D 10 methods and ISO/IEC 17025:2017 risk-based justification.
Cable condition monitoring in industrial plants centres on detecting insulation ageing in organic-polymer cables through reflectometry, LCR, IR, and online partial-discharge methods. Reflectometry remains the workhorse for locating degradation, while LIRA and integrated online systems now allow in-s
IEC 61511 compliant safety bypass and override management requires authorisation, risk assessment, compensatory measures, time limits, and verified restoration for every SIS maintenance activity in process plants.
Brownfield modernizations typically cut CAPEX by 40–60% per unit of added capacity and shrink project timelines by 30–50% versus greenfield builds, but under-planned programs overrun 25–50% on schedule and 20–40% on cost. Most line-level budgets land in the USD 1–5M range for AAC and discrete-asset
Raman spectroscopy is a Process Analytical Technology that quantifies substrate, metabolite, and product concentrations in real time inside bioreactors. A 785 nm immersion probe with multivariate chemometric models is now the standard PAT stack for upstream glucose, lactate, and amino acid tracking.
World-class beverage filling lines sustain 85%+ OEE against a 55–65% industry average, with high-speed PET rotary fillers operating at 36,000–72,000 bph and aseptic changeovers compressed to under 2 hours. SMED programs routinely cut format changeover from 60–90 minutes toward a 12-minute target on
Belt and chain drive monitoring for conveyors now combines current-signature drivetrain analysis with distributed belt-condition sensors, cutting unplanned stops 4-8 hours per failure in mining. Selection hinges on coverage of bearing faults versus belt splices.
Formation is the slowest step in lithium-ion cell production, typically 10 to 20 hours at 0.05C to 0.1C and 25 to 45 C, and dominates capex per gigawatt-hour. Three reduction routes, single-cycle formation, high-temperature ageing rooms, and pulsed/regenerative power conversion, each cut days off th
Industrial bakery and confectionery line automation now spans continuous mixing, stress-free lamination, tunnel ovens, automated pan handling, ultrasonic slicing, and end-of-line packaging robotics, with packaging cells reaching 1,800 cardboard pieces per minute and modular forming platforms cutting
Bad actor analysis from CMMS work order data is a Pareto-based reliability method that isolates the top 5-20% of assets driving 50-80% of unplanned downtime, cost, or production loss, typically over a 12-24 month rolling window. Calculation blends failure frequency, MTBF, MTTR, repair cost, and down
Autonomous process operations are graded on a five-level maturity scale, from Level 1 operations assistance to Level 5 full autonomy. Most process plants today sit at Level 2 (regulatory/PID control) or Level 3 (advanced regulatory), with closed-loop AI acting on a single domain only. Reaching Level
An autonomous counterbalance forklift costs USD 85,000–120,000 versus USD 25,000–35,000 for a manual unit, but the cost-per-pallet-move crossover happens in 18–36 months on multi-shift operations. Below ~500 moves/shift, manual remains cheaper per pallet.
Automotive paint shops consume 50-70% of total assembly-plant energy, with curing ovens and spray-booth HVAC as the two largest loads. AI-driven oven and ventilation control is delivering 15-25% shop-wide savings, with HVAC retrofits alone reaching 30% fan-energy cuts.
Automotive body shops run the highest robot density of any major industry, with the US car sector recording 1,287 installed robots per 10,000 employees in 2024, up from 1,200 in 2017. A modern body-in-white line typically integrates 60-90 articulated robots across welding, material handling, and ins
Industrial automation projects typically split spend across three blocks: hardware (controllers, robots, sensors, panels) at roughly 25-40% of the budget, engineering and integration labor at 30-50%, and software plus lifecycle services at 15-30%, with total turnkey spend ranging from $200,000 for a
AS/RS (fixed-rack cranes, shuttles, VLMs) and goods-to-person AMR fleets (G2P-AMR, shelf-to-person) attack the same picking problem from opposite ends. G2P-AMRs raise pick productivity up to 6x and shrink manual-labor reliance by about 50%, while AS/RS wins on storage density and deterministic throu
Automated overhead cranes in steel mills handle roughly 1,000 coils per day with thermal imaging and laser positioning, while paper mill cranes run at A6–A8 duty cycles lifting 30–80+ ton parent rolls with sway control and IP65 sealing.
Automated Gauge R&R on connected gauges quantifies the 0-0.8 mm spec window using crossed ANOVA with three operators and ten parts, two trials each, per AIAG MSA. Modern digital force gauges such as the AMETEK DFS II hold ±0.25% full-scale accuracy and push statistics to SPC over RS-232 or USB.
Asset twins, process twins, and line (system) twins are not interchangeable scopes: asset twins model one machine's component interactions, process twins model end-to-end workflows and throughput, and line twins model how multiple assets synchronize on a production line. Choosing the wrong layer inf
An asset naming convention in IIoT is a fixed rule set combining hierarchical codes (SITE-AREA-LINE-CELL-TYPE-NUMBER) with a unique ID, locking the structure before CMMS data loading. Templates and validation enforce it across plants, while IIoT tag data models layer alarm, control, and historian at
An asset criticality ranking segments plant equipment into critical, semi-critical, and non-critical tiers by scoring safety, production, environmental, quality, and financial consequences, so predictive maintenance (PdM) budgets land on the 5-20% of assets that drive the bulk of unplanned downtime.
Robotic aseptic fill-finish cells are now delivering up to 675 vials per hour inside H2O2-decontaminated isolators rated for Grade C rooms, displacing manual RABS lines under EU GMP Annex 1. Adoption is concentrated in cell/gene and biologic small batches where fill-volume tolerance is measured in m
Core AS/RS hardware runs $800–$2,000 per pallet position for four-way shuttle systems; total project budgets span $500,000 to over $2 million for unit-load installations, with passive racking alone at $50–$200 per position. The biggest cost swings come from system type, building readi
Time-series foundation models (TSFMs) deliver measurable zero- and few-shot forecasting wins on industrial sensor streams, but they are not a drop-in replacement for task-specific models and require careful scoping around data volume, distribution shift, and safety-critical use.
APS software for high-mix plants delivers documented ROI bands of 8-25% throughput gain, 10-20% inventory reduction, and pilot payback commonly inside 90 days when finite-capacity logic and measured cycle times replace spreadsheet planning, with selection driven by sequencing math depth, ERP integra
Anomaly detection flags out-of-distribution events without naming them; classification assigns defects to predefined categories. The 2025 arXiv pipeline VELM reports 80.4% accuracy on MVTec-AD by chaining both, while the global anomaly detection market reached $6.90B in 2025 with 18.92% ML-segment C
Multivariate sensor anomaly detection now spans statistical baselines, tree ensembles, and reconstruction-based deep learning, with 2025 surveys confirming the last group as the dominant direction for industrial time series. A practitioner shortlist: Mahalanobis/Isolation Forest for low-dimensional
Digital Andon systems cut response-to-resolution time by 58% and unplanned downtime by 34% versus physical stack-light setups, per iFactory 2026 deployments. Trigger layer, escalation engine, and MES data capture are the three differentiators.
AMR fleets lose measurable throughput at vertical transport nodes: shared elevators, roller shutters, and air-shower doors create queueing, dwell, and single-fleet monopolisation. The 2026 remedy is layered: route elevators only when unavoidable, hard-interlock door handoffs, and push interop traffi
AMR fleets typically pay back in 12-30 months depending on duty cycle, while forklifts carry compounding annual cost with no ROI endpoint. Choose AMR for flexible, mixed-traffic horizontal moves; choose automated forklifts for pallet stacking above 1.5 m; choose tugger trains for fixed milk-runs ove
AMR unit prices in 2026 sit between $30,000 and $300,000 depending on payload and sensor class, with $50,000–$200,000 the most cited bracket. Fleet software adds $128–$856 per month at entry to high end, plus a $5,000–$25,000 integration line item per project.
For AMRs, SLAM dominates new deployments in dynamic plants, while magnetic tape and reflector tape remain the lowest-cost options for fixed paths; laser triangulation sits between them on infrastructure cost and route flexibility. Pick SLAM for routes that change monthly, magnetic tape for sub-milli
AMR fleet size for a production plant is set by a capacity-demand balance: required robots equal peak trip demand times cycle time, divided by available productive hours per robot, then uplifted for charge, traffic and failure margin. Use OEM calculators such as the KUKA and KINEXON tools as a first
An AMR fleet manager sits between MES, WMS, and ERP task generators and the robots that execute moves; VDA 5050 v2.0 is the practical interoperability standard, and successful deployments hinge on API depth, OPC UA PLC bridging, and a tunable task-assignment model.
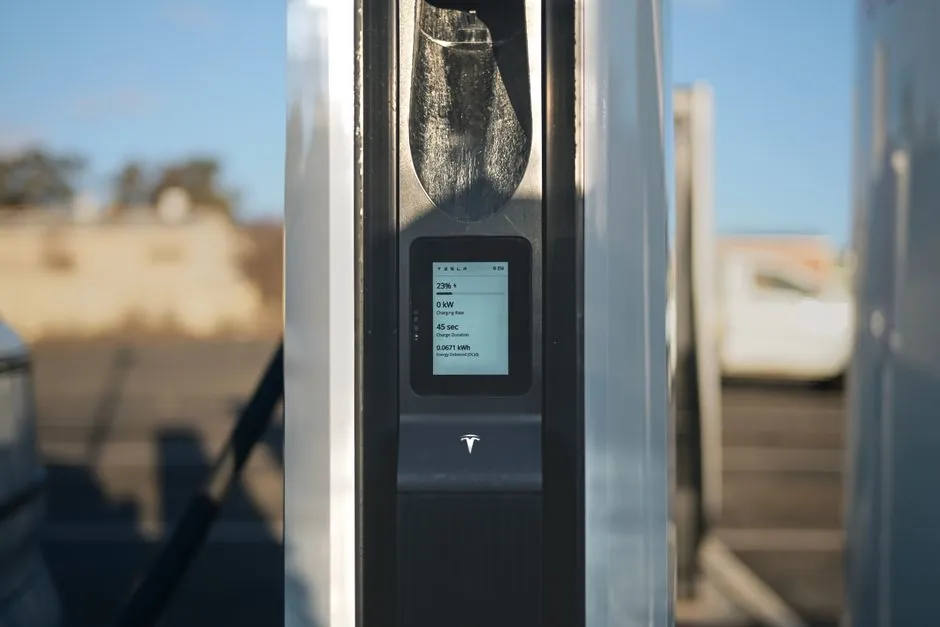
For most AMR fleets, opportunity charging during natural idle windows is the better default, while battery swapping wins when duty cycles are dense, interruption-sensitive, and idle windows are too short to trust. The decision is operational, hinging on shift length, charger placement, battery chemi
Alarm floods occur when operators receive 10 or more alarms in 10 minutes, overwhelming response capacity and burying critical alerts. Primary causes are chattering instruments, process upsets, communication failures, and un-rationalized alarm databases that grow by addition without review. Effectiv
Alarm fatigue in industrial condition monitoring is a design problem, not a sensor problem: 80-99% of alerts on typical monitoring stacks are non-actionable, and the fix is rationalized thresholds, deadbands, prioritization, and AI-based state alarms.
Deep-reinforcement-learning and Transformer-architecture path planners published in 2026 reduce path length to 14.6 m, push success rate to 97.8%, and re-plan smoother trajectories in multi-robot warehouses without specialized hardware. Classical A* and RRT* remain reliable baselines; learning-based
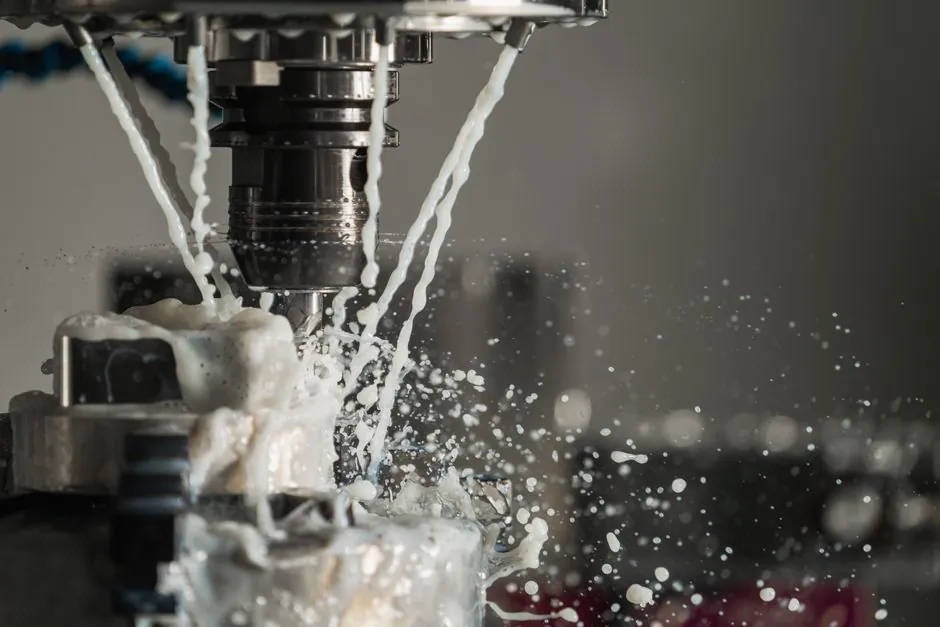
AI-assisted CAM tools now claim 40–80% reductions in CNC programming time across feature recognition, feeds-and-speeds, and toolpath generation, with DELMIA, NX X Manufacturing Copilot, CAM Assist, Lambda Function, and Toolpath as the main 2025 entrants. Shops weighing adoption
AI video analytics for bottleneck and cycle time studies turns existing line cameras into continuous timing sensors, capturing 100% of cycles, sub-60-second micro-stops, and dynamic constraints that manual time studies miss.
AI parameter optimization in injection molding is shifting from DOE and operator experience to real-time machine-learning loops that cut scrap from a typical 3–8% baseline and lift first-pass yield from 85–93% toward higher bands. Adoption is documented across BASF, IMFLUX, Husky, LS Mtron and Chine
AI governance on the plant floor is shifting from policy folderware to documented audit controls in 2026, with the NIST AI RMF and EU AI Act as the dominant reference frameworks. Survey data shows 87% of manufacturers now use generative AI, while only 27% have fully embedded an AI strategy across bu
AI-based production scheduling using deep reinforcement learning typically reduces makespan by 8-15% and tardiness by 10-18% versus static APS heuristics in flexible job shops, per a 2025 review. APS remains the right pick for low-mix, stable plants; AI scheduling wins in high-mix, disruption-heavy
AI-driven load forecasting and scheduling cuts plant energy costs 10–25% and trims MAPE to 1–2%, with generative AI lifting renewable forecasts by up to 25% and BiLSTM-MPC frameworks reshaping virtual power plant dispatch.
Agentic AI work-order systems detect equipment anomalies, generate CMMS work orders in seconds, and cut 60–80% of routine maintenance planning time, per April 2026 industry data.
Machine builders placing AI-enabled systems on the EU market must treat the AI Act (Regulation 2024/1689) as a parallel regime to the Machinery Regulation, with high-risk safety-component AI rules applying from 2 August 2027. CE marking, Annex I conformity assessment, and provider/deployer role spli
Fan and pump shaft power scales with speed cubed under the affinity laws, so a 20% speed cut drops power to roughly 49-51% of full-speed draw, while a throttling valve still pulls 90-95%. VFD speed control on centrifugal loads is the dominant industrial energy-saving lever on that physics.
AFP and ATL split aerospace layup by geometry: ATL runs 75-300 mm tapes above 50 m/min on wing skins, while AFP places 3.2-6.35 mm tows on double-curvature parts at 10-25 kg/h. Aircraft AFP/ATL composites demand hit USD 5.6 B in 2025, with 8.6% CAGR projected through 2034.
Automated drilling and fastening cells for airframe assembly now install up to 21 fasteners per minute and apply up to 18,200 kg of upset force, and they are designed to cut cycle time and repetitive-stress injuries on modern aircraft production lines. A wide-archetype equipment mix covers linear he
APS optimizes multi-constraint production plans over a 1–12 week horizon; MES dispatching executes work orders in real time on the shop floor. Use APS for sequencing, MES for execution, and close the loop with native integration when downtime cost exceeds licensing savings.
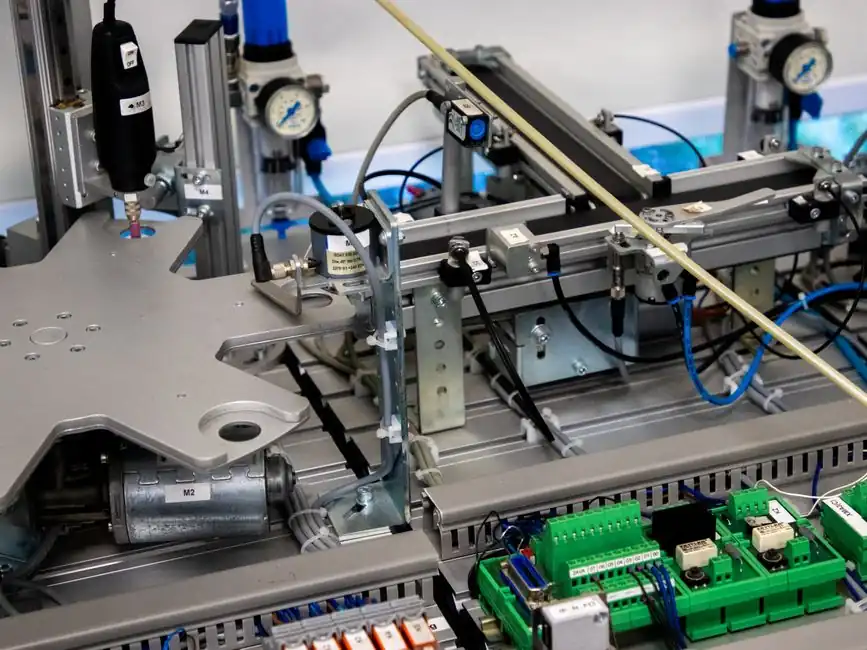
Inline 3D bead inspection of adhesive and sealant dispensing now combines laser triangulation, AI defect classification, and closed-loop robot control to catch width, height, volume, and placement defects at the nozzle in real time. Vision rings from Coherix, Quiss (Atlas Copco), Cognex, and Sciemet
An additive manufacturing production cell co-locates print, depowder, finishing, and inspection stations around a part family so powder-to-part flow beats batch-and-queue on lead time, work-in-process, and floor space. EPA's lean guide and Six Sigma implementation practice both anchor the cell to on
Layer imaging and computer vision detect additive manufacturing build failures in real time, with 2023-2025 research showing FDM warping, delamination, and extrusion defects caught by single-camera CAD-to-image comparison, and powder-bed defects classified by deep learning on per-layer image stacks.
Non-PLC sensor retrofits, including clip-on CT, vibration, and temperature probes feeding edge gateways, now let brownfield plants add OEE and predictive-maintenance visibility in 14 days without modifying control logic. Three viable paths exist: external CT clamps, edge-native overlay gate
5G URLLC marketing routinely quotes the 1 ms air-interface target, but real plant deployments in 2024-2026 still measure 1-10 ms one-way over the air and 5-50 ms end-to-end when PROFINET, PROFIsafe and TSN bridging are included. Engineers should plan deterministic closed-loop control on wired or TSN
Analytics-first digital twins deliver 15-30% productivity gains in year one, while 3D-visualization-first twins risk being "expensive virtual tours" with weak ROI. Selection hinges on pairing the 3D model with IoT, BMS, and CMMS data plus predictive analytics, not on render fidelity.
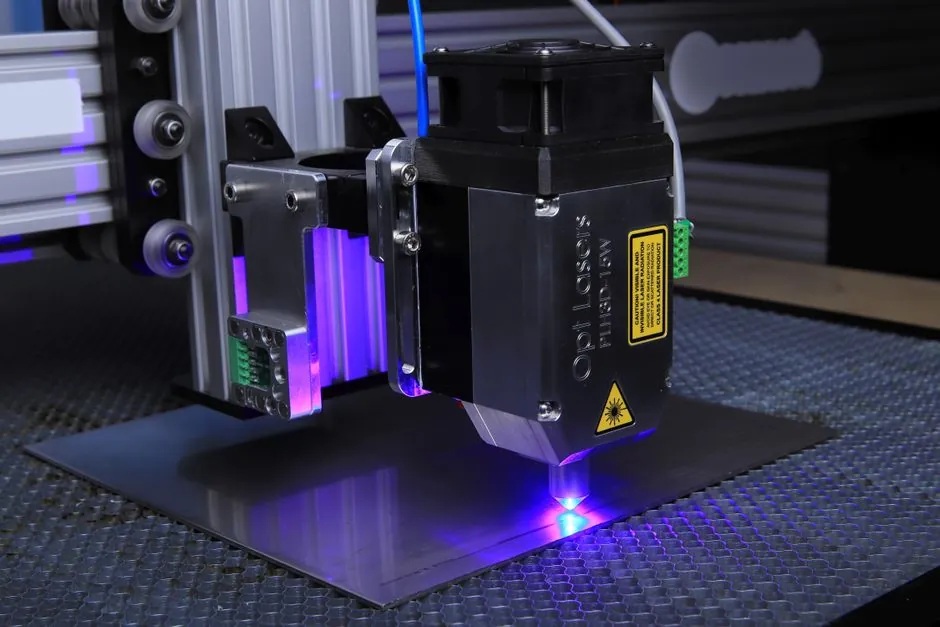
Laser triangulation, structured light, and stereo vision are the three most common active 3D imaging methods on the factory floor, each trading resolution, standoff, motion tolerance, and cost differently. For most sub-millimetre inspection of moving parts, laser triangulation wins on accuracy; for
2D vision systems deliver sub-0.1 mm repeatability on flat, indexed parts at lower cost, while 3D vision is required for stacked, overlapping, or randomly oriented parts where depth data is mandatory; the decision hinges on part geometry, lighting control, and cycle-time budget.
Dielectric cure monitoring measures ion viscosity and dipole relaxation across a 1 Hz-100 kHz AC sweep to track epoxy cure state in real time, with interdigitated foil sensors reaching 2.3% spectral fit error using a five-parameter model. Selection pivots on AC vs DC excitation, sensor geometry, and
Lithium refining to 99.5% purity requires AI-driven process control and online analyzers across calcination, acid roast, leach, purification, and crystallization stages, where reagent dosing, temperature, and pH hold the ppm spec that defines battery grade. With refining now the supply-chain bottlen
FDA 21 CFR Part 11 §11.10(e) requires secure, computer-generated, time-stamped audit trails for closed-system electronic records in life-sciences manufacturing, with retention tied to the record's lifecycle and full availability for inspection.
Wind blade layup automation in 2026 is reshaping per-blade cycle time: AFP/ATL systems now place roughly 2 kg/hr per worker equivalent, while mould cycle for a large blade still runs one to two days, with cycle time gains of up to 50% reported in robotic post-machining steps.
UL Listed is third-party certification with factory surveillance under NFPA and ICC model codes, while CE marking is largely a manufacturer self-declaration under EU New Approach Directives with no "CE certificate" issued for most product categories.
Plants standardize on PROFINET for IT/OT convergence and ecosystem depth; machine builders prefer EtherCAT for sub-millisecond distributed motion, line topology without managed switches, and the lowest deterministic cycle times under high node count.
Additive production lines need a dedicated MES layer because legacy MES was architected for stable, low-mix discrete or batch lines under the ISA-95 Level 3 model, while AM operates with high-mix jobs, geometry-driven scheduling, iterative design changes, and per-build traceability of material batch
Replace an aging PLC at 10–20 years of service or sooner if spare parts are obsolete, software is unsupported, or repair exceeds 50–60% of replacement cost. Documented component-level repair is usually smarter than marketplace "new" spares for legacy Allen-Bradley or Siemens controllers.
The robot arm itself accounts for 25 to 40 percent of a total robotic cell cost, with integration, safety, end-of-arm tooling, and installation making up the remaining 60 to 75 percent.
Category 4 safety circuits under EN ISO 13849-1 require more than dual-channel redundancy: they demand diagnostic coverage ≥99%, well-tried safety principles, high MTTFd per channel, measures against common-cause failure, and single-fault detection before the next demand, with fault accumulation con
A machine builder placing machinery on the EU market must keep an EN ISO 12100 risk assessment, the full technical file, an up-to-date EU Declaration of Conformity, and translated instructions in every member-state language; from 20 January 2027 this sits under Machinery Regulation (EU) 2023/1230, n
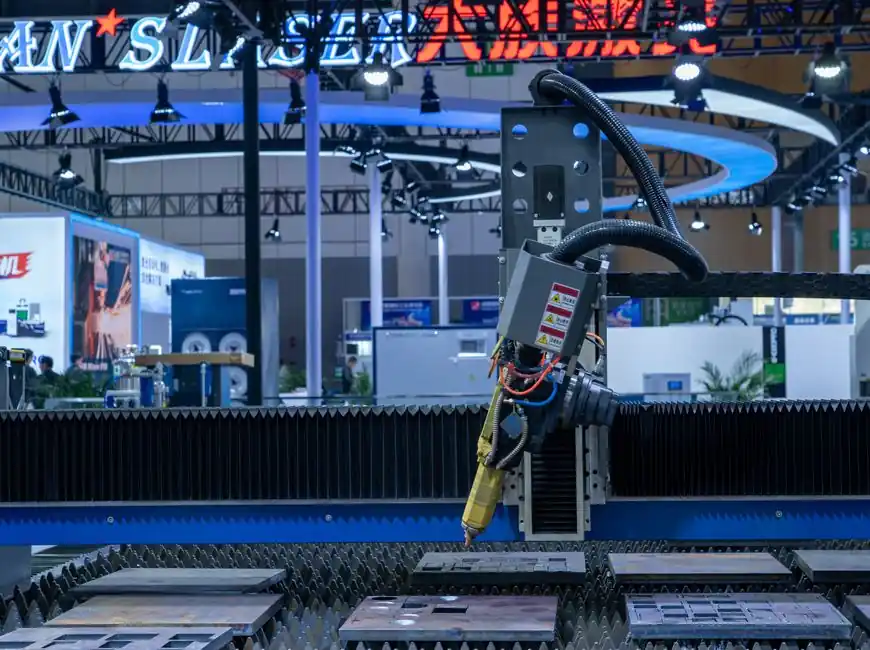
Exporting a CE-marked machine to an NFPA 79 market swaps the legal addressee (operator vs manufacturer), the electrical reference standard (EN 60204-1:2018 vs NFPA 79), and the evidence path (self-declared technical file vs NRTL/AHJ approval), so wiring colors, surge protection, and the documentatio
TOPCon cell yield loss maps directly onto two process blocks: diffusion/anneal and metallization. Wet process non-uniformity is the dominant upstream failure mode, with LPCVD wrap-around, firing-induced blistering, and laser SE alignment as the next-largest contributors.
A CE technical file for machinery is a manufacturer-assembled, no-template dossier per Machinery Regulation Annex VII: design docs, EN ISO 12100 risk assessment, harmonised-standard list, test reports, instructions, and the Declaration of Conformity, kept 10 years after last placement on the EU mark
Phased PLC migration is the safer default for most plants; single-shutdown "big bang" cutover only suits small, well-documented systems with short permissible downtime. Decision rests on lifecycle status, spare-parts supply, engineering depth, and tolerable outage hours per year.
Replace a legacy PLC when a single card failure would halt production; bridge or overlay it when the site needs data visibility, modern I/O integration, or a staged cutover on a live line. The decision is dominated by spares risk, outage window, and network protocol limits, not controller age alone.
For server-board PCBA validation, In-Circuit Test (ICT) typically catches 90–98% of assembly defects in under a minute via bed-of-nails access, while Functional Test (FCT) exercises the powered board through its connectors. Modern lines combine both; the question is where ICT earns its fixture cost
Server assembly line automation now pairs servo-driven fixtured screwdriving cells with vision-guided cable routing to cut cycle time and torque scatter on rack and motherboard subassemblies. A modular mini-robot plus laser foil-strip architecture is the main low-volume/high-mix build pattern, while
SCADA licensing splits into two camps: per-tag/per-seat tiers (VTScada, AVEVA Plant SCADA) and per-server unlimited models (Ignition by Inductive Automation at ~$3,280 start, ~$500/server add-ons). Choose per-server unlimited for tag counts above ~5,000 or when designer/client seats scale unpredicta
Across a 10-year service life, an industrial robot cell's purchase price typically represents 25 to 40 percent of total cost of ownership, with the remaining 60 to 75 percent absorbed by integration, energy, preventive maintenance, and unplanned downtime.

A 1.2 GW automated PV module line runs at roughly 200 modules/hour with single-digit operators per shift on bottleneck stations, while a 150 MW semi-automated line needs about 25 operators per shift at 45 modules/hour. Operator headcount scales roughly with throughput, not with nameplate GW
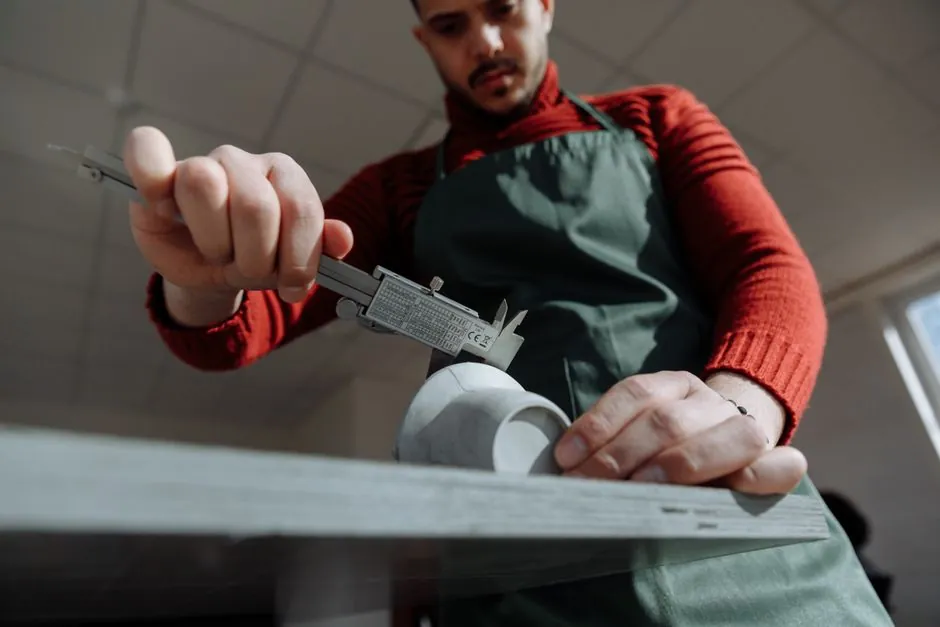
Inline profile extrusion measurement now resolves dimensions to ±0.01 mm at line speeds up to 60 m/min using non-contact cross-section light scanners, replacing contact gauges that only sample at ±0.1 mm. Sheet-of-light and multi-camera systems such as PIXARGUS ProfilControl 7 XLine (launched Septem

PLC scan time and task cycle time are not the same metric: scan time is the measured execution duration of one program pass, while task cycle time is the configured period at which a task is triggered, and a PLC must be configured with the cycle period at least equal to the worst-case scan to avoid

Pharmaceutical line conveyor integration with serialization stations depends on stable product spacing, validated controls, and parent-child aggregation under DSCSA and EU FMD frameworks. Selection criteria split into mechanical handling, vision/print quality, and GMP-grade data integrity. Plan chan
NFPA 660, the consolidated combustible dust standard that replaced NFPA 652 and five commodity-specific predecessors, became effective December 6, 2024 and now drives Dust Hazard Analysis (DHA) reviews, dust-data refresh, and transfer-point controls in U.S. plants handling powders, metals, food, sul
Monopile welding production lines now pair tandem twin-arc SAW gantries (rated up to 12 m diameter, 4000 kg platform load) with motorized fit-up rotators in the 200-2500 t class, and NDT throughput is gated by UT/MT/dimensional inspection on every longitudinal and circumferential seam. Selection hin
Top-tier PV stringers now run 7,000–10,800 cells/hour while holding cell breakage at or below 0.2% on Class A wafers; ultra-thin n-type cells remain the dominant risk factor pulling line yield down.

Module-line OEE typically runs in the 60% range across discrete manufacturing, with availability losses from unplanned downtime and changeovers, performance losses from micro-stops and reduced speed, and quality losses from scrap and rework each contributing roughly one-third of the gap to the 85% w

Mixed EtherCAT and PROFINET plants are routine in 2026 brownfield retrofits, but only when each protocol stays inside its own physical segment and joins at a documented gateway. Cross-protocol bridging through the same cable, shared safety stacks, and unmanaged switches are the three failure pattern

MES wafer-to-module traceability requires per-die and per-board serial binding, not lot-level rollups, to scope field failures in hours rather than 18 months. Modern fabs run 1,400+ process steps where multi-chip modules generate thousands of child data points per lot, so tracking must be forward-lo
Membrane electrode assembly (MEA) yield in proton exchange membrane fuel cells hinges on catalyst-layer coating uniformity: pinhole rates must stay below 0.1%, thickness variation within ±2 µm, and batch loading within ±2% to avoid local hotspot formation and accelerated stack degradation.
ISO 12100:2010 prescribes a four-step machinery risk assessment: define machine limits, identify hazards, estimate risk, and evaluate risk, followed by a fixed three-step risk-reduction hierarchy (inherently safe design, safeguarding, information for use). For EU CE marking, every step must be docum

Battery-grade LiOH·H₂O purification now hinges on two coupled control loops: supersaturation/mixing in the crystallizer and ppb-level impurity rejection verified by ICP-OES. Process data published in 2025-2026 shows ion-exchange pretreatment can pull 90% of Al and 70-75% of Mg/Ca/Na/K/Ni before conv

Liquid-cooled rack leak testing before shipment is a factory-floor gate that combines a pressure-hold visual check per OCP guidelines with a continuous on-site detection layer, typically using sensor cables, leak-sensing wires, and flow/pressure transmitters on every secondary loop.

Inline laser marking stations with vision-verified Data Matrix codes, fiber/UV/CO₂ heads, and OPC UA / MQTT links to MES are the default specification for serialized part traceability on 2026 production lines, with cycle times in the 0.5–8 s range and ISO/IEC 15415 grading.

PV module laminator cycle time, typically 8-25 minutes per module, is the dominant bottleneck on module assembly lines above 50 MW/year. Double-side heating cuts process time 10-30%, and 90-150 second cycles on advanced POE lines keep two-laminator 600 MW layouts viable.

ISO 13849 Category 4 is the only architecture that can claim Performance Level e, requiring dual-channel redundancy, MTTFd of each channel classified as "high", DC avg ≥ 99% including fault accumulation coverage, PFHd ≤ 1.0×10⁻⁸/h, and documented CCF measures. PL e can also be reached via other cate

ISO 10218-1:2025 and ISO 10218-2:2025 replace the 2011 editions, fold ISO/TS 15066 into Part 2, add a two-class robot taxonomy, formalize mobile platform safety, and mandate cybersecurity. Integrators face expanded Clauses 6 and 7 validation against Annex H, mandatory PL ratings per EN ISO 13849, an

Image-based code readers are the practical default for DPM Data Matrix and QR marks, while laser line scanners retain a clear depth-of-field advantage on long, well-printed 1-D labels above ~600 mm read distance. Choose image-based for low-contrast, curved, dot-peened, or laser-etched parts; keep la
Fully automated hydraulic cylinder machining and assembly cells, combining PLC/SCADA control, machine vision, and sensor-integrated cylinders, are moving from pilot projects to standard practice in 2026. Each cell pairs precision CNC turning, honing, and seal-fit operations with robotic assembly and

Hydraulic component end-of-line test stands run 100% verification after assembly, capturing pressure, flow, displacement, and temperature traces into serialized MES records inside line takt. Modern cells use real-time DAQ at 10-300 kHz for closed-loop control and barcode-driven recipe loading.

Human-robot interaction is structured into coexistence, cooperation, and collaboration tiers, with ISO 10218-1 and ISO/TS 15066 as the governing standards for fenceless operation. Selection of a tier depends on shared workspace, task simultaneity, and required safety-rated monitored stop, hand guidi
Damaged and low-contrast DPM Data Matrix codes are best read with 2D imagers using dome or coaxial lighting, 5-15 degree polarised illumination, and tuned exposure. ECC200 error correction recovers 25-30% damage, while ISO/IEC 15415 grade verification sets the deployment threshold for shop-floor tra

PLC code conversion tools deliver roughly 95% functional translation on legacy platforms such as Allen-Bradley SLC 500 and Siemens S5, leaving 5% that demands manual verification. Plan migration with IEC 61131-3 as the target language family and budget 6 to 16 weeks for a mid-size line, with method

NFPA 652 requires a Dust Hazard Analysis (DHA) to be reviewed and updated at least every five years, with the first revalidation cycle landing in 2025 after the September 2020 initial deadline. Triggers for off-cycle updates include new raw materials, process changes, and facility expansions, so the

ISO 7 cleanrooms do not have a one-size-fits-all particle counter count; ISO 14644-1:2015 sets only the particle limits (352,000 ≥0.5 µm, 83,200 ≥1.0 µm, 2,930 ≥5.0 µm per m³) plus 60 air changes per hour, while the number of sampling points and instruments is driven by room area, risk grade, and EU

A 1 GW solar cell and module line typically needs 200-300 direct operators across all shifts, equating to roughly 60-100 operators per shift depending on automation and cell technology mix.

A mid-size PLC migration typically takes 6 to 12 weeks calendar time on a staged brownfield path, or 8 to 16 weeks on a parallel/shadow run, with a one-cell upgrade measured in weeks and a plant-wide modernization extending into many months.

In-situ monitoring for metal additive manufacturing measures melt-pool, thermal, and geometric signatures layer-by-layer inside the build chamber to qualify parts in real time, replacing or trimming downstream CT and destructive coupon testing. NASA funded Phase3D on 2026-04-29 to push in-situ inspe
End-to-end automated assembly for smart devices is organized as a seven-stage workflow, from process design and equipment selection through integration, validation, ramp-up, monitoring, and final QA, with PLCs, vision systems, and MES/ERP forming the digital backbone of the line.

AI server racks are validated through a multi-stage factory acceptance process: 24 to 72 hour burn-in under thermal stress, firmware and network I/O checks, automated optical inspection, and shock/impact monitoring in transit. A single fully loaded AI rack drawing 30 to 100+ kW leaves the integrator
Modular cleanrooms are classified under ISO 14644-1 on a Class 1 to Class 9 scale based on maximum allowable particles per cubic meter, with ISO 5 zones requiring continuous monitoring and ISO 8 typically monitored on a schedule. Compliance follows ISO 14644-2 monitoring, ISO 14644-3 test methods, a

PLC scan time directly sets the floor on machine cycle duration: a 30 ms vs 6 ms scan adds ~2,250 parts/year on a 30 s, six-step cycle. For high-volume discrete lines, dropping scan time is one of the cheapest throughput gains available, since each step transition waits for one or two full PLC scans
3D printing is the only Industry 4.0 pillar that directly digitises fabrication, converting CAD files into physical parts inside a sensor-rich, cloud-connected, data-driven factory. It maps onto nine Industry 4.0 pillars (big data, digital twins, IIoT, autonomous robots, cybersecurity, additive manu

An obsolete PLC can stay in service for 12 to 36 months on a documented bridge plan: battery-backed RAM secured, spares stockpiled, protocol converters installed, and a parallel-rack conversion staged against a planned outage.

SCADA licensing splits into three camps: per-tag, per-seat/server, and all-inclusive. Ignition, FrameworX and iFIX use unlimited or per-server tags, while AVEVA, WinCC and FactoryTalk meter tags, clients or nodes. Match licensing to tag count, client count and growth path, not to sticker price.

Plants connect 3D printers to MES and quality systems by routing the printer's raw data through a vendor-neutral protocol such as MTConnect, then publishing it over REST APIs, OPC UA or message queues to MES, ERP, PLM and QMS platforms that remain the systems of record for orders, released parts and

Offshore wind fabricators digitize weld tracking by tying barcode and RFID identifiers to welding logs, material batch numbers, and inspection records, then binding that data to robot parameter sets, laser seam tracking, and induction preheating controls across monopile, jacket, and floating foundat

Capacity data between plants in collaborative manufacturing networks flows through three layered mechanisms: a cloud-based data collection framework pulling IoT signals, multi-agent platforms translating machine status into shared resources, and a collaboration hub normalizing data across enterprise

Hairpin stator production for EV traction motors now spans fully automated wire forming, insertion, twisting, laser welding, and 3D-scan dimensional inspection, with global market value projected to reach $14.2 billion by 2034 from $4.8 billion in 2025. End-to-end lines from Comau, metrology stacks

In-line green sand testers now measure compactability, moisture, permeability and mould strength in 12-22 seconds at the moulding machine, replacing hand-feel checks and most lab routines. Foundries targeting under 49°C sand temperature, 3% water and consistent bentonite bonding should specify onlin

PEM fuel cell stack production is shifting from manual stacking to automated lines with integrated leak testing, where helium or nitrogen mass-flow testing on 80-500 kW stacks at 1,050 bar capability has become the dominant quality gate. Cycle-time math (1 s/cell at 35k stacks/yr) drives pick-and-pl

Foundries adopting mechanical, pneumatic and microwave sand reclamation report new-sand consumption drops of up to 90%, with digital sensors now monitoring grain fineness, moisture and dust in real time on the sand reclamation unit loop.
DC EVSE end-of-line testing now spans four mandatory gates: SECC/EVCC handshake simulation, multi-coupler parallel runs, AC-DC efficiency/power-factor checks, and OCP/OVP/thermal protection verification. Standard references include IEC 61851-1, IEC 62196, UL 2231, SAE J1772, CHAdeMO, GB/T, and OCPP
EtherCAT delivers 30–100 µs cycle times with sub-microsecond jitter, while PROFINET IRT reaches a 250 µs class A minimum and PROFINET RT sits at 1–10 ms. The decision hinges on servo count, jitter tolerance, and PLC brand lock-in.

Epoxy and polyester batch reactors are converging on real-time viscosity and dielectric endpoints to replace offline sampling, with inline viscometers, NIR/UV-Vis, and dielectric cure monitors each covering a different window of the reaction trajectory. Selection hinges on temperature ceiling, visco
Mixed-SKU end-of-line sortation in 2026 centers on robotic palletizing cells (45% market share, 30-50% labor cost cut) paired with vision-guided sortation, programmable EOAT, and ANSI/RIA R15.06-compliant integration for sustained throughput.

EL imaging combined with visual inspection catches 100% of severe cell micro-cracks and out-of-tolerance Pmax modules at the factory gate, with flash-test Pmax tolerance typically held to +3%/-0% under STC reference conditions.

UL Follow-Up Services require traceable calibration of all IMTE used to verify compliance, but do not mandate an in-house lab; CE marking applies only when a product is placed on the market, with calibration driven by ISO/IEC 17025 traceability and customer-process needs.

ISO/IEC 29158:2025 supersedes the withdrawn 2020 edition and is the current direct part marking (DPM) quality guideline published March 2025 under ISO/IEC JTC 1/SC 31. It grades Data Matrix and QR marks lasered, dot-peened or etched onto metal, plastic or electronic substrates, using modified illumi

A digital twin for wind turbine blade production combines a physics-based blade model with live MES, layup, cure, and CT-scan data to monitor each part during manufacturing. Field examples, including the Aerosense MEMS-based monitoring twin and a University of Hull blade-factory digital twin project

Vacuum-assisted HPDC targets cavity pressure under 100 mbar, frequently much lower for critical parts, before metal reaches the cavity; tight shot-profile control across slow-shot, fast-shot, and intensification determines whether that vacuum actually converts to dense, weldable castings.

An automated die casting cell pairs a die casting machine with coordinated peripherals: dosing furnace, die sprayer, extraction robot, trim press, and part handling. Spray, extract, and trim are the three stations that set cycle time, part consistency, and downstream scrap rate in cold-chamber alumi

Inline IV flash-test at end-of-line is the single most information-dense measurement in a PERC cell line; correlating its seven electrical parameters against upstream process variables lifted top-bin yield from 6.6% to 13.7% over 12 weeks at a 1 GW US foundry.
CE marking and UL listing are not interchangeable for industrial machinery: CE is a manufacturer self-declaration regime under EU directives, while UL is OSHA-recognized NRTL third-party testing, so dual-market equipment needs both. Procurement teams that treat them as substitutes routinely face cus

Wrap-around case packers form corrugated blanks directly around product collations, typically reaching 25–30 cases/min for PET lines and up to 30–140 cases/min on rigid-container and carton lines, while top-load or side-load regular case packers handle wider SKU mixes. Select wrap-around for single-

A case packer installation and commissioning checklist breaks the job into eight sequential gates: site-readiness review, arrival inspection, mechanical alignment, dry commissioning, product commissioning, site acceptance test, training, and handover. Defects caught at FAT cost roughly 1× to remedia

Additive manufacturing cells can run lights-out when automated post-processing covers part removal, support removal, surface finishing and inspection, with the printer rarely the bottleneck, as the post-print step typically consumes 30-70% of total part cost. NASA Ames' FFF in-situ actuator patent a

A digital spare-parts inventory can replace physical spares for a defined subset of low-volume, plastic, and legacy components, cutting carrying costs (20-55% of item value per year) and shortening MTTR from days to hours, but cannot substitute for safety-critical, high-stress, or large metal parts.
Automated bipolar plate lines now combine high-speed precision stamping, fiber-laser welding, and in-line inspection at sub-millimeter tolerances, with cycle times around 45 s per plate, for PEM fuel cell mass production.
Automated PV junction-box potting failures trace to a chain of material, dispense, and cure variables: substrate contamination, off-ratio metering, undercure, and trapped air. Moisture ingress from these defects drives 10-30% of field module failures. Spec the chemistry, the meter-mix, and the inspe

ATEX is the legally binding EU framework (Directives 2014/34/EU and 1999/92/EC) for explosive atmospheres, while IECEx is a voluntary IEC-based scheme accepted across 30+ member countries. Dual-certified equipment is the practical path for process plants shipping globally, though IECEx's unit-verifi

AGVs are the stronger pick for fixed-route heavy loads up to roughly 5.5 tonnes, while AMRs dominate dynamic, human-mixed environments with payloads typically between 0.11 and 2.2 tonnes. The right call is route stability, load, and reconfiguration frequency.
An additive manufacturing qualification data package (QDP) is a Technical Data Package that proves process, material, and part performance for a fixed machine-powder-post-processing chain. For production parts, it must contain machine capability reports, design-of-test-coupon rationale, pedigree mec

Additive Manufacturing Execution Systems (MES) for 2026 bundle build-prep automation, full material and parameter traceability, and post-processing workflow control, replacing paper travelers and spreadsheets across aerospace and medical AM lines. Buyers should weigh features against shop-floor fit:
A 2oo3 (two-out-of-three) voting architecture in SIL3 safety PLCs is preferred for low-demand-rate process industries where PFD matters more than availability. NI C Series modules perform a two-step FPGA vote, and Moore SLA-based HIPPS units can shut wellheads above 8,700 psi.

LiDAR adoption for Industry 4.0 deployments is anchored in centimeter-level 3D point clouds, with the global LiDAR sensor market valued at USD 2.8 billion in 2025, growing to USD 3.2 billion in 2026 at a 13.8% CAGR toward USD 11.7 billion by 2036.

OEM keeps the brand owner in control of design and IP while the manufacturer executes production; ODM flips that, with the manufacturer owning design and the buyer relabelling. For pharmaceutical equipment, OEM typically fits regulated, validation-heavy skids; ODM suits standardised modules and fast

OEM and ODM differ on who owns the product design: OEM means a factory builds to the buyer's specifications while ODM means the factory's existing design is rebranded by the buyer, with ODM cutting development cost and lead time at the price of differentiation. For measuring-instrument buyers, the t
DC fast charger process control hinges on two-stage power conversion (AC/DC then DC/DC) under IEC 61851-23 isolation rules, with current, voltage and temperature sensors forming the primary feedback loop. The 100 kW Level 3 class uses SiC semiconductors and targets 80% charge in under 30 minutes, so

DC fast charger manufacturing quality hinges on three stackable standards: NEVI minimum-port rules (88 FR 12724) for federally funded sites, IEEE Std 519-2014 for grid-side harmonic distortion, and IP-rated enclosures for thermal, dust, and moisture endurance under continuous public use.

Industrial catalyst manufacturers adopting Industry 4.0 are deploying IIoT sensors, AI analytics, and digital twins across reactors and mixers to cut batch variability and energy use. Adoption remains under 30% globally, with workforce skill gaps and capital cost as the top barriers.
DC fast charger manufacturing combines 50-350 kW power-conversion modules, CCS/CHAdeMO/NACS connector assemblies, and OCPP network backends; the U.S. had ~15,000 DC fast sites and 72,000 ports as of May 2026, with Tesla Superchargers (37,000+ ports) and ChargePoint (375,000 activated ports network-w

Warehouse robotics production line design in 2026 centres on three rules: pick-by-decision dashboards over vendor-native consoles, VDA 5050 and ISO 3691-4 as the non-negotiable integration baseline, and end-effector-driven cycle targets in the 4-5 second window for palletising and pick-and-place cel

Data center cooling manufacturing now sits at the intersection of ASHRAE thermal guidelines, EPA SNAP refrigerant rules under the AIM Act (85% HFC phasedown by 2036), and UL/IEC/ICT safety certification, with water quality and corrosion control defining the build-quality bar.

Ferrochrome Industry 4.0 adoption is constrained by electricity cost and Chinese competition, with a 30-year South African roadmap deferring full digitalization to phase 2. The global FeCr market is projected at USD 22.83 B in 2025 to USD 30.61 B by 2032, CAGR 4.28%.

ODM EV charger projects deliver a certified 7kW AC wallbox in 4-8 weeks with MOQ 50-200 units, while true OEM takes 10-16 weeks plus 3-6 months of pre-production engineering and $15k-$80k tooling. Pick ODM below ~1,500-3,000 units/year per SKU, OEM above.

Industrial laser production line design in 2026 hinges on matching five process stations (positioning, cutting, cleaning, marking, welding) to throughput, footprint, and laser safety class, with line-laser positioning, multi-head cutting, and galvo marking forming the dominant architectural pattern.
Polypropylene resin producers are scaling Industry 4.0 stacks to defend 4.1–4.4% CAGR growth, with the global market tracked at US$91.77Bn (2025) heading to US$129.50Bn by 2033. Digitalization now sits at the centre of synthetic resin plants, from live process analytics to closed-loop extru

OEM and ODM represent two distinct outsourcing routes for industrial Ethernet hardware: OEM keeps design and IP with the brand owner while the partner builds to spec; ODM lets the manufacturer own the reference design and IP, and the customer rebrands or lightly customises. The right pick hinges on
The global machine vision system market reached $29.7 billion in 2019 and is projected to hit $74.9 billion by 2027 at an 11.3% CAGR, driven by Industry 4.0, automotive mass production, and healthcare automation at a 15.3% CAGR.
E-axle manufacturing quality hinges on three end-of-line gates: NVH acoustic screening, efficiency/torque mapping, and high-voltage safety per IEC 61851/IEC 60664. Test cells must cover up to 440 kW per wheel, support 24/7 takt-time operation, and integrate COP audits. For a deeper look at the equip

LNG manufacturing equipment spans liquefaction trains, cold-box heat exchangers, and storage tanks built to ASME BPVC Section VIII. Spec gates for 2026 cover −162 °C service, NACE MR0175 metallurgy, and API 620/2510 storage rules.
Electrolyzer manufacturing equipment selection hinges on matching stack technology (PEM, alkaline, SOEC) to power electronics, BoP, and assembly tolerances. For green-hydrogen builds, spec the rectifier, plate-coating line, and NDT equipment for pressure-bound bipolar plates first, then size the res
Steel production routes split into BOF and EAF paths, with continuous casting feeding hot-rolling mills that turn billet into plate, section and strip; downstream pipe lines add HF welding, anti-corrosion and ultrasonic testing.

LNG plant cost is dominated by liquefaction trains, cold-box brazed-aluminum heat exchangers, and full-containment storage tanks; instrument-layer spend on pressure transmitters and flow meters is a single-digit share of total installed cost. Buy-side 2026 sourcing data shows magnetostrictive LNG le
Molybdenum producers in 2026 are wiring sintering presses, warm flow-forming cells and AM powder lines into ISA-95/MES stacks, cutting scrap roughly 10-20% versus manual recipe control. The fit is mid-to-high volume refractory metal plants; job shops below 50 t/yr rarely recoup the integration cost.
Industrial CPU process control and instrumentation PLCs now spec at minimum 500 MHz with 16 Mb integrated program memory, 0.08 µs bit operations, and battery-free FEPROM backup per current IC general-spec guidance. PCB structures still link the OS scheduler to those control loops.
Designing a rare-earth production line in 2026 centers on solvent-extraction separation trains targeting up to 99.999% REE oxide purity, with single-pass column flowsheets replacing legacy mixer-settler cascades. Spec priorities include non-toxic solvent chemistry, three-year-plus maintenance interv

An AI accelerator flows through three manufacturing stages — design on EDA tools, wafer fabrication at a fab, and advanced packaging — before being assembled into a data-center accelerator card; NVIDIA shipped 1.5–2 million H100 units in 2024 and holds an estimated 80–95% AI chip market share.

Nickel manufacturing quality in 2026 hinges on three standards stacks: industrial ASTM/ASME material specs for pipe and alloy, REACH/Oeko-Tex 100 for skin-contact consumer goods, and ISO 9001-linked QMS platforms connecting first-article to supplier inspection. Buyers should match the spec stack to
Server hardware in Industry 4.0 plants is now chosen for OPC UA, PROFINET, and time-sensitive edge-compute loads, with AI/ML workloads being absorbed by the same physical servers via dedicated metamodel layers. Specifiers should fix the platform as edge node plus centralized historian, not as a gene

EV charging station manufacturing spans sheet-metal fabrication, PCBA, power-module integration, and final burn-in across China-based OEM lines; output runs from 7 kW AC units to 360 kW DC fast chargers, with customization options on housing material and dimensions confirmed by Saipwell. Proces

Semiconductor manufacturing equipment (SME) covers front-end wafer processing and back-end packaging lines, governed by SEMI E137 packaging/relocation and SEMI E35 COO metrics, with the 2025-2032 market growing from USD 166.35B to USD 344.36B at 11.0% CAGR.

Battery Management System (BMS) manufacturing combines cell monitoring ICs (1.2 mV resolution, 0.1% accuracy), protection firmware, and balancing circuitry (passive vs active) on PCBs that meet ISO 26262 ASIL-C/D for automotive or functional-safety targets for 12-48 V stationary packs, with MathWork
Wind turbine manufacturing quality is governed by grid-code power-quality tests, IEC 61400-series design rules, and OEM smart-factory systems; LVRT/UVRT, harmonic compliance, and blade/tower tolerances are the binding gates for 2026 builds.

Primary nickel (Class I) cost stack runs ore-to-refined-metal at roughly US$16,000–22,000/t on the LME benchmark, with laterite HPAL feed, sulfidic matte flash smelting, and NiSO4/cathode-active precursor chemistry each adding distinct cost lines that procurement and process engineers must separate

OEM solar panel contracts run on buyer-supplied specs and tight cost control; ODM contracts hand design ownership to the factory for faster SKU launch. Pick OEM when you own the bill of materials and certifications; pick ODM when speed-to-market outweighs IP control.
OEM builds to your design, ODM ships the factory's existing design with your label; in petrochemical procurement the gap is who owns the process IP, who carries the certification risk, and who is liable for the pressure transmitter trace.

SCADA systems anchor smart manufacturing by linking PLCs, sensors, and MES layers into a single supervisory loop across power, water, and discrete plants. As of mid-2026, vendors are layering agentic AI on top of legacy SCADA stacks to convert dashboard data into prescriptive guidance rather than ad
ABS plastic smart manufacturing now pairs injection moulding cells with MES, IIoT sensors and AI-driven process control, lifting OEE on consumer-goods lines while cutting scrap below 1% on well-tuned 80–1600 tonne presses.

Taiwan's SAA is collaborating with the Industrial Development Bureau to codify PCB Industry 4.0 standards, while SMEs remain the slowest adopters. Cyber-physical production, IIoT, and digital twin stacks are now the dominant reference architecture for greenfield PCB lines. Engineers sourcing for new
Chinese lithium-battery makers continued to expand cell and pack capacity in 2025-2026, with Azure Corporation alone targeting ~700 million cylindrical cells annually, a 48-acre Malaysian plant green-lit, and new municipal consumer-cell projects in Liaoyuan. Output gains concentrate in LiFePO4, Li-p
Industrial refrigeration plants are absorbing Industry 4.0 controls at the cell and line level in 2026, with 97% of surveyed APAC manufacturers naming digital transformation a priority and roughly 60% of large firms explicitly targeting sustainability through IIoT and AI tools. Smart manufacturing h
Renishaw Central, Rockwell FactoryTalk and Applied SmartFactory are reshaping how smart meters, energy monitors and metrology assets stream process data into closed-loop control on the factory floor in 2026.
CNC machine production technology covers the full stack from mechanical frame and spindle design to multi-axis control, with Chinese OEMs leading woodworking and aerospace segments, UK and EU integrators handling turnkey cells, and pricing for entry CNC tooling machines starting around US$7,200.

AI server production lines run as dual-track systems pairing electronics assembly with liquid-cooling integration, with leading ODMs standardizing 27-35 process steps, 2000W+ titanium-grade PSUs, and helium leak rates under 1×10⁻⁹ atm·mL/s. For an automatic molding line-style repeatable layout, plan

EV traction motor manufacturing is a four-part assembly flow—rotor, stator, body/inverter housing, and control unit—now scaling on flexible shared lines with hairpin winding, axial-flux architectures, and additive-manufactured components cutting copper/iron content.
Hydraulic system production technology in 2026 centers on five building blocks: cylinders, motors, pumps, valves, and power units, with cylinder honing tolerances commonly held to 0.01-0.03 mm and piston pump ratings climbing past 420 bar in mobile machinery.

Offshore wind foundation production lines balance throughput, weld quality, and logistics for monopile, jacket, and floating substructures. Targets of 380 GW by 2030 and 2,000 GW for net-zero are pushing steel-pile diameters from 3.5–6 m into the 8–10 m range and water depths past 50 m toward 100 m,

Polypropylene resin is made by polymerizing purified propylene monomer in gas-phase or liquid-phase reactors, then after-treating and pelletizing the polymer. Slurry, solution, gas-phase fluidized-bed, and stirred-reactor routes dominate the global installed base.
Rolling-element bearing production combines forged ring forging, CNC grinding, heat treatment, and raceway superfinishing into a 200+ step flow; key material, tolerance, and process decisions determine whether a ball bearing or roller bearing meets ABEC/P0-P6 accuracy classes and ISO 15:2017 boundar

A humanoid robot manufacturing process spans reducer/actuator build-up, joint assembly, full-stack integration and on-site pilot deployment; the 23-DoF Unitree G1 (~35 kg, US$13.5K) and UBTech Walker S1 at Foxconn anchor the 2025-2026 industrialisation curve.
Additive manufacturing covers seven core process families — FFF, SLA, SLS, MJF, DMLS/SLM, PolyJet and binder jetting — each with distinct material bands, dimensional tolerances and cost-per-part profiles. FFF, SLA and SLS dominate the service-bureau mix; PAEK-grade FFF and DMLS cover serial producti
Wafer fab equipment (WFE) covers 15 main silicon-wafer manufacturing tools and the FEOL/BEOL process chain, with the 2024-2029 market growing USD 34.7 B at 6.2% CAGR across 7 nm-and-below to 65 nm-and-above nodes.
Copper cathode (≥99.99% Cu) is made by two routes — pyrometallurgy (ore → concentrate → smelt → anode → electrolytic refining) and hydrometallurgy (oxide ore → leach → SX → electrowinning) — with LME-grade cathodes typically 0.5–1 m², 3–20 mm thick.
OEM in pneumatic system sourcing means the buyer owns design, drawings and tooling while the factory only manufactures; ODM means the factory owns an existing design and the buyer rebrands it. Use OEM for proprietary IP, custom pneumatic cylinder geometry or regulated builds; use ODM for fast market

Copper production capacity planning ties cathode output, scrap feed, and SX-EW line debottlenecking to a quantified tonnage target, with site selection governed by LME pricing, acid availability, and reagent balance. Process engineers should size electrowinning cells, anodes, and tankhouse current d
Desalination plants sized 50,000–500,000 m³/d now adopt ISA-95/88-aligned smart-manufacturing stacks, with reverse-osmosis high-pressure pressure transmitters, Ethernet-APL flow meters and CIP-skid smart valves forming the core automation layer per industry guidance.

LNG Industry 4.0 adoption is driven by cryogenic valve digitalization, IoT condition monitoring on LNG trains, and systems-theory frameworks for SME supply chain financing, with operational gains centered on cryogenic industrial valve reliability.

Silicon wafer quality is governed by SEMI standards (M1, MF84, MF523) covering geometry, surface, and particles, with 300mm prime wafer diameters now mainstream. Reclaim and test/dummy wafer segments add specification layers for cost-effective reuse. Spec-driven sourcing, not brand, is the practical

PVC resin (polyvinyl chloride) is polymerised from vinyl chloride monomer (VCM) via free-radical chain growth, with K-value (60–68) and polymerisation temperature (45–72 °C) defining the grade family SG-1 to SG-8. The S-PVC process dominates global supply; additives (CPE-135A, AIM-50, Ca-Zn stabilis
Specialty chemicals manufacturing relies on a formal process specification (工艺规范) that locks down route, equipment, parameters, and inspection, with plants clustering around logistics hubs such as Katoen Natie's 350,000 m² Saint-Martin-de-Crau site. Vendor service models (Wesmar-style) add on-site t

Electric motors consume roughly 40% of global electricity and 69% of industrial electricity, with over 30 million new industrial units sold each year; Industry 4.0 adoption in motor manufacturing and drive systems is now centred on data-driven remanufacturing, IEC 61800-9-2 efficiency-class reportin
Modern CPU bill of materials splits across silicon wafer, EUV lithography, advanced packaging and test, with packaging and test now rivaling wafer cost on leading-edge nodes.

Cobalt cathode-active material typically accounts for roughly 5–15% of a battery cell's manufacturing cost stack, with hydrometallurgical processing, energy and labour being the dominant line items per Nature Energy 2018 cell-level data, while extraction-pyrolytic routes offer a low-volume recycling
Kolkata-based distributor Machine Tools Centre lists 40+ instrument categories from 30+ brands, covering pressure, temperature, level, flow, and weighing lines for machine-tool and process plants. Brands include Honeywell, Wika, Pepperl+Fuchs, SMC, and Mitutoyo. Service scope spans selection, calibr
An EV charging station production line assembles enclosure, power module, control PCB, and HMI stages on a modular conveyor with RFID traceability, balancing cycle time, ISO 15118 communication, OCPP backend integration, and end-of-line safety tests per UL/IEC norms.

Machine vision systems use industrial cameras, optics, lighting, controllers and image-processing software to automate inspection, measurement and robot guidance in manufacturing. AI-powered edge vision now supports EtherNet/IP, PROFINET, OPC-UA and trains defect models in under an hour, reshaping f

Fiber laser cutting machine manufacturing cost spans $15,000 for a 1kW entry unit to over $600,000 for a 20kW-plus production line. The 2026 cost stack is driven by laser source wattage, working area, automation level, and the laser cutting head plus CNC control package, with gas and electr
Commercial Level 2 EVSE hardware runs $1,500-$5,000 per port and installed costs land at $3,000-$12,000 per port, while DC fast charger projects reach $80,000-$250,000+ per unit; the main cost drivers are power electronics, certification, electrical service upgrades, and software/networking stack, w
Laser cutting capacity planning is a production-cell problem, not a wattage problem: machines, operators, software, consumables, extraction, loading, unloading and downstream processes must be sized together. Output depends on cycle time, nesting, material mix, automation level, and the chosen plann

Designing a compressed air production line requires matching CFM and PSI demand to compressor type, then layering ISO 8573-1 air treatment, ring-main distribution, and receiver storage per AS 1210, with energy savings of 20-50% achievable through right-sizing and pressure-drop control.

PVC resin plants are typically scoped at 100,000-200,000 MT/year, with a downstream pipe line built on a twin-screw extruder, vacuum calibration tank, haul-off, and cutter stack. Three polymerization routes (suspension, emulsion, bulk) feed the same compounding chain that drives global PVC demand pr
Kontron opened a Düsseldorf production line on 2026-07-15 for automotive and industrial 5G M.2 modules, with FRMCS rail modules as a target. Industrial 5G LAN targets 10–16 ms latency, 4–8 Mb/s uplink per HD camera, and 100–1,000 devices per hall.

For SCADA system buyers, the OEM path delivers full IP control and brand differentiation at higher cost, while ODM gives a turnkey, faster-to-deploy platform built on the manufacturer's design IP; the right pick depends on customization depth, certification burden, and in-house integration capacity
An industrial gearbox quote breaks into 8 line items, with raw stock at 20-30%, gear machining and finishing at 25-35%, bearings at 10-18%, and heat treatment at 8-15% of unit cost. End prices span $300 for light-duty worm units to over $250,000 for custom-engineered parallel-shaft and planetary gea

EV charging stations in 2026 run on a tiered DC fast-charging architecture (Level 2 AC to 350 kW+ DC), with process control centred on grid-side PFC, three-level NPC converters, and ISO 15118-compliant vehicle-to-everything (V2X) signalling. Standards like IEC 61851, ISO 15118, and UL 2231 govern sa

Industrial filter manufacturing quality is governed by ISO 9001 quality management, ISO 14001 environmental management, and ISO 16890 air filter classification, with CE and UL marking for market access. Buyers should verify raw-material traceability, in-process checkpoint testing, and end-of-line ef

OEM and ODM are the two dominant manufacturing routes for warehouse robotics; OEM keeps design and IP in-house while ODM trades those for lower upfront cost and faster time-to-market. The right pick is dictated by load class, navigation stack, and software-integration depth, not by label alone.

EV charging station manufacturing quality hinges on layered compliance: GB/T 18487.1-2015 and GB/T 20234.3-2015 for DC hardware, OCPP 1.6 for backend, plus ETL/CE/UKCA/TUV/CB certifications, with burn-in testing and 10,000-cycle connector life as baseline QC gates.
Specifying AI accelerator manufacturing equipment in 2026 means building a 9-station tool chain from EUV lithography through CoWoS packaging, with EUV scanners above USD 200 million and CoWoS throughput now the binding supply constraint for sub-5 nm accelerator dies.

Compressed air lifecycle cost is dominated by energy: 70-80% of total spend across vendor estimates, while the hardware itself is only ~10%. A 100 hp rotary-screw at 80% load splits as electricity 70%, leaks 20%, maintenance 5%, auxiliaries 5%, and producing 1,000 scf runs roughly $0.25-$0.30.

LiDAR sensor production capacity planning in 2026 centers on three signals: separating nameplate from demonstrated throughput, mapping calibration-station bottlenecks before adding lines, and qualifying a contract manufacturer with synchronized multi-site capacity (Benchmark runs 20 facilities acros

EV charging station production capacity planning pairs a demand model (charger count, kVA, fast/slow mix) with a queueing/optimization solver. Peer-reviewed work in 2024-2026 reports 4-5% total cost reductions over baseline models using simulated annealing versus genetic or ant-colony methods.
Activated carbon manufacturing is governed by ASTM D-28 standards (iodine number D 4607, hardness, ash, moisture, density), ISO 9001:2015 QMS, NSF/ANSI 61 for drinking water, AWWA B604, EN 12915, and Food Chemicals Codex for food grade. Buyers should require certificates and verify them independentl

5G industrial modules are now the connective tissue between IT and OT on the factory floor, enabling URLLC-grade control with 1-10 ms latency, 99.99% reliability, and up to 10 Gbps throughput. This guide covers module types, manufacturing equipment, standards, and selection criteria for spec-driven

JEDEC finalized HBM4 in April 2025, lifting per-stack bandwidth to 2048 GB/s and doubling the interface to 32×64-bit channels, while yield-driven wafer-level test is now the manufacturing gating factor for HBM3E and HBM4 stacks. Three vendors, SK Hynix, Samsung, and Micron, control supply, with TSMC

RV reducer manufacturing quality hinges on cycloidal-gear profile tolerance, pin-gear concentricity, and bearing accuracy grade, with the RV-40E study (2025) confirming virtual-prototype tolerance optimization. Standard RV-E production lines run broaching, whirling, and grinding stations in series.

Industrial catalyst manufacturing relies on a five-stage equipment chain: support formation (pelletizing/granulation), impregnation/coating, drying, calcination, and bulk material handling. Selection hinges on support material (alumina, zeolite, silica), required morphology, and throughput. Rotary k

Industrial Ethernet cable selection for plant floors is governed by IEEE 802.3 electrical performance layered with IEC 61918 environmental severity ratings; shielded Cat6A (S/FTP, 500 MHz, 100 m channel) is the practical baseline, with PUR jackets, IP67 M12 connectors, and double-layer shielding (≥8

Rebar manufacturing equipment splits into two tracks: hot-rolling mills (1-35 t/h, 8-32 mm bar) for mill-scale producers and CNC cut/bend/thread lines (10-40 mm rebar) for fabrication shops. Match kit to capacity, stock length, building power, and bar grade.

OEM vs ODM for e-axle programs is a make-or-buy decision driven by IP ownership, MOQ, and lead time. OEM buyers carry $50K–200K+ in tooling and 20–30 week lead times; ODM partners cut upfront cost to $5K–30K with 8–14 week lead times but surrender base design rights.
Activated carbon plants built around 10,000 to 20,000 MT per year hit the economic scale, with coconut shell feedstock driving 50 to 60% of OpEx and 35 to 45% gross margins. PFAS, microplastics, and VOC rules now mandate granular activated carbon treatment across municipal and industrial sites.

Collaborative robots (cobots) are six-axis force-limited arms designed for shared workspaces, with a global market projected to reach $7.5B by 2027, roughly 29% of the industrial robot segment. Selection hinges on payload, reach, ISO/TS 15066 power-and-force-limiting compliance, and application fit.

Humanoid robot programs use OEM and ODM routes very differently: OEM means the brand owns the full design and the factory only fabricates, while ODM means the supplier also owns kinematic architecture, BOM, and control stack. On a 2026-09-12 spec view, ODM wins on speed and cost for buyers entering
Second-generation eAxle production lines in 2026 are built around a cell-and-line hybrid architecture that pairs a shared robotic main line for common processes with dedicated manual cells for model-specific assembly, enabling multi-variant output on a single line. End-of-line test benches such as t

Industrial LiDAR procurement starts with five binding constraints: application, range, field of view, environment, and interface, all of which must be resolved before comparing vendor datasheets. 2D vs 3D, indoor vs outdoor, and AMR-grade vs survey-grade units diverge enough that a single spec sheet

E-axle unit cost sits in a $2,500 to $7,000 band, driven mainly by the PMSM or induction motor, power electronics, and the choice of single- versus multi-speed gearing, with the largest swing factors being motor power class and housing manufacturing route.

Immersion cooling instrumentation for single-phase data center tanks centers on a dielectric fluid loop where ultrasonic/radar level, RTD temperature, differential pressure, and electromagnetic flow meters feed the CDU, with PID control holding coolant within a few degrees of the target setpoint.
UPS system purchase price represents only 25–40% of total cost of ownership; battery chemistry alone drives 30–50% of the bill, and kVA rating dictates the largest absolute spend, from $300 for sub-3 kVA standby units to $250,000+ for 100 kVA+ online double-conversion systems.

An instrument data sheet (IPDS) is the master technical record tying a tagged measurement or control device to its process service, calibrated range, materials, accuracy, and hazardous-area certification, and is developed by the process engineer then refined by I&C. Standardised forms (ISA-20-1981 l

For linear guide rails, OEM means the buyer owns the CAD and tolerances while the factory machines to print; ODM means the supplier owns the rail/carriage platform and the buyer rebrands an existing design. Choose OEM for proprietary machines and IP control, ODM for faster market entry at lower upfr
Liquid cooling instrumentation in data centers now spans flow, pressure, level, leak and analytical sensors tied to industrial PLCs, with hyperscalers drawing 1.5–3 million gallons of water per day at 100–300 MW facilities. Control architecture selection, not sensor choice alone, drives uptime in AI

Wafer fab equipment is two distinct tool chains: ingot-to-wafer substrate manufacturing (crystal growth, slicing, lapping, CMP) and front-end chip patterning (lithography, etch, deposition). The combined WFE market is projected at USD 166.35B in 2025, growing to USD 344.36B by 2032 at an 11.0% CAGR,

HBM3e is in high-volume production with 1024-bit interface, 16 channels, and over 1.2 TB/s per stack; HBM4 doubles that target to 2.0 TB/s using a 2048-bit wide I/O. Manufacturing equipment centered on TSV etch, copper-fill deposition, ALD, and hybrid bonding is the gate.

E-axle production capacity planning now hinges on cell-and-line hybrid systems, modular EOL testbeds rated to 440 kW per wheel, and super-vertical integration that has cut supplier development lead times to 1.0-1.5 years. The reference plant cadence for 100 axles per shift is a 4.5 min cycle on a 45
OEM pneumatic actuator sourcing puts design, tooling and certification burden on the buyer with 60 to 120 day lead times and USD 3,000 to 30,000 mould cost; ODM inverts that, with the factory owning an existing 30 L/min-class platform, MOQs as low as 100 units, and 15 to 45 day first-article deliver

An AI accelerator production line is the union of a 300 mm wafer-fab cell, an HBM/2.5-D advanced-packaging cell, an SMT-assembly cell, and a burn-in test cell, and the 2026 design problem is dominated by reticle-limited die area, chiplet partitioning, and on-prem vs hybrid compute placement rather t
Industrial gearbox manufacturing quality is governed by AGMA and ISO standards covering gear geometry, heat treatment, and load rating, with ISO 9001:2015 quality management and AGMA 2001-D04, 6013-B16 as the core references. Buyers should match service factor, material grade, and inspection regime
Pneumatic actuators remain the dominant final-control element driver in process plants, converting a 3-15 psi (0.2-1.0 bar) or 4-20 mA-derived air signal into linear or rotary motion for valves and dampers. Spring-return, double-acting, rack-and-pinion, and scotch-yoke topologies cover roughly 90° q
Building an e-axle production line at Tier-1 scale in 2026 means hitting ±5 µm stator concentricity, ±0.1 mm hairpin placement, G2.5 rotor balance, and USMCA 75% RVC, all under IATF 16949 dual with IRA Section 45X sourcing. Plan a 240,000-unit/yr greenfield around PMSM + integrated e-axle + SiC inve

Cutting tool production line design hinges on five interlocking factors: tool geometry, tool material, workpiece material, machine forces, and process conditions. Specifiers should size chip space, rigidity, and force components together rather than picking a tool first.

Polysilicon procurement is a control-vs-speed decision: OEM (buyer-owned design, slower, higher upfront) suits cell-makers chasing differentiated roadmaps, while ODM (supplier-owned design, faster, lower NRE) suits private-label or quick market-entry buyers. Choose by IP ownership, tooling cost, and

Industrial automation software manufacturing quality is governed by ISO 9001:2015, ISO 16100 interoperability profiling, and ISA-95/MES-SCADA architecture, with mid-2026 platforms from SafetyCulture, MasterControl, and Plex priced at $24-30/seat/month starting tiers.
Raw materials dominate industrial coatings cost at up to 70% of total spend, with binders, pigments, and solvents the main price drivers. Total cost of ownership hinges on formulation time, batch size, lead time, and maintenance savings that often reach 30% or more with functional coatings.
An EV traction motor production line is purpose-built around hairpin stator welding, PMAC rotor magnet loading, and slot/winding automation, with optical encoders providing 1 nm resolution and ±40 nm SDE for end-of-line rotor-position calibration.
A 10,000-50,000 MT/yr zinc ingot plant is the standard capacity envelope for greenfield builds in 2026, with 15-25% gross margins tied to galvanization, die-casting, and brass demand. Global market sits at 12.27 MT (2025) on the way to 15.63 MT by 2034 at a 2.7% CAGR, while 12.0 MT of mine output in

A 316/316L stainless steel coil siphon is the default process-control interface for pressure transmitters on steam and high-temperature lines, sized PN20 with 1/4" male/female fittings and priced around €22.88 list. Selection pivots on service fluid, temperature, and number of helical turns, typical
OEM vs ODM in industrial coatings splits on who owns the design IP: OEM clients control every spec (resin, pigment, substrate prep) while ODM partners retain design architecture and supply a private-label formulation. Pick OEM for differentiated, specification-driven systems (corrosion, anti-static,
Stainless CR coil plant OpEx is 80–85% raw materials and 10–15% utilities, with 15–25% gross margin; 304 coil base price sits at $2,400–$3,400/ton across US, China, and EU in May 2026. Cost drivers rank: nickel, cold-rolling passes, precision tolerance, and tariff overlay.

An EV traction motor's manufacturing cost is dominated by raw materials (electrical steel, copper, NdFeB magnets), with magnet and copper often reaching 40-55% of bill-of-materials and assembly/test adding another 30-40% of factory cost.

Activated carbon OEM vs ODM manufacturing splits on who owns the design IP: OEM builds to the buyer's drawing (coconut-shell or coal-based carbon, specified iodine number, mesh size) for brand control, while ODM lets the supplier supply an existing cartridge or pellet platform for faster launch. Act

Industrial refrigeration manufacturing equipment is built around four core stages: compression, condensation, expansion and evaporation, with screw chillers now mainstream for 24/7 industrial duty. Selection hinges on refrigerant type, load profile, ambient conditions and maintenance access.
Industry 4.0 adoption in the EV traction motor market, valued at USD 17.12 billion in 2025, is shifting from pilot-scale digitalization to full production-line integration, with PMSM, BLDC, and induction motor architectures being optimized via IIoT, machine learning, and edge analytics. Decision-mak
An industrial fastener production line covers wire-rod receiving, cold heading, trimming, thread rolling, heat treatment, and packaging, with design choices governed by fastener type, batch size, and torque-quality targets. Lines built on modular stations and measurable per-stage standards out-perfo

Global industrial robot reducer demand is projected to grow from $3.8B in 2025 to $8.1B by 2034 at an 8.8% CAGR, with the RV reducer segment holding a 38.5% type share and Asia Pacific accounting for 58.3% of revenue. Nabtesco disclosed a 2025 capacity expansion at its Tsuyama plant in Japan an

Zinc ingot process control now relies on a layered architecture spanning melting-furnace temperature loops, automated slag-handling robotics, and constant-volume ladle dosing into casting lines. Sensors track zinc-liquid level, melt temperature around 419-430 C, and dross formation, with PID and fuz

EV traction motor process control hinges on field-oriented control running in a sub-10 kHz control loop, with resolver/encoder feedback and SiC inverter switching at 20–100 kHz. Calibration of current, voltage, and rotor-angle sensors drives torque ripple and efficiency.

A properly engineered welding robot production line integrates robot, positioner, fixture, welding source, seam tracking, and offline programming into a single workcell, with modular layouts and two-axis turntables as the dominant configuration for arc welding of sheet metal.

Capacity planning software now anchors discrete and process manufacturing scheduling, with lead, lag, and match strategies tied to MRP/SCADA/ERP data flows. Modern tools integrate demand forecasting, real-time resource monitoring, and AI-driven what-if analysis to balance labor, machine hours, and i

Global EV traction motor demand rises from 27.4 million units in 2025 toward 87 million by 2035, with PMSM holding 59.4% of 2025 value and Posco tripling motor-core capacity to 7 million units per year by 2030.
A 10,000-30,000 MT/year lithium carbonate production line built on spodumene feed at 6 wt% concentrate running 27 kta of battery-grade product, with soda-ash precipitation, DLE brine bypass, and Metso's one-pass refining option now defining the 2026 plant-design baseline.

Offshore wind foundation OEM and ODM models split on three pillars: design authority, IP ownership, and time-to-market; OEM suits differentiated monopile/jacket IP, ODM suits faster series builds of catalog transition pieces.

Lithography system cost is dominated by the scanner class: I-line steppers $5M-$15M, KrF $20M-$40M, ArF immersion $40M-$60M, and EUV around $120M-$200M per unit. Total market value: $30.4B in 2026, 9.6% CAGR to 2033.

Molybdenum manufacturing equipment spans concentrate-roasting kilns at 1,500–1,800 mm diameter, single-chamber sintering furnaces to 1,400°C with 6.67×10⁻⁴ Pa ultimate vacuum, and DFARS-compliant precision etch lines for aerospace, electronics, and energy parts using a 2,623°C-melting refractory met
OEM vs ODM in fluoropolymer manufacturing hinges on design ownership: OEM keeps the part drawing and IP client-side (longer lead, higher tooling, full material/standard control), ODM lets the supplier's existing PTFE/PFA/FEP platform carry the part (faster, lower MOQ, shared IP). Most 2026 procureme
Immersion cooling production lines combine sealed dielectric tanks, coolant distribution units (CDUs), brazed plate heat exchangers, and 19-inch rack-standard server baskets to absorb heat from AI/HPC loads exceeding 500 kW per rack, with dielectric fluids from suppliers such as Evonik enabling heat

Industrial refrigeration Industry 4.0 adoption centres on AI-driven monitoring, IoT sensor layers, and predictive maintenance, cutting the 20% sector electricity load documented in 2025. Adoption is real but uneven, with framework research flagging capability gaps, integration cost, and the need to

Offshore wind foundation manufacturing cost is driven by raw steel tonnage, fabrication capacity, and specialized installation vessel day-rates. Fixed-bottom foundation CAPEX is on the order of £43,000/MW for secondary steel and connectors, with floating substructure reaching £1,313,000/MW. Installa

EV traction motor manufacturing equipment centers on stator winding, rotor assembly, and end-of-line testing, with four process types (insertion, needle, segmented, flyer) selected by slot geometry and production volume. The segment is set to grow to USD 183.29 billion by 2034 at a 30.58% CAGR, driv

Tungsten manufacturing quality standards center on ISO 9001, ISO 14001, AS9100, REACH and ROHS compliance, paired with material specs like 99.95% purity and 19.25-19.3 g/cm³ density. Procurement decisions should verify documented certifications and batch-level test data before awarding orders.

Industrial fastener buyers face a fork between OEM (buyer-owned design, full IP, higher upfront engineering) and ODM (supplier-owned design, faster lead times, lower tooling cost). The right pick depends on tolerance class, alloy, thread standard, lot size, and whether the program needs the full des
Global tungsten mine output reached 85,000 metric tons in 2025, with China supplying 67,000 t (~80%) and ex-China projects projected to add roughly 20 kt WO3 by 2030, reshaping defense and industrial supply planning. APT prices quadrupled to $340/kg WO3 by July 2026 under export controls and tight c

Offshore wind foundation process control and instrumentation centers on structural monitoring, foundation SCADA, and pile-driving sensors that protect roughly 25-33% of project capital cost tied to the support structure. Selection hinges on measuring natural frequency, fatigue, and scour while navig

Edge computing gateways sourced via OEM or ODM in China are the dominant path for industrial buyers, with the practical split turning on design IP ownership, BSP support depth, and certification experience rather than label alone. For a 50-unit pilot scaling to 10,000 units, OEM fits when the buyer

Offshore wind foundation manufacturing in 2026 hinges on ISO 19902, EN 1090, and ISO 12944 C5-M, with 100% volumetric weld inspection and splash-zone corrosion rates above 0.3 mm/year driving buyer specification. Foundation cost now sits at ~30% of project capex on turbines exceeding 15 MW.

Zinc ingot production relies on five equipment tiers, with induction furnaces supplying melt at 420–500°C, ingot casting machines running 50–108 mold cavities, and PLC-controlled stacking/leveling stations. The 2026 global zinc market sits near $30B with 3–4% annual growth, making process-grade equi

Offshore wind foundation manufacturing equipment in 2026 spans monopile, jacket, and floating substructure production lines, with 205 GW of capacity targeted globally by 2030. Selection centers on water depth, turbine rating (12–20 MW), and welding/NDT throughput. Major capex risk is serial producti

Machine vision systems are now a core input to AI-driven capacity planning, with manufacturers using them to raise OEE, cut forecast error to under 5%, and lift throughput by around 25%.
Wind turbine gearboxes are produced under two distinct sourcing models: OEM builds to the turbine maker's design and IP, while ODM lets the gearbox supplier own the design and lets the buyer rebrand. The choice changes who holds IP, who carries the certification load, and how fast a fleet can be sta

Wind turbine gearbox production line design centres on a 3-stage planetary/helical drivetrain rated around 6 MW, a torque density of 200 Nm/kg, and end-of-line test benches instrumented with fiber-optic strain sensors validated against IEC 61400-4 and AGMA 6006. Geared drivetrains still cover about

A utility-scale wind turbine gearbox typically absorbs 8 to 10 percent of construction cost, with materials (case-hardened gear steel, bearings, housings) and machining/grinding time driving the largest line items. Total cost of ownership is dominated by lifetime O&M, since gearbox replacement event
Wind turbine gearbox suppliers are layering IIoT condition monitoring, digital twins, and predictive maintenance onto planetary and helical drivetrains, with the global market projected to climb from $11.34 B in 2025 to $17.73 B by 2035 at a 4.57% CAGR.

Wind turbine gearbox process control and instrumentation centers on drivetrain-mounted sensors, SCADA-integrated vibration/oil/temperature channels, and condition-monitoring logic that targets planetary and high-speed stage wear. Mature deployments combine flowmeters, pressure transmitters, and ther
Wind turbine gearbox manufacturing is governed by IEC 61400-4:2025 (replacing the withdrawn 2012 edition) and ANSI/AGMA 6006-B20, both covering enclosed speed-increasing gearboxes above 500 kW. Quality gates include 1/100 mm tolerances on 4 m+ ring/sun/planet gears, ISO 6336 contact-fatigue calculat

Wind turbine gearbox capacity planning now hinges on 10-12 MW class units, with ZF's SHIFT platform clearing 10 GW of shipped offshore capacity with Vestas and a 30 MW validation rig live for next-generation powertrains. Lead times for replacement gearboxes are the single largest O&M swing factor, s

Wind turbine blade OEM vs ODM hinges on four spec-driven axes: design ownership, IP retention, capex/lead time, and post-sale fire-safety liability. OEM suits brand-driven platforms above 3 MW with strict design IP; ODM suits cost-driven 1.5-3 MW retrofits where the buyer accepts platform designs.
Wind turbine blade production line design hinges on integrating bend-twist-coupled aerodynamics, flatback airfoils, and composite layup automation. A 2023 techno-economic model in Renewable Energy links labor, material, overhead, and business costs into a single ROI tool, enabling line changes to be

Wind turbine blade manufacturing cost is driven by materials at 35–40%, labor and overhead at 25–30%, and tooling/equipment depreciation, with a single 60 m onshore blade priced between USD 150,000 and USD 250,000. Larger blades and carbon fiber reinforcement raise costs sharply, while transport, to
Industry 4.0 adoption in wind turbine blade production centers on AI-assisted defect detection exceeding 90% accuracy, additive manufacturing for blade tooling at USD 1.2B in 2024, and digital-twin inspection frameworks across the USD 32.68B 2025 global blade market. The 12 m AM scale ceiling and ab

Wind turbine blade process control pairs strain, load and acoustic-emission instrumentation with adaptive pitch-torque loops running on Paris-crack / particle-filter life models. Annual O&M runs about USD 17,000 onshore and USD 46,000 offshore, so the spec map is shaped by sensor density, loop bandw
Wind turbine blade manufacturing is governed by IEC 61400-5:2020 and DNV-ST-0376, with APQP4Wind and PPAP gating serial production. Expect 3-6 month approval windows and up to 3 years from spec to series production for next-generation offshore blades over 100 m.
Wind turbine blade production is scaling toward 15–26 MW turbines with blades up to 153 m, forcing capacity planners to solve transport, cycle-time, and composite-process bottlenecks. The 2025-2035 blade market is projected at 20.5% CAGR, with India, Turkey, and China absorbing most new lines.
Wind turbine blade manufacturing equipment spans mold layup stations, resin infusion setups, autoclaves, root-end orbital mills (achieving ±0.15 mm flatness) and tower-flange milling machines. Modern land-based blades exceed 52 m and offshore blades reach 107 m, driving capital tooling investment in

For grid-scale battery storage, OEM contracts typically amortise above 1,000–5,000 units with a 6–9 month safety-test cycle, while ODM reference platforms ship in 4–8 weeks from 50–200 packs and ride existing UN38.3, IEC 62619, and UL 1973 reports. Pick OEM when BMS firmware, IP, and a proprietary c

Grid-scale BESS production lines in 2026 converge on 280–314 Ah LFP prismatic cells in 20 ft or 40 ft ISO containers wired to 1500 V DC, with line builders publishing 6–10 containers/day capacity, ±0.02 mm weld repeatability, and 99% equipment-side yield targets as the engineering baseline.
Grid-scale battery storage procurement now requires Industry 4.0 platforms with 100-500+ MW scope, LFP chemistry at 6,000-12,000 cycles and 90-93% round-trip efficiency, 5 MWh-class containerized blocks running 2C charge/discharge, and IEC 61850 plus Modbus TCP communication to integrate with utilit

Grid-scale BESS manufacturing in 2026 centers on LFP prismatic cells in 280-314 Ah, 1.5-6 MWh DC blocks on a 1500 V bus, and certification gates including UL 1973, UL 9540A, IEC 62619, and IEC 62933-2-2.

Grid-scale battery storage capacity planning for 2026 grids sizes systems as 4-hour duration LiFePO4 containerized blocks from 2.4 MWh to 50 MWh per unit, modularized to 100 MWh+ with 1000V/1500V DC architecture, sub-20 ms response, and 6000-cycle LFP cells.

Grid-scale BESS manufacturing equipment is built around eight metrics, UL 9540/9540A/1741 plus IEEE 1547, and a line stack from coating to PCS, with prismatic modules landing at 6–8 PPM and 18.8 m × 3.57 m footprints.

For commercial B2B energy storage buyers evaluating China-based partners, the OEM vs ODM choice in BESS manufacturing is an engineering decision, not a branding decision. OEM builds to the buyer's spec, while ODM owns design, architecture, BMS/PCS integration, and certifications. The right pick depe

DOE launched the Storage Design STEP Prize on 2026-07-14 to push production-readiness into next-generation storage designs, while BESS assembly line builders are standardizing module and pack workflows around IEC, UL, and ISO compliance. Greenfield plant economics now demand BESS, thermal, and flywh

BESS installed cost in 2026 spans roughly $100–$700/kWh depending on scale and chemistry, with battery cells driving 50–65% of total spend, LFP now 20–30% cheaper than NMC, and utility-scale LCOS at $210–$292/MWh.

Energy storage system Industry 4.0 adoption in 2026 pairs AI-driven battery management with digital-twin analytics on a market projected to grow from USD 39.2 billion in 2026 to USD 226.2 billion by 2035 at a 21.5% CAGR, anchored by LFP cells below USD 120/kWh and roughly 10.9 GW added in Q3 2025 al

Battery energy storage systems rely on four coordinated control layers: cell-level BMS, bidirectional PCS, plant-level PPC/EMS, and integrated EIS monitors. Specification hinges on power-rating, duration, and real-time comms like Modbus TCP.

Prismatic lithium battery module and PACK assembly lines for energy storage systems now run at 12 to 22 PPM with 99% yield, spanning 587Ah large-format cells, 314Ah liquid-cooled modules, and 50-314Ah flexible lines. This guide maps process stages, throughput ranges, and equipment classes for BESS a
OEM and ODM both build TOPCon solar modules, but they sit at opposite ends of the IP axis. OEM is a make-to-print contract under the buyer's locked BOM, while ODM ships a pre-engineered reference module the buyer re-labels. Pick the model by four gates: cell IP, IEC 61215 / IEC 61730 certificate hol

TOPCon cell manufacturing cost in 2026 is driven mainly by silver paste, n-type wafers, and LPCVD/PEALD passivation capex, with non-silver metallisation and wafer thinning the two largest cost-reduction levers remaining. The articles below provide a complete cost-stack breakdown plus a capex/opex co

TOPCon 4.0 cell technology reached 26.33% certified efficiency on 333.4 cm² N-type wafers and 735 mV open-circuit voltage in 2023, with commercial modules at 575-585 W and 440-460 W now shipping for utility and residential use.

TOPCon solar cell lines running at 24.5–25.5% commercial cell efficiency rely on tight control of the n-type tunnel oxide (~1–2 nm) and phosphorus-doped polysilicon rear stack, with LPCVD/PE-poly, ALD-AlOx, and PECVD-SiNx as the critical process-control nodes. Front efficiency now exceeds 25.00% on
India's MNRE added high-efficiency TOPCon and HJT cell models to ALMM List-II on 21 Aug 2026, while global TOPCon cell capacity hit 400 GW in 2025 at $0.08–$0.12/W manufacturing cost and 85% technology share, reshaping new-fab capex decisions across 2026 planning cycles.

Solar glass OEM vs ODM is a tooling-vs-catalog trade: OEM locks your design IP and your mold (typical $300–$1,200 tooling fee for a hand-blown shade mold, ±1.5mm fitter tolerance), while ODM rides an existing factory catalog for a 4–8 week launch. Pick OEM for unique BIPV cover glass and BC module f
Solar glass production lines in 2026 are spec'd around three decision gates: rolled-pattern hot end at 1200-1260 t/d with ±1°C roller control, BIPV/laminated cold end at ±0.3 mm assembly accuracy and 99% yield, and continuous tempering at 3-5x batch capacity. Match line type to glass thickness and e

Solar glass Industry 4.0 adoption is accelerating in 2026, with AI-driven cutting, optical cullet sorting, and float-line automation cutting scrap rates and lifting throughput. Solar PV glass demand is forecast to grow from 32.24 million tons in 2026 to 75.08 million tons by 2031, an 18.42% CAGR, re

Solar glass process control relies on a float-line architecture: tin-bath O2 at 0.5–2 ppm, lehr ±2 °C, ribbon pull 600–1,200 m/h, tempering at 620–680 °C, and AR-coat transmittance gains of 1.5–2.5 points. Control hardware crosses into standard industrial transmitters, flow meters and IPC-based temp

Solar cover glass for PV modules is a low-iron (≤120 ppm Fe2O3), tempered soda-lime sheet, supplied in 2.0–4.0 mm grades with ≥91.6% light transmission (≥93.6% with AR coating) and qualified to EN 12150, IEC 61215, and IEC 61730.

A solar glass manufacturing line combines hot-end forming (rolling machine, 1.2–4 mm, up to 600 t/d) with cold-end processing (cutting, grinding, tempering per EN 12150:2000). Equipment selection is driven by glass thickness, ribbon width, and module format (c-Si vs thin-film).
Solar module OEM contracts in 2026 price monocrystalline product at US$0.07–0.11/W with 18,000 W MOQs on 565–580 W half-cell lines, while ODM runs the same watt class with 2–4 week lead time on factory-owned reference designs. Choose OEM for locked BoM and proprietary certification, ODM for channel

Solar cell production line design in 2026 centers on a 22-station turnkey architecture, baseline 25 s/pcs cycle time, 98% uptime, and multi-format cell compatibility (G1/M6/M10/M12 plus PERC/TOPCon/HJT/IBC). Capacity tiers scale from 60 MW pilots to 1.2 GW gigawatt lines, with capital ranging from U

Solar cell manufacturing cost is dominated by polysilicon refining and wafer slicing, with silicon purity (sub-ppb for critical dopants) and energy-intensive purification setting the floor price. Cell technology choice (PERC, TOPCon, HJT) shifts 10-25% of total cost between silver paste, deposition,

PV Industry 4.0 module lines in 2026 standardize on three equipment blocks (AI dark-crack inspection, laser cell cutting, robotic EVA layup), with 182-210 mm TOPCon/PERC wafers, 0.1-0.3 mm EL resolution, and 140-155°C lamination windows defining the spec envelope.

PV cell-line process control stacks four measurement nodes: irradiance reference (ISO 9060 Class A pyranometer), cell/module electrical test (IV + EL + Class AAA flash per IEC 60904-9), thermal loop (K-type TC at 320-420 °C), and lamination (0-1013 mbar vacuum, 140-160 °C EVA). Furnace-side tools in

Turnkey solar module production lines now scale in clear tiers from 60MW semi-auto at USD 1.7M up to 1.2GW fully-automatic gigawatt lines at 2.4-3.0MW draw, with 300-500MW emerging as the standard core-line capacity for new regional factories. Cell compatibility has converged on M10/M12 wafers suppo

Solar cell manufacturing equipment for 2026 production lines covers glass loading, laser cutting, tabber-stringer, layup, lamination, EL/IV testing, and palletizing, with mainstream suppliers (Ooitech, Argus Solar, Xinology, FLSolar) offering 5MW–1GW turnkey cells supporting G1/M6/M10/M12 and PERC/T
Solar inverter OEM vs ODM manufacturing splits cleanly on who owns the R&D: the brand owns it under OEM (Original Equipment Manufacturer) and the factory owns it under ODM (Original Design Manufacturer). The right pick depends on your team, lead-time tolerance, and certification budget, not on unit

A solar inverter production line built around 50 modules and 22 stations can replace roughly 40 headcount per double shift, with CCD positioning, RFID traceability, and an integrated SMT front end sized for 800 to 1,500 components per residential inverter board.

Solar inverter manufacturing cost in 2026 breaks down into IGBT/magnetics BoM (40-55%), assembly and test labor, enclosure/thermal hardware, SG&A and warranty overhead, with finished inverter pricing running $0.10-$0.25/W across string, micro, and hybrid types per public benchmarks. Tot
Solar PV inverters are shifting from simple DC/AC conversion to grid-forming, IIoT-connected units, with the global market projected to grow from USD 15.24 billion in 2026 to USD 21.16 billion by 2031 at 6.79% CAGR, per Mordor Intelligence.

Solar inverter process control centers on MPPT, a closed-loop control function that measures PV voltage and current to keep the array at its peak I-V product. Sizing is Vmp/Imp-based, dual-MPPT is only useful under asymmetric array conditions, and DC street lights do not need an AC inverter.
Solar inverter manufacturing quality standards in 2026 hinge on IEC 62109 safety, IEEE 1547/UL 1741 grid interconnection, IEC 61000 EMC, and EN 50549 EU rules, with QC depth (conformal coating 50–75 μm, RoHS SMT lines, 2-second anti-island disconnect) separating industrial-grade from consumer-grade
Sizing solar inverter production capacity requires a load-study-first approach, not nameplate summation. For factories, capacity is typically driven by the 60–600 kVA industrial energy storage inverter bracket, with string (10–100 kW) and central (megawatt-class) topologies covering 50 MW+ utility p

A solar inverter manufacturing line typically integrates 22-28 workstations across 50-70 modules, combining SMT PCB assembly, automated screw locking, CCD vision, and aging tests. Process parameters anchor at 250°C ± 5°C soldering, 5-10 Nm torque, and 2-4 second joint time, with a 40-headcount savin

Electrolyzer production line design in 2026 targets GW-class capacity with laser-based alkaline turn-milling and PEM/AEM modular stack lines, 1 s/pcs bipolar-plate cycle at ±0.1 mm tolerance, and full ERP-MES-SCADA integration on unmanned workshops. Key constraints are bipolar-plate handling precisi

Electrolyzer CAPEX is dominated by the stack (bipolar plates, membranes/electrodes, and catalysts) plus power electronics and BoP. Global manufacturing capacity is 61 GW with 16 GW under construction (2026-03), and unit cost tracks PEM's precious-metal load versus alkaline's localisation play, with
Electrolyzer production capacity planning in 2026 hinges on modular stacks of ~500 NL/h cores scaling to MW range, with Enapter's EL 4 AEM unit at 1.0785 kg/24 h and chlor-alkali skid cells spanning 50-2000 g/h chlorine output as reference benchmarks.

Green hydrogen production line design in 2026 centers on modular PEM and alkaline electrolyser skids sized from under 1 Nm³/h R&D units to 200 Nm³/h containerized stacks and 120 MW gigawatt-class plants, with BoP, rectifier, and water-treatment integration governed by project scale and renewable pow
Green hydrogen LCOH sits at $4.50–$6/kg in Europe and $4.70–$6.65/kg in India, against grey at $1.50–$2.50/kg. Cost is driven 60–70% by renewable power price and the rest by electrolyser capex, currently $750/kW target by 2030.

Green hydrogen remains under 1% of global H2 output, but EU 2026 auctions cleared 4.3 GWe and alkaline electrolyzers hold a 66.6% share. Industry 4.0 adoption hinges on flow, pressure, and DCS integration that cuts LCOH toward $5.84/kg.

Green hydrogen flow and pressure control in PEM/AEM electrolyzers is production-critical, with PEM differential pressure windows as tight as ±20 to 50 mbar and water feed conductivity below 1 µS/cm. Digital DCS layers with predictive analytics have demonstrated up to 20% energy-cost reduction, direc

The Green Hydrogen Organisation (GH2) defines green hydrogen as electrolysis-based H2 with ≤1 kg CO2e per kg H2 averaged over 12 months, requiring renewable electricity, water treatment, and impurity control per the 14-contaminant hydrogen purity rule.

Fuel cell stack OEM vs ODM is a build-versus-buy decision driven by IP ownership, tooling cost, and time-to-market. OEM suits proprietary stack designs with full design control; ODM fits catalog-based stacks for fast entry with shared IP. For a PEM stack project, OEM engineering runs $10k–$50k plus
Automated fuel cell stack production lines for graphite and metal plate stacks deliver stated first-pass qualification rates ≥98%, stacking positioning accuracy of ±0.1mm, and press accuracy around 0.2-1% FS, with capacities of 2 stacks/h to 1000 units/year. Selection hinges on stack format (air-coo

Fuel cell stack Industry 4.0 adoption in 2026 centers on digital stack monitoring, automated BOP control, and ISO 14687 hydrogen-quality gates for megawatt-scale systems. Buyers should map IIoT telemetry, real-time cell-voltage monitoring, and H2 purity instrumentation before specifying power class,

Fuel cell stack production capacity planning in 2026 hinges on three sizing decisions: stack electrical envelope (50 W to 25.6 kW per unit), BOP catalyst and reformer feed path, and the integration of pressure, flow, and temperature instrumentation. Specs span PEMFC, MCFC, PAFC, and SOFC chemistries
Fuel cell stack manufacturing equipment spans modular assembly lines with 2–1000+ stacks/year capacity, servo-hydraulic presses with ±0.5% FS pressure repeatability, and MES-integrated stations. Selection pivots on stack power class (0.5–10 kW air-cooled vs 20–300 kW liquid-cooled), alignment accura

OEM and ODM battery management system manufacturing diverge on three decisive axes: design IP ownership, time-to-market, and upfront tooling investment. OEM suits buyers who own the BMS firmware and want full IP control (6-12 month cycles); ODM fits buyers who need pre-certified platforms in weeks,

Modern BMS (Battery Management System) PACK production lines are configured as 15- to 16-station modular automated systems with 90-120 day delivery, ±1 mV cell sorting, 500-2000 W laser welding, and 99.5% uptime. Lines must serve cylindrical, prismatic, and pouch cells with full MES traceability.

The global battery management system market is valued at USD 11.55 billion in 2026, on track to USD 24.17 billion by 2031 at a 15.94% CAGR, with the US segment expanding from USD 1.34 billion in 2024 to USD 2.83 billion by 2029.
A Battery Management System (BMS) is the electronic control unit that monitors cell voltage, current, and temperature in real time, estimates State of Charge and State of Health, balances cells, and protects lithium packs from overcharge, deep discharge, and thermal runaway. The BMS sits between cel

Battery management system manufacturing quality hinges on validating each BMS against protection thresholds (overcharge, over-discharge, balance, temperature, short-circuit) before pack dispatch, on a six-step line that ties cell matching to BMS validation, and on chemistry-specific limits such as t

Battery management system (BMS) production capacity planning anchors on three numbers: kWh target per platform, cell-format share, and GWh-per-line output the equipment stack can sustain. With prismatic cells growing at an 8.4% CAGR and global EV battery demand forecast at USD 103.04 billion in 2026

For 2026 battery electrolyte programs, OEM suits buyers who already own electrolyte IP and need recipe confidentiality, while ODM fits teams that need a turnkey cell-to-pack partner with a qualified electrolyte on the shelf. Choose by IP ownership, scale, certification scope, and time to first gram.

Battery electrolyte production lines split into three engineering tracks in 2026: oxide solid-state lines (10 t/day, 150–800°C dual-zone), sulfide solid-state lines (oxygen-/moisture-controlled), and liquid-electrolyte preparation (LiPF6 salt, EC/EMC/DMC solvents) under dry-room dew-point control. C

Battery electrolyte manufacturing cost is dominated by LiPF6 salt, high-purity carbonate solvents, and additive packages, with dry-room dew point, moisture spec, and certification scope acting as the second-order price drivers.
Battery electrolyte Industry 4.0 adoption is now driven by tighter purity gates (water under 10 ppm, HF under 50 ppm), solvent reformulation for sub-zero operation, and solid-state scale-up. Procurement specs, not chemistry breakthroughs, are the gating factor for 2026 cell makers.

Li-ion electrolyte filling process control centers on a dry room at -40 to -60 °C dew point, ≤20 ppm electrolyte water, and ±0.5% volumetric filling accuracy with 10⁻⁶ mbar·L/s leak acceptance across cell formats.

OEM and ODM models for battery separators split on design ownership, tooling cost, and lead time. OEM suits buyers with proprietary coating IP and high-volume repeat runs; ODM suits fast market entry using the factory's existing separator design and catalogue line.

Lithium-ion battery separator makers are layering Industry 4.0 controls onto wet and dry film lines, with the EV separator segment alone reaching USD 5.67 billion in 2026 and inline ceramic coating forecast to grow at 20.6% CAGR through 2031, driving demand for inline defect inspection and digital t

Ceramic-coated polyethylene and polypropylene battery separators must hold defect rates under 10 ppm in mass production, with coating uniformity within ±2 µm and dual-band terahertz inspection emerging as a non-destructive QC method, while U.S. effluent rules under 40 CFR Part 461 govern process was

Putailai is adding 7.2 billion m²/year of lithium battery separator capacity in Qionglai for a 5.6 billion yuan outlay, while Jinlongyu is building 1,550 t/year of coated separator lines and a 2-micron base film plant has broken ground in Shandong, reshaping domestic separator supply through 2028.
A wet-process Li-ion battery separator line runs asynchronous biaxial stretching at 105 m/min, delivers 5–25 µm diaphragms up to 6800 mm wide, and pairs with separator coaters and slitter-rewinders for ceramic or PVDF coating. Line cost is dominated by oven count, MD/TD stretch ratio, and tension-co

Anode material production line design splits into three distinct equipment families in 2026: zinc-electrowinning anode plate lines, lithium-battery graphite roasting trains, and aluminum anodizing lines. Spec bands differ sharply, with rotary kiln throughput at 12-16 t/day versus anodizing 100-5000

Anode material cost is driven by feedstock grade (titanium, high-purity graphite, Al/Zn/Mg alloys), coating chemistry, certifications (ISO, NACE, DNV, RoHS, REACH), and geometry. Spec bands for Li-ion anode powder show 300–420 mAh/g capacity, 0.9–1.25 g/cm³ tap density; sacrificial Al anodes carry Z

Anode material Industry 4.0 adoption is shifting from pilot MES/SCADA rollouts to data-driven PSD, tap-density, and SEI-stability control, with silicon-carbon, hard-carbon sodium-ion, and pre-lithiated SiO lines being qualified under tighter 2026 spec windows.

Anode-material process control in 2026 hinges on a few measurable nodes: 100 S/cm SOFC anode conductivity, 40–60 vol% Ni-YSZ cermet window, 1200–1800°C sublimation-furnace zone, and 0.01–1000 Pa vacuum with ±0.5 mm plate flatness for non-ferrous anodes.

OEM cathode manufacturing means build-to-print against buyer-owned cell specs, while ODM is a faster, reference-platform route on supplier-owned designs: choose OEM when you control the chemistry IP, and ODM when UN38.3, IEC 62133, and a 5–100 kWh reference pack already on file matter more than 6–9

Cathode material production lines split into two distinct design families: battery CAM lines (LFP, LMFP, sodium poly-anion, ternary) running solid-state sintering, jet-mill classification and wet coating; and electrolytic metal-cathode lines (Cu, graphite) running electrode handling, electrolytic ce

Cathode material manufacturing cost is driven by five line items: precursor chemicals, calcination energy, atmosphere and moisture control, particle sizing, and certification. Exact figures vary, but specification, sourcing, and process discipline set the order of magnitude.
Cathode Industry 4.0 adoption centers on three measurable shifts by August 2026: NCMA quaternary grades hitting 225 mAh/g first-cycle capacity at 99.9% purity, YS/T 1868-2026 codifying solid-state cathode specs effective 1 November 2026, and 4th-gen LFP reaching ≥2.60 g/cm³ compaction dens
Cathode material process control in 2026 hinges on tight co-precipitation and calcination instrumentation, with the North America market alone projected to grow from USD 4,680.2 million (2025) to USD 7,162.7 million by 2030 at an 8.9% CAGR. Inline pH, ORP, moisture, and spray-drying feedback loops a

Cathode material quality standards now center on a tiered qualification framework that ties LFP/NCM carbon-coating metrics, trace-metal limits, and PAT-grade spectroscopy to specific acceptance criteria, with Epsilon's Gen 3.0 LFP (159 mAh/g, 2.51 g/cc) cleared for global cell-maker validation as of

Global lithium-ion battery cathode material production capacity is being re-planned around 5 TWh of new cell gigafactories under construction, with LFP capacity additions targeting 240,000 t/yr by 2028 and China holding 85-90% of cathode and anode active material output.

Cathode material manufacturing equipment selection hinges on matching mixers, coaters, calenders, and dry rooms to four chemistry families: LFP, NCM/NCA, LCO, and sodium-ion layered oxides. Pilot lines typically run 50–500 kg/batch, while GWh production targets electrode defect rates below 0.5%.

For solid-state battery programs in 2026, OEM suits buyers who already own cell IP and a pack design, while ODM fits teams that need a turnkey cell-to-pack partner. Semi-solid lines dominate current scalable output, and full SSB remains in pilot. Use the decision matrix below to pick the right engag

Solid-state battery production lines replace liquid-electrolyte filling with solid-electrolyte film forming, composite cathode mixing, and stacking-based cell assembly. Samsung SDI targets H2 2027 mass production from its Suwon pilot; CATL rates its own programme at 4 of 9 on the technology-readines
Semi-solid-state batteries are now in mass production in China in 2026, with the broader EV solid-state market valued at USD 542.3 million and growing at 46.1% CAGR through 2035. Industry 4.0 adoption remains limited to early pilot lines, with silicon-anode lithium-ion cells absorbing most near-term
Solid-state battery process control in mid-2026 revolves around four measurement nodes: stack pressure (100 MPa-class) on sulfide cells, ppm-level moisture via high-temperature Karl Fischer up to 1000°C, operando neutron powder diffraction for thick pellets, and screw-press test cells up to φ16 mm.

Solid-state battery manufacturing quality standards remain in flux as of August 2026: no global ASSB-specific standard exists yet, and China is leading formalization with two new GB/T projects for performance and life. OEM stacks ride on conventional transport and safety certifications like UN38.3,
Solid-state battery module capacity is scaling into the GWh range, with one Chinese maker confirming 3 GWh of cell capacity and 500 Ah cell tooling. Module demand is projected to grow from USD 980M in 2026 to USD 12.5B by 2036 at a 29.0% CAGR, with sulfide chemistry and sub-1 kWh formats leading ear

China's H1 2026 sodium-ion output reached 2.45 GWh, up 16% year-on-year, and OEM/ODM partners now deliver 12V to 1.45MW systems on shared lines. Choose wholesale for low-risk market tests, OEM for branded re-skinning of proven designs, and ODM when capacity, BMS, or form factor must be co-developed
Sodium-ion cell cost sits at $59-75/kWh in 2026, roughly 20% above LFP at $95-115/kWh pre-subsidy, with manufacturing overhead (Yuan 0.15/Wh) and hard-carbon anode (Yuan 0.09/Wh) as the dominant cost drivers over cathode savings.

Sodium-ion battery materials market is on track from USD 0.10 B in 2025 to USD 0.57 B by 2035 at a 19.01% CAGR, with Asia-Pacific holding ~75% share and CATL's Naxtra brand leading mass-market deployment in stationary storage.

Sodium-ion cell production is moving from pilot to GWh scale, but current lines run at roughly 70% yield versus more than 95% for mature lithium-ion, so the next 12 months will be defined by tighter process control around moisture, CO2 exposure, particle size, and stack pressure rather than chemistr

Over 80% of lithium-ion cell production equipment can be adapted for sodium-ion manufacturing with minimal modification, per Chinese industry guidance published August 24, 2026. Full-cell energy density now reaches 140–160 Wh/kg versus LFP at 160–180 Wh/kg, while hard-carbon anode first-cycle c

A battery pack production line in 2026 is a four-stage system: cell sorting, module assembly with laser or ultrasonic welding, pack-level thermal and electrical integration, and conditioning plus end-of-line test. PNNL's 16-piece prismatic pilot fills 1,400 sq ft of lab space. Turnkey integrato

Battery pack manufacturing cost in 2026 splits roughly 45% electrode manufacturing, 30% cell finishing, and 25% cell assembly, with cell-level pack pricing in the $40-140/kWh band and global 2024 average at $115/kWh. LFP, NMC, geography, and capex intensity are the main cost drivers.

Industry 4.0 adoption in battery pack manufacturing is driven by MES-edge integration, AI vision-based defect detection, and digital-twin production lines, with secondary rechargeable cells supplying 90.6% of 2025 demand at 17.45% CAGR through 2031.

Lithium battery pack process control is dominated by PLC/SCADA platforms with dew points held at -40 to -60 °C, OCV/IR grading to ±1 mV, and module fixturing under 8,000 N clamp force, per 2026 spec maps and pilot-plant engineering postings.

Battery pack manufacturing quality in 2026 hinges on a layered stack: ISO 9001 quality management, IEC 62133-2 cell safety, UN38.3 transport, ISO 14644 cleanroom control, and product-specific UL/IEC marks. EV and medical packs add ISO 13485, IEC 60601-1, and tighter contamination limits; 68% of auto
Battery pack production capacity planning now depends on three numbers that move together: 70% three-year U.S. storage growth, 54 GW of operator-planned additions, and roughly 890 GW sitting in interconnection queues. Plants that align labor, maintenance, and AI-driven scheduling on a single calenda
OEM battery manufacturing builds cells and packs to a customer's drawings and BMS/communication specs, while ODM manufacturing sells the factory's own reference design with branding tweaks; OEM suits unique high-performance builds, ODM suits faster, lower-NRE launches.

Battery cell production line design splits into three sequential process blocks: electrode manufacturing, cell assembly, and cell finishing. Modern lines target cylindrical, prismatic, and pouch formats on parallel cathode and anode tracks, with dry rooms held at sub-1% humidity for lithium-ion asse

The global battery cell market is set to expand from USD 93.48 billion in 2026 to USD 241.96 billion by 2031 at a 20.95% CAGR, with Industry 4.0 adoption driven by gigafactory buildouts, 4680 cylindrical formats, and BESS demand. CATL held 37% global share in 2024.

Battery cell manufacturing quality in mid-2026 hinges on three pillars: UL/IEC 62133-2 safety certification, EPA 40 CFR Part 461 effluent compliance, and documented incoming-cell testing plus formation-and-grading discipline. Manufacturers that skip capacity, internal resistance, and OCV checks at i

Battery cell manufacturing equipment spans three process blocks (electrode manufacturing, cell assembly, cell finishing) and a parallel pack-assembly stack, with the global market valued at USD 15.63B in 2025 and projected to USD 36.94B by 2030 at 18.8% CAGR. Selection is driven by format-specific t

Nuclear-grade OEM and ODM manufacturing diverges sharply from consumer-grade ODM: ASME NQA-1 / 10 CFR 50 Appendix B quality programs, 10-year commercial-grade dedication, and EN 10204 3.2 mill certs are non-negotiable. A 2026-08 spec check for nuclear fasteners and I&C assemblies is mapped below.
Heavy forging capacity and U.S. fuel-line policy now define the bottleneck for new nuclear build. Generation III+ pressure vessels need 140-150 MN presses taking 500-600 tonne ingots, and 2025-07 DOE Fuel Line Pilot Program backs U.S. HALEU supply lines.
Four privately developed non-light-water reactors reached criticality at U.S. labs between June 4 and July 4, 2026, meeting the Energy Department's Reactor Pilot Program target. Industry 4.0 digital instrumentation, AI-assisted control, and ISO 19443 nuclear-quality schemes are now central to that b

Nuclear power I&C is shifting from analog to digital PLC/DCS platforms with embedded AI monitoring, driven by SMR builds and fleet digitization. U.S. design hires at Sargent & Lundy, Black & Veatch, and Burns & McDonnell confirm sustained demand as of August 2026.
Nuclear component manufacturing is governed by ASME NQA-1 and 10 CFR 50 Appendix B, the dominant QA frameworks for safety-related fabrication. Specifying nuclear-grade alloys, NQA-1 audited suppliers, and CMMS systems with safety-classification tagging and tamper-evident records is the practical flo

Specifying nuclear power manufacturing equipment starts with three filters: ASME N-stamp qualification, forging press capacity (140-150 MN for Gen III+ RPVs), and ASME III/IX weld procedure coverage. As of 2026, the global forging bottleneck sits with Japan Steel Works, China First Heavy Industries,

For offshore wind projects, OEM vs ODM selection hinges on whether the buyer owns the IP and certification file: pure OEM runs the buyer's drawing and bill of materials, while ODM lets the manufacturer supply cell topology, firmware, or hull design under the buyer's brand. Picking wrong inflates LCO

Offshore wind production line design now demands tower rolling, monopile fabrication, and drivetrain assembly lines rated for 11–15 MW turbines, with foundations representing roughly 30% of project CAPEX. Engineers should size plate-rolling cells, automatic welding stations, and balance-of-plant con

Offshore wind LCOE sits at $95/MWh for fixed-bottom and $145/MWh for floating, with a 132% premium over onshore. Cost drivers are turbine size, water depth, installation logistics, and O&M, and European turbine selling prices have risen 40–45% since 2020 while manufacturing costs rose only 20–25%.

Offshore wind manufacturing quality now hinges on a documented stack: APQP4Wind for supplier quality, ISO 12944-9 plus DNV-RP-0416 and NORSOK M-501 for offshore coatings, and ISO/IEC 17025-accredited labs for materials testing. Corrosion-driven O&M at $135/kW-year is the line item forcing spec tight

Offshore wind manufacturing equipment spans tower steel fabrication, nacelle assembly, and floating substructures. 2025 installations hit 10,312 kW average offshore turbine capacity, with 178 GW added globally per GWEC.
For natural gas appliance brands choosing between OEM and ODM manufacturing, the decision pivots on IP ownership, time-to-market, and tooling cost: OEM suits long-term brand control with higher upfront investment, while ODM delivers faster launches from a factory-owned catalog. Indian and Chinese fa
U.S. natural gas production in 2026 averages 122.5 Bcf/d with Henry Hub at $3.44/MMBtu, but consumer prices still rose 63% from 2024 to 2025; the cost stack for natural gas as a manufactured, transported and combusted product runs roughly 55–70% feedstock, 15–25% processing, and 10–20% delivery.
U.S. oil and gas digital transformation spend grows by $56B from 2024 to 2029, with FERC confirming NAESB gas-electric coordination standards in May 2026 to harden pipelines against cold-weather stress. RPA, SAP S/4HANA, OPC UA, and AI are now the dominant adoption stack, but roughly 70% of digital
Natural gas process control depends on four instrument families: pressure/level/temperature transmitters, gas chromatographs or Raman analyzers for composition, flow computers at custody transfer, and pneumatic or SCADA-linked controllers for valve actuation. EPA guidance names gas-driven pneumatics
Natural gas manufacturing quality rests on API Q1 10th edition (2026) for equipment QMS, ISO 9001 for general QMS, EPA NESHAP MACT rules for emissions, and pipeline-quality specs set by major transmission operators. Producers and processors must satisfy all four layers simultaneously to ship gas int

U.S. marketed natural gas production hit a record 118.5 Bcf/d in 2025, with Appalachia, Permian, and Haynesville supplying 67% of output and 81% of growth, while global LNG faces a 120 Mt/yr capacity gap by 2040. Capacity planning now spans reservoir decline, pipeline takeaway, storage, and AI-drive
Natural gas manufacturing equipment spans the full processing train: slug catchers, 2-/3-phase separators, amine contactors, molecular-sieve dehydrators, TEG units, cryogenic NGL recovery, reciprocating/centrifugal compressors, and pipeline-spec custody meters. Specs are anchored to API/GPA pipeline

OEM connector projects mean the buyer owns drawings, BOM, and IP, and pays for full mold/tooling; ODM means the factory picks a mature platform (e.g. M12, IP67) and the buyer only supplies parameters plus a logo. Decision turns on who holds the IP, who funds the mold, and whether MOQ supports a 3-7

Connector BOM cost in a typical wire-harness assembly sits at 20-30% of the total, with entry-level crimp terminals near $0.10 and sealed industrial connectors at $20-plus, so connector family rationalization and DFM reviews routinely cut 15-40% off finished unit cost in 2026 programs.

Connector Industry 4.0 adoption is reshaping the US$25.83B North American connector market, with contactless variants forecast to grow from US$0.3B in 2024 to US$1.8B by 2035 at 17.5% CAGR, driven by EV, robotics, and smart-factory demand.

Connectors for process control and instrumentation are engineered in two distinct families: electrical signal/power interconnects (2-26 pin industrial circulars) and instrumentation pipe/thread conversion fittings (NPT-to-ISO). Specifying the right one requires pinning down contact count, current/vo

Connector manufacturing quality in 2026 rests on four interlocking layers: ISO 9001 QMS, MIL-STD performance, IEC electrical safety, and inline process controls that target defect rates below 50 PPM at automated plants.

Connector production capacity planning in 2026 hinges on five work-center nodes (molding, soldering, assembly, potting, inspection) tied to batch repeatability, with median factory runtime stuck near 32% and changeover variability at 56.6%, making process-level control the highest-leverage decision
Cable and wire production line design hinges on three design gates: a high-speed automated core (typically 0.8-2.5 m/s line speed) with in-line vision, a Kanban-staged material flow that compresses lead time to one day, and PPAP-grade process control. The article compares manual, semi-auto, and full

Custom wire harness cost in 2026 ranges from under $1 for simple consumer builds to over $5,000 for aerospace assemblies, with materials (30–50%), labor (15–25%), and connector choice as the main cost drivers. A 10% rise in copper prices typically adds 3–4% to harness cost, while US-based production

Industry 4.0 adoption in the cable and wire sector is reshaping factory floors through IoT extrusion lines, digital twins, and AI-driven quality control, with the global wire and cable market projected to grow from $246.48 billion in 2026 to $410.70 billion by 2034 at a 6.59% CAGR.

Wire and cable procurement hinges on a layered quality stack: ISO 9001 for the QMS, UL or BIS ISI marks for product safety, IPC/WHMA-A-620 for harness workmanship, plus AWG sizing, XLPE cross-linking, and ampacity derating rules that govern every spec sheet. Buyers who skip the cert audit invite ins
Cable and wire production capacity planning now hinges on closing the gap between ERP standard line speeds and what the extruder or drawing line actually runs, with a L.E.K. engagement showing 10%–16% income uplift from end-to-end supply chain work and a 2026 global market sized at $246.48 billion [

Industrial valve production lines balance casting/forging, CNC machining, seat hardfacing and hydrostatic testing against API 6D, API 600 and PED 2014/68/EU. The 2026 spec bands call for hard-seating alloys like Stellite, body materials spanning WCB to duplex 2507, and pressure classes from 150 to 1

Initial purchase price accounts for 10 to 15 percent of an industrial valve's total cost of ownership, with installation, maintenance and downtime driving the remaining 85 to 90 percent. Critical-service units can exceed $50,000 each, and a single $3,000 control-valve failure can cost a pl
Smart-valve integration tied to Industry 4.0 is the single largest demand lever for the European industrial valve market, projected to climb from US$ 17,974.2 million in 2025 to US$ 26,494.0 million by 2034 at a 4.4% CAGR, with control valves leading at 5.0% CAGR. Solenoid and proportional valv

API 6D, ASME B16.34, ISO 5208, and API 607/6FA are the four specification pillars procurement teams check first when qualifying an industrial valve manufacturer, with API 6D mandatory for pipeline service and ASME B16.34 governing pressure-temperature ratings across the spec sheet. Plants that hold
Industrial valve production capacity planning in 2026 hinges on three levers: hydrogen-ready line conversions, electric-actuator integration, and Cv-validated throttling. Flowserve expanded hydrogen-compatible capacity in 2025; Rotork launched a new electric actuator generation the same year.
Industrial valve manufacturing equipment selection is driven by five spec anchors: pressure class (ASME Class 150 to 2500, PN10 to PN160), body material (WCB, LCC, SS316, Duplex 2205/2507, WC6/WC9), end connection type, temperature range, and applicable standard (API 600, API 6D, ASME B16.34). Plant

Industrial pump OEM and ODM routes differ primarily in who owns the design: the buyer for OEM, the factory for ODM. This translates into concrete trade-offs in tooling cost, MOQ, IP risk, and time-to-market that specifiers should weigh against duty class and certification needs.

The industrial pump market reached USD 50.46 billion in 2026 and is forecast to hit USD 63.45 billion by 2031 at a 4.69% CAGR, with centrifugal designs holding 61.85% revenue share. Production-line design for pump assembly should anchor on three technical pillars: pump-type mix, throughput bottlenec
Industrial pump manufacturing cost is dominated by lifecycle energy and maintenance, not the unit price: the pump itself is roughly 10% of 20-year spend, energy ~40%, maintenance ~25%. Per-HP ranges run $100–$500 for general-purpose units and $500–$2,000 for API-compliant builds, with material grade

Industry 4.0 adoption has pushed intelligent pump control systems past 60% penetration among Fortune 500 manufacturers, with the global intelligent pump market valued at $28.5B in 2025 and projected to reach $47.3B by 2033 at a 6.8% CAGR.

Industrial automation software suites from OAS, Rockwell, Inductive Automation, B&R and LEAD Intelligent are converging on a single IIoT/SCADA/MES/edge stack as of July 2026, with vendor positions diverging on licensing, openness and battery-line specialization.

Industrial pump production capacity planning hinges on the bottleneck work centre, not total factory hours: level-load MPS against finite-hour constraints at machining, assembly, and test cells, using RCCP and AI replanning to keep OTD above 95%.

Industrial pumps convert mechanical energy into hydraulic energy, covering head 5–150 m, motor power 0.75–250 kW and materials from cast iron to Hastelloy C-276, with API 610, ISO 5199, ATEX 2014/34/EU as reference standards. Selection hinges on matching flow, head, NPSH, fluid chemistry and duty cy
OEM air compressor programs let brands stamp their identity on a proven platform with lower tooling cost, while ODM programs design the unit from scratch to meet a custom flow, pressure, voltage, or noise target. For most buyers the decision hinges on IP ownership, MOQ tolerance, validation depth, a
Air compressor production line design in 2026 centers on modular assembly with 150,000–300,000 units annual capacity, ±0.02 mm servo press-fit accuracy, and OEE ≥85%. Two-stage compression cuts energy use 15–25% versus single-stage, while DOE data flags 20–30% leak loss as the first audit target.
Industrial air compressor manufacturing cost is driven by materials (cast iron, copper windings, rotors), assembly labor, and energy over a 10-15 year service life. Energy typically dominates 70-80% of total cost of ownership, with purchase price only 10-15% and maintenance 10-15%.

Industry 4.0 adoption is reshaping industrial air compressor specification in 2026, with the global market projected at $29.0 billion in 2026 and smart-connected units now central to plant energy and uptime strategies. Selecting a compressor in this cycle means weighing VSD, oil-free, sensor density
Instrument air for process control must be oil-free, dry to a -40°C pressure dew point, and held inside ±1% of loop setpoint. For 2026 spec work, the real decision is single-stage oil-flooded screw vs. oil-free two-stage vs. oil-free centrifugal, paired with desiccant or membrane drying and ISO 8573
Air compressor manufacturing quality is anchored by ISO 8573-1:2010 purity classes, CAGI performance certification, and OSHA 29 CFR 1910.147 LOTO procedures. Class 0 oil-free is mandatory for direct food contact; U.S. plants lose roughly 30% of compressed air to leaks per U.S. DOE data.
Air compressor capacity planning hinges on a five-step audit-to-FAD method under ISO 1217:2009, with two-stage units delivering 10–40 bar at 15–25% lower energy than single-stage. Capex runs near 8% of 10-year life cost; electricity exceeds 90%, so a kW-sized mistake compounds fast.

Industrial air compressors in 2026 are integrated compressed air systems, not standalone machines, with sizing driven by CFM, PSI, and duty cycle, and pharmaceutical builds requiring ISO 8573-1 Class 0 oil-free units on a full URS/DQ/IQ/OQ/PQ qualification framework.
Pneumatic production line design is dominated by four engineering decisions: material characterization, conveying mode (dense vs. dilute phase), air velocity and pressure-drop calculation, and pipeline layout. Field data shows 70% of failures trace to design errors, and correctly sized air velocity

A pneumatic system in 2026 typically costs 60-75% in compressors, dryers and FRL, 15-25% in actuators and valves, and 10-15% in fittings, tubing and assembly labor, with annual energy at 70-80% of ownership cost.

Smart pneumatic components are scaling fast under Industry 4.0, with the global market valued at USD 18.66 billion in 2026 and growing at a 5.38% CAGR toward USD 28.38 billion by 2034. Asia-Pacific leads adoption at 48.3% share, and valves plus actuators now ship with onboard sensors for pressure, l

Pneumatic system manufacturing quality is governed by ISO 8573-1 compressed air purity classes, SAE pneumatic standards (73 active), and FSMA cGMP rules, with Class 6-7 particles for general factory automation and Class 2-3 for electronics manufacturing.

OEM and ODM are the two main engagement models for sourcing hydraulic systems, with OEM suited to brand-owned designs and ODM suited to leveraging manufacturer-developed platforms. The decision turns on IP control, mold investment, MOQ, lead time, and target differentiation.

Hydraulic system manufacturing cost is dominated by pumps, valves, cylinders, and motors, with the global component market valued at USD 53.48B in 2024 and projected to reach USD 94.4B by 2035 at a 5.3% CAGR. Real total-cost-of-ownership is driven by energy losses of 50–65%, fluid losses of 5–10 gal

Hydraulic system manufacturing quality is enforced across five stages: material selection, CNC machining, welding, surface finishing, and pressure-tested assembly, with ISO 4406 fluid cleanliness and sub-millimetre tolerances as the baseline gates. Plants that skip the gates absorb $150K–$800K per h

Hydraulic system production capacity planning for 2026 hinges on aligning cylinder bore (up to 1000 mm), stroke (up to 14000 mm), and pressure (up to 1000 bar) with verified ISO 9001 in-house test rates and 24/7 duty cycles, with steel-mill servo systems at 250-350 bar driving downtime exposure of $

The global hydraulic equipment market is projected to grow from $55.49 billion in 2026 to $80.08 billion by 2034 at a 4.7% CAGR, driven by steel, mining, and recycling machinery demand. This guide covers hydraulic system manufacturing equipment: the pump, cylinder, valve, and accumulator building bl
OEM bearing contracts require buyers to supply complete drawings, tolerances, material grades and packaging, while ODM shifts concept and design responsibility to the supplier. For ball, roller and slewing bearing buyers, the decision turns on engineering maturity, sample-to-mass-production lead tim
A bearing production line in 2026 is built around four anchor decisions: bearing type and capacity mix, raw material and forging route, heat treatment and finishing cell, and assembly plus testing automation. BKZ Industry's first new-factory line for deep groove ball bearings came online on 2026-06-
Bearing purchase price is a small slice of total cost; raw material (typically bearing steel), manufacturing process, and quantity tier dominate the line item, while downtime averaging ~$260,000/hr per Aberdeen data makes the failure cost dwarf the part.
Bearing manufacturers are folding AI, machine learning, robotics, and condition monitoring into factory and product design, with the global ball bearing market tracking from USD 21.63 B in 2025 to USD 31.69 B by 2035 at 3.89% CAGR, and linear motion bearings from USD 9.21 B to USD 16.22 B at 5.82% C

Bearing process control relies on closed-loop monitoring of load, speed, temperature, and lubricant film to keep miniature and precision bearings inside their design envelope. Timken's 2026-05-18 miniature ball bearing spec sheet confirms compact, high-speed, low-friction units for medical, robotics

Bearing manufacturing quality in 2026 is anchored on ISO 9001 QMS audits, ISO 14001 environmental controls, ISO/IEC 17025 lab accreditation, and ABMA/ANSI/ISO tolerance grades ABEC-1 to ABEC-9 for rolling elements, with DIN 620 PT2 defining ring tolerances. Three August 2026 vendor pages illustrate
Bearing production capacity planning in 2026 hinges on machine-hour capacity, throughput time, and demonstrated output, with bearing-type mix driving real machine load. Treat capacity as a dynamic, type-specific calculation, not a single number.
Bearing manufacturing equipment selection for 2026 hinges on five decision gates: bearing type, machine class, accuracy tier, lot size, and remanufacturing policy. Procurement engineers should match ISO 15243:2017 failure-mode data to CNC process demands before vendor shortlisting.
Machine tool production line design in 2026 centers on virtual-prototype modelling, WZL-style metrological acceptance, and modular tending cells, with ISO 230 and ASME B5.45 acceptance tests governing geometric and positioning accuracy. This guide compares layout, work-holding, and tending options a

Machine tool Industry 4.0 adoption in 2026 centers on digital-twin NC simulation, OPC UA interoperability, and AI-driven process control, with SMEs still lagging large OEMs in deployment maturity.

Machine tool manufacturing quality is governed by ISO 230 accuracy/repeatability tests, JIS B 6336 thermal-stability checks, and ISO 9001 QMS audits applied to builders such as SMTCL (Shenyang Machine Tool) and HAILI. CNC machining services typically quote ±0.01–0.05 mm tolerances, with China-based
Machine tool production capacity planning resolves around three core numbers: machine-hour capacity, throughput time, and demonstrated actual output, with Rough Cut Capacity Planning (RCCP) used to validate master schedules at hours per week per resource or rate per week per line before detailed MRP

Machine tool manufacturing equipment in 2026 spans CNC machining centers, gantry mills, cylindrical grinders, lathes, and saws. Selection hinges on workpiece envelope, axis count, repeatability, and controller openness. This guide maps types, criteria, and a comparison of mainstream options for proc
OEM and ODM are not interchangeable CNC sourcing models. OEM executes the buyer's locked spec; ODM lets the factory drive design and IP. Pick by who owns the drawing, the lead-time tolerance, and the unit-volume commitment.

A CNC machine production line is an integrated cluster of machine tools, robotic loaders, conveyors and control software, configured to turn raw stock into finished parts with minimal manual handling. Design choices on spindle envelope, axis count, automation tier and takt balance determine throughp

CNC machine cost breaks into setup cost plus cost-per-unit. Setup absorbs material, CAD/CAM, fixturing, labor, and QA; per-unit covers cycle time, tooling wear, and material. The cost split is the only reliable lever for lowering price per part.

CNC Industry 4.0 adoption in 2026 means retrofitting machine tools with IoT sensors, edge controllers, and OPC UA/MQTT links so spindle, axis, and tool data feed cloud analytics for predictive maintenance and lights-out machining. Plants should treat it as a brownfield integration project with payba
CNC process control in 2026 revolves around closed-loop feedback, smart tool monitoring, and 1 nm-class axis resolution on grinding platforms, with 220 kN hydraulic presses and 1,600 strokes/min punching rates still anchoring sheet-metal cells. Specifying engineers should size machines by axis resol

CNC machine manufacturing quality standards in 2026 cluster around ISO 9001:2015 as the floor QMS, with AS9100D required for aerospace Tier-1 supply and ITAR governing defense work. Acceptance criteria split into geometric (positioning accuracy, repeatability per ISO 230-2), surface (Ra per ISO 2192

CNC production-capacity planning for 2026 hinges on matching spindle hours, axis count (3-12), and tooling budgets against forecast demand, using RRP and CRP models to validate constraints before commit. For spring-forming cells, ±0.01mm accuracy on 2-14 axes at speeds to 110m/min sets the output ce

OEM and ODM are the two dominant manufacturing engagement models for mining equipment, separated by who owns the design: in OEM, the brand owner controls the drawings; in ODM, the factory contributes or fully owns the design. The right pick depends on IP control needs, capex tolerance, and time-to-m

Designing a mining equipment production line in 2026 means chaining primary jaw or gyratory crushers, cone/impact mid-stage units, ball or SAG mills, vibrating screens, magnetic separators, flotation cells, and rotary dryers, with throughput options typically 40-1000 t/h and matched wear-resistant s

Mining equipment manufacturing cost in 2026 breaks down into steel content, powertrain, hydraulics, electronics, and certification tier, with material inputs typically driving 45-60% of build cost on mobile mining assets. Buyers mapping 2026 budgets should anchor on application class (surface vs und

Mining-equipment Industry 4.0 adoption in 2026 is anchored on cyber-physical systems, IIoT telemetry, and condition-monitoring rebuilds on legacy shovels, drills, and conveyors. Buyers should match I4.0 scope to shovel/drill/plant criticality, OEM data openness, and underground connectivity limits.

Mining-grade process control and instrumentation in 2026 is built around three spec gates: ruggedised field hardware, integration with heavy mobile equipment, and traceable calibration. Buyers should anchor selection on IP/ATEX/IECEx ratings, HART or Ethernet-APL comms, and on-condition monitoring t

Mining equipment manufacturing quality standards in August 2026 still center on documented weld procedures, 100% pressure testing, ISO 9001 QA systems, and material traceability for wear parts across crushing, drilling, and valve product lines. Domestic Chinese and Indian OEMs are converging on a co

Mining equipment production capacity planning in 2026 hinges on matching shovel/excavator engineering capacity, service capacity, and truck haulage cycle to ore body variability. Open-pit planners now layer OEM automation, condition monitoring, and ISO 9001/14001/45001-certified spares supply into a

Chinese OEMs supplied roughly 60% of new mining-dump-truck, drilling, and crushing equipment globally in the past 6 months, with Hebei FCCS, CITICIC Luoyang, UGHM, and Yantai Jinpeng leading underground-drill, ball-mill, and rock-jumbo lines. Specifying engineers should match ISO 9001-certified Chin

Desalination OEM builds to the buyer's design and tooling; ODM ships a buyer's-brand-ready reference plant with the manufacturer's own process IP. Pick OEM when feedwater, recovery, or compliance is non-standard; pick ODM when a 10,000-50,000 m³/d SWRO or BWRO block fits a known reference design and

Desalination plant capital cost breaks down into five dominant buckets: intake/screens, membranes and pressure vessels, high-pressure pumps, energy recovery, and civil works. Membrane modules plus high-pressure pumping typically account for 25-35% of equipment cost on a seawater reverse osmosis trai
Desalination plants are digitising the brine train, the high-pressure pump skid, and the RO membrane array with IIoT, digital twins, and AI-driven energy optimisation. Adoption is gated by retrofit cost, sensor coverage, and a small set of industrial-automation standards. This article maps the curre

Desalination manufacturing quality rests on ISO 9001 QMS, membrane performance testing, and traceability from RO/UF/ceramic elements to pressure-vessel castings, with third-party inspection and OEM/ODM control shaping buyer risk.

Petrochemical production line design in 2026 ties feedstock selection, reactor duty cycle, and IIoT-grade instrumentation into a single spec gate. Twin-screw extruders sized 55-65mm screw diameter, 11.5-15kW drives, and 30-100 kg/h output define the polymer-pipe branch, while downstream maintenance
Petrochemical manufacturing cost is dominated by feedstock (commonly 50–70% of cash cost) and energy, with catalysts, utilities, fixed capital depreciation, labor, and maintenance competing for the remainder. Total cost of ownership shifts with crude-to-naphtha parity, steam/reformer load, catalyst

Petrochemical Industry 4.0 adoption is accelerating as TIC spend scales to USD 254.41 billion in 2026, with 80% of manufacturers running Industry 4.0 initiatives. Integration centers on IIoT-enabled pressure transmitters, flow meters, and PLCs, while TIC providers deliver the assurance backbone for

Petrochemical capacity planning in 2026 hinges on multi-objective linear programming, integration with MRP/RRP, and instrumented feedback from pressure, flow, and valve assets. This article lays out the spec gates, decision criteria, and instrumentation points engineers should use.
OEM builds to the buyer's drawing, ODM ships the buyer's brand on a factory-finished design. For LNG buyers the choice is binary: pick OEM when ASME/DOT pedigree and process IP control matter, pick ODM when speed-to-market and lower NRE outweigh customization. Chinese factories on Made-in-China.com
An LNG production line is sized around feed-gas composition, refrigerant cycle choice, and impurity solubility gates, with the 2026 supply expansion adding ~40.7 MTPA of new nameplate to a 142 MTPA-plus baseline. Purification trains target p-xylene and heavy-aromatic solubility in methane to protect

2026 marks the pivot year of the global LNG "super-expansion cycle," with ~40.7 million t/yr of new liquefaction capacity (Golden Pass, LNG Canada, Costa Azul, North Field expansions) driving process-control and instrumentation demand for cryogenic, hazardous-area, and SIL-rated systems across the s
LNG production capacity planning now centers on 142 MTPA mega-trains and modular mid-scale plants, with control-instrument spec gates set by flow, pressure, and valve selections on the 4–20 mA / HART layer.

Aerospace production line design in 2026 hinges on tight integration between precision machining, hydrogen-ready powertrain packaging, and Industry 4.0 spec gates. Cranfield Aerospace Solutions markets modular, scalable, retrofit-or-line-fit hydrogen powertrain integration, while shops like Spectrum

Aerospace part cost is driven by five interlocking buckets: raw material (often 25-45% of part cost for titanium/Inconel), AS9100D/NADCAP-qualified labor, tight-tolerance machining cycle time, recurring certification/audit overhead, and low-volume tooling amortization. Tier-2 suppliers in 2026 compe
Aerospace Industry 4.0 adoption in 2026 centers on IoT, digital twins, additive manufacturing, and AR/VR for assembly, with Europe holding 30-35% of the global Industry 4.0 market and SMEs facing the steepest barriers to entry.
AS9100D, ISO 9001:2015, and NADCAP are the three quality frameworks most often specified in aerospace manufacturing RFPs, with AS9102 FAIR documentation and ITAR registration common to the contract flow.

Aerospace production capacity planning is the discipline of sizing work centers, equipment, and skilled-labor hours against an MPS or MRP-derived schedule, using tiered methods (RRP, RCCP, CRP) over a 12-month to three-year horizon. Selection hinges on whether the bottleneck is tool-hours, floor-spa
Aerospace manufacturing equipment in 2026 centers on AS9100D-certified 5-axis CNC machining, friction stir welding, and precision adhesive dispensing, with suppliers split between US Tier-2/3 shops and Chinese high-precision gantry builders. Buyers should match equipment to part mix: gantry mills fo
Satellite OEM and ODM are distinct engagement models: OEM builds to the buyer's design and bills for the build, while ODM contributes the reference design and the buyer rebrands. In the space-segment supply base, the choice hinges on IP control versus time-to-orbit, with Chinese antenna and receiver

China now runs at least two purpose-built smart small-satellite lines: a CASIC Wuhan line rated for 240 small satellites per year, and Hunan Satellite Technology's Zhuzhou line rated for 150+ satellites annually in the 50–500 kg class. Both rely on machine-led assembly, on-site AIT, and integrated s

Satellite bus and subsystem costs are governed by payload class, radiation-hardened electronics, and qualification gates, with LEO smallsats (≤500 kg) priced an order of magnitude below GEO platforms. Decision-relevant cost drivers: bus size tier, EEE parts grade, propulsion type, and ITAR/export cl
Satellite production capacity planning in 2026 is being reshaped by China's smart-manufacturing satellite plants targeting 240 units/year per line, while Western operators shift to smallsat constellations requiring MRP, work-center routing, and capacity-constrained finite scheduling in SAP PP or Net
Satellite manufacturing equipment in 2026 centers on Class 100K/ISO 8 cleanrooms, autoclave/composite curing ovens, precision 5-axis CNC, and thermal-vacuum chambers sized to small-sat busses (3U-12U, ESPA-class). Spec gates: ISO 14644-1 cleanliness, AMS 2774 thermal processing, and MIL-STD-810 vibr
Drone production line design in 2026 centers on modular, AGV-fed assembly cells with robotic subassembly, ESD-controlled avionics stations, and an FAA Part 107 plus Section 44807 compliance frame for finished units above 55 lb. Output planning should track takt, fixture density, and the BOM cost sta

Industrial drone bill-of-materials cost is driven by frame, flight controller, motors/ESCs, batteries, and sensors, with each subsystem split between material, conversion, and integration cost; a standard-costed BOM inquiry approach lets buyers and OEMs roll up the same view, while volume tier,

Industrial drone adoption inside Industry 4.0 programs stays gated by data plumbing, talent, and standards more than by airframes, with open repositories and SME studies from 2024-2026 shaping the spec map.

Drone manufacturing quality standards in mid-2026 hinge on three OEM-disclosed pillars: airframe-grade composites, military-grade electronics screening, and customizable UAV platforms built to industrial specs. Indian OEMs ideaForge and HAVELI UAVs lead documented practice, with SWITCH UAV and SWAMI

OEM and ODM OLED manufacturing are two distinct sourcing models: OEM builds a buyer-supplied design to print, while ODM delivers a pre-engineered reference design the buyer re-labels or customises. In China, most Tier-2 OLED module factories cluster in Guangdong and offer both services side-by-side,

OLED production line design centers on Gen 8.5+ evaporation deposition, with 2026 demand driven by IT-grade panels for slimmer MacBook Pro at 3-5 million units annually. Core specs: 2290 mm x 2620 mm substrate, thin-film encapsulation, vacuum cluster tools. Samsung Display runs the lead IT-8G OLED l

OLED panel cost-of-ownership is dominated by laser-based process steps, with femtosecond and nanosecond sources, beam-delivery optics, and motorized stages cited as the primary spend categories by MKS in its 2026 OLED processing guide.

OLED display makers are now wiring AI into deposition, metrology, and driver-IC lines: Sunic System joined Korea's 7-year Super B R&D program to build an AI-based OLED deposition platform (2026-08-07), while Lumicore broke ground on a 12-inch OLED microdisplay fab in Nanjing targeting late-2026 comp
OLED panel quality hinges on a tightly controlled dry vacuum process stack where particle counts, vacuum integrity, and laser-patterning precision set the yield ceiling, and three process gates (encapsulation, Laser-Lift-Off, fine metal mask drilling) are the recurring root causes of field failure.

OLED panel manufacturing equipment in 2026 spans vacuum thermal evaporation (VTE), PECVD, MBE, laser Lift-Off, and ELA clusters. Buyers should match tool class to substrate (rigid glass vs flexible polyimide), generation (4.5G/6G/8.6G), and stack type, with throughput and encapsulation yield as the

Display panel OEMs execute buyer-owned designs, while ODMs supply a ready reference platform that the buyer re-skins and re-brands, a split that drives 2026 sourcing decisions on MOQ, IP, and time-to-market.
Display panel production line design hinges on a few hard variables: substrate generation (G4.5/G6/G8.5), cleanroom class, and target monthly capacity. Reference AMOLED fabs like the Yungu Gu'an G6 project (30,000 pieces/month, 30 billion RMB, 573-day build) set the benchmark for full-flex line engi
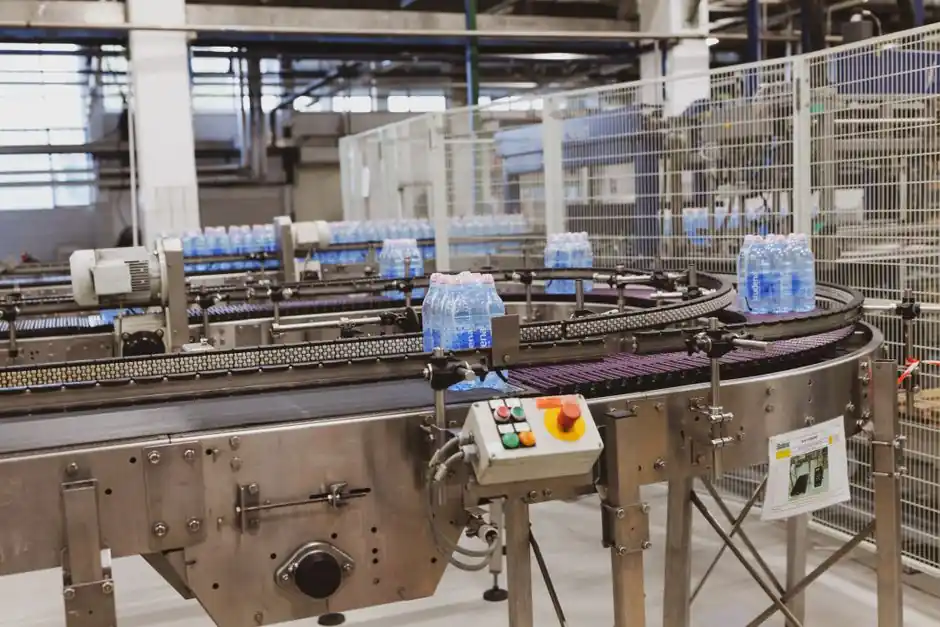
Display panel Industry 4.0 adoption in 2026 centers on retrofitting legacy HMIs and aluminum control panels with OPC UA, MQTT, and edge-AI OPC UA gateways, cutting unplanned downtime. The harder question is which upgrade path matches a given production line's protocol stack and takt time.

Flat-panel display buyers in 2026 must qualify fabs against IEC, ISO, and IPC-grade quality gates, because LCD, OLED, and PDP lines all diverge on optical, mechanical, and process-control requirements. This article maps the standards, the process-engineering checkpoints, and the supplier audit signa

Display panel production capacity planning in 2026 hinges on a USD 137.83 BN market by 2032, 3.9% CAGR, and a 12.3% microdisplay CAGR, with LCD, OLED, and Micro-LED fabs scaling 8.6-Gen lines against stochastic demand models.

Display panel manufacturing equipment is a US$7.8B (2024) capital market anchored by Gen 8.6 LCD and RGB FMM OLED fabs, with laser lift-off, cutting, and annealing tools dominating the 2026 capex cycle in China and Korea. Selection hinges on substrate compatibility, line speed, and Gen-size scalabil

LED OEM builds to a buyer-owned design while ODM ships a factory-developed platform; for 2026 lighting buyers, the decision hinges on R&D cost, MOQ, and time-to-market, with Guangdong factories dominating both service tiers.

LED production line design in 2026 centres on three module choices: lamp-shell extrusion (T5/T8 PVC or silicone), LED-strip SMD assembly with SMT pick-and-place, and robotic dispensing for potting. Capacity, substrate, and connector type drive equipment selection.
LED Industry 4.0 adoption centers on digital twin, IIoT, and machine-vision integration across SMT lines, with global Industry 4.0 spending growing strongly through the 2025-2026 transition window. The biggest returns come from joining MES to die-bond and AOI stations, not from stand-alone retrofits

LED manufacturing quality hinges on three concrete pillars: ISO 9001:2015 quality-system certification, ANSI/UL safety listing, and LM-80 / TM-21 lumen-maintenance data backed by IES LM-79 photometric testing. Skip any one pillar and the supply chain cannot be specified for industrial or commercial
LED production capacity planning hinges on aligning upstream MOCVD tool counts and downstream assembly throughput with quarterly MPS demand. Use RCCP for critical work centers, CRP for shop-floor load, and RRP for 12-month to 3-year capital plans.
LED manufacturing equipment spans MOCVD epitaxy, lithography, dicing, wire bonding, and aging testers, with lines increasingly built to SECS/GAM and SEMI smart-fab standards. Asia Pacific holds the highest share of the broader semiconductor equipment market at USD 166.35 B (2025) growing to USD 344.

Heat pump OEM and ODM services in China concentrate in Guangdong and Shanghai, with PHNIX running 24 production lines at 2000+ units/day and module units like 12 kW DC inverter air-to-water models listing at US$1000-3000 per piece on 1-piece MOQ as of mid-2026.

A heat pump production line combines a sheet-metal cell, a brazed/charged refrigeration loop cell, an inverter-board assembly, and an end-of-line performance test station; line throughput, COP verification, and refrigerant-leak rate define the spec sheet for any new 2026 build.

Heat pump OEMs in Guangdong, China are standardising Industry 4.0 production lines around air-to-water and water-source units, with Midea-backed MBT alone running 32 European training centres and guiding a market targeting 1.15 billion euros by 2028.
Industrial and commercial heat pumps integrate vapor-compression control loops that require pressure transmitters, temperature sensors, and flow instrumentation tuned to refrigerant-specific operating envelopes. Specifications focus on low-temperature heat-source lift, part-load modulation, and comp

Heat pump manufacturing equipment for industrial output spans four core production lines (copper brazing, vacuum charging, NDT leak testing, foil winding), with air-source units 30–120°C and Bosch investing 100 million euros. Specs follow ISO 9001.

EV charger OEM/ODM manufacturing in 2026 centres on a few certified Chinese hubs offering UL/ETL/CE-marked AC Level 2 and DC fast units with full PCBA and enclosure customisation. CPOs, fleet operators and brand owners weigh control depth, certification scope, MOQ and integration ownership when choo

EV charger manufacturers adopting Industry 4.0 principles now layer IIoT, AI/ML metamodeling, and cyber-physical system controls onto high-mix lines, with McKinsey's 2026 guidance narrowing focus to four practical levers. Adopters report measurable scrap and uptime gains on the back of near-real-tim

Battery energy storage system (BESS) production capacity planning hinges on three coupled spec axes: power rating (kW/MW), energy capacity (kWh/MWh), and C-rate, with 0.25C to 0.5C utility projects typically planned on 2- to 4-hour discharge durations. Matching cell chemistry, depth-of-discharge lim
A nuclear power manufacturing process spans five controlled stages: fuel fabrication, reactor-component forging, heavy machining, precision assembly and ASME-qualified NDE/QA, with the most sensitive QA gates gated by ASME III and RCC-M. Zhefu Holding runs this R&D pipeline across product design
Copper manufacturing quality standards in 2026 center on ISO 9001:2015 quality systems, ASTM-grade purity (ETP, OF, DHP), and continuous-caster crystallizer specifications. Leading suppliers such as Ganpati Wires, IMC Metals America, and Vipul Copper publish ISO 9001:2015 certifications and ship to
AI chip manufacturing quality standards in July 2026 are being reshaped by AI-driven EDA flows, VDA QMC's automotive AI yellow paper, and tightened traceability expectations from design to wafer. Synopsys's AI-powered EDA suite and imec IC-Link's ASIC/PIC services are the two visible reference stack

Electric motor manufacturing equipment is specified around IEC 60034 / NEMA MG-1 frames, IP/IC codes, thermal class, efficiency tier and VFD bearing protection, with shaft grounding typically limited to 300 mV stray voltage on inverter-duty builds.

EV manufacturing cost is driven primarily by the battery pack (30-40% of BOM), the e-drive assembly, and the high-voltage electronics stack. Cell chemistry, pack energy density, and production volume tier move the bill of materials more than any other lever, while stamping, paint and assembly still
Solar inverter smart manufacturing in mid-2026 spans string combiner boxes, hybrid 3–10 kW inverters, and 96.7%-class single-stage efficiency models, with LiFePO4 storage integration moving from option to default bundle.
Cobalt smart manufacturing in 2026 is converging around Rockwell-style MES/IIoT control, AI vision inspection and lithium/EV battery process cells, with Chinese plants leading scale deployment across smelting and battery lines.
Mining-equipment smart manufacturing pivots on integrated automation, machine vision, and remanufacturing cycles, with Sandvik and Rockwell Automation driving digital fleet control, while Indian and Chinese OEM/ODM capacity keeps unit costs competitive in 2026.
Power grid process control and instrumentation in 2026 centers on IEC 61511 SIS lifecycles, IEC 61850 substation communications, and cybersecure microgrid controllers running on 12-36 Vdc with NIST 800-82/800-53 compliance. Selection is driven by safety integrity level, interoperability, and cyberse

Compressed air system smart manufacturing in 2026 is anchored by master controllers with multi-compressor sequencing, ISO 8573-1 purity-class oil-free compressors, and ASME EA-4-2010 energy assessments driving AI-based leakage analytics across plant networks.

Power semiconductor process control combines thermal-fatigue monitoring, gate-drive instrumentation, and module-level process telemetry to keep IGBT/SiC power stages within safe operating limits. The dominant failure mechanisms are bond-wire lift-off, solder fatigue, and thermal-cycling stress, all

AI chip production capacity planning in mid-2026 hinges on translating wafer-fab and ABF-substrate output into named monthly wafer-starts and qualified substrate area, with AI-driven scheduling now drafting plant plans before human sign-off.
U.S. electrolyte maker Automat Solutions runs a 500+ ton/yr agile line producing 40–400 kg batches, while 2026 Industry 4.0 spec sheets from Rockwell, LEAD Intelligent and Danl converge on AI-driven closed-loop controls for Li-ion electrolyte dosing and battery pack assembly. Smart

Industrial automation software is the digital layer that ties PLCs, robotics, sensors, SCADA, MES and ERP into one controllable system, spanning fixed, programmable, flexible and integrated automation tiers. The 2026 build-out emphasizes real-time data, 3D simulation, and EU CRA-ready controls like
LED smart manufacturing in mid-2026 is defined by AI-driven process control, IIoT data platforms and cobot-mobot interaction patterns, with Chinese OEM/ODM capacity dominating flexible, rental and bar-format LED display lines across 3-300 USD unit price tiers.
Wind turbine manufacturing cost is dominated by the rotor (blades + hub) and the drivetrain (tower, nacelle, generator, gearbox), with blade material, gearbox ratio, generator type, and tower height as the four main cost drivers. A typical 3-5 MW onshore unit lands in the $1.1-1.4 million per-MW cap
Electric motor production capacity planning hinges on matching installed equipment hours against nameplate output, factoring in downtime, maintenance, and efficiency-class mix. March 2025 U4E model rules raise the floor on what a "compliant" line can ship.
IGBT smart manufacturing links insulated-gate bipolar transistor fabs to real-time MES, AI vision and closed-loop process control. As of 2026-06-25, vendors bundle 12-inch line automation, HBM-grade traceability and AI-based yield analytics to push IGBT module yields above 90%.

Power semiconductor production combines wafer fab, lithography, epitaxy, doping, and packaging into discrete devices and modules that switch kW to MW loads. Key families are Si IGBT, Si MOSFET, SiC MOSFET and GaN HEMT, with 1.7kV Full-SiC modules cutting switching loss ~30% versus prior Si IGBTs.
Modern lithium-ion cell production is a six-stage flow (mixing, coating, drying, calendaring, winding/stacking, formation) running inside dry rooms at -40 °C dew point, with electrode coating speed and moisture control as the two spec gates that decide throughput and yield.
Steel rebar is hot-rolled from billets through automated multi-stand mills to ASTM A615/A706/A955, sized #3 (9.5 mm) through #18 (57.3 mm) with grades 40/60/75 ksi, then fabricated by cutting, bending, and coupling for concrete reinforcement.
An electric motor's unit cost is driven first by its specification sheet, not by factory floor choice: insulation class, frame size, enclosure, duty cycle, and efficiency class set material and labour content before any lamination is stamped. Cost stacks from five blocks: raw electrical steel and co

The global EV market was valued at USD 163.01 billion in 2020 and is projected to reach USD 823.75 billion by 2030 at an 18.2% CAGR, with Industry 4.0 digital-twin and IoT manufacturing now determining which suppliers can deliver at that scale.
Lithium battery cell and PACK production-line design in 2026 splits into prismatic, cylindrical 18650/21700/4680, and pouch architectures, with throughput targets like 15–30 PPM, CTP cell-to-pack structures, and laser-welding stations dominating modular layouts.
Battery energy storage manufacturing equipment for grid-scale, commercial, and residential BESS spans electrode coating, calendaring, stacking, and formation steps, governed by UL 9540, UL 9540A, and IEEE 1547. Specs hinge on capacity, C-rate, round-trip efficiency, and UL-listed inverters.

For power grid hardware, OEM and ODM manufacturing differ on three practical axes: who owns the design IP, who funds NRE and tooling, and how much of the bill of materials the buyer controls. Utilities and EPCs that need grid-specific certifications, custom switchgear ratings, or relay firmware they

Power grid manufacturing cost is dominated by four drivers: copper and grain-oriented electrical steel, transformer and switchgear assembly labor, type-test certification per IEEE/IEC standards, and HVDC converter station complexity. Custom-fabricated structural steel and enclosures, DER aggregation

Industry 4.0 adoption in the power grid is driven by IEC 61968-9, DLMS/COSEM (IEC 62056), IEEE 1547-2018, IEEE 2030.5, and OpenADR 2.0 interoperability profiles, paired with substation IoT sensing, smart-meter data, and real-time power-quality monitoring tied to industrial automation loads.

Power grid manufacturing equipment spans HVDC converter stations, large power transformers, switchgear, and protective devices. The U.S. lacks domestic converter-station manufacturing capacity, while HVDC project cost is dominated by installation timeline rather than equipment BOM.
Electric motor sourcing splits cleanly between OEM and ODM routes, with the trade-off defined by who owns the design, the tooling, and the bill of materials. OEM fits buyers with in-house design teams and IP they must protect, while ODM fits buyers prioritising time-to-market, lower NRE, and accepti

Electric motor production line design hinges on three decisions made before cell layout: spec-driven requirement engineering, the discrete manufacturing steps from stator winding to final test, and the cell/line architecture. Skip any one and cycle time, yield, or NEMA/IEC compliance drifts.

Electric motor process control pairs a final control element (the motor or driven valve) with sensors, controllers, and variable-speed drives in a closed loop. Scalar V/Hz drives, soft starters, and DOL starters cover most industrial duty, with frame sizes 56 to 355+ per IS 12615 for 0.12 kW to 1000
Transformer OEM builds to the buyer's electrical and mechanical spec with the buyer holding IP, while ODM supplies a factory-owned base design that the buyer rebrands or lightly modifies. Choose OEM for custom kVA, voltage, impedance, and enclosure; choose ODM for fast, low-NRE delivery of standard
Industry 4.0 adoption in transformer manufacturing is anchored in IoT-enabled monitoring, AI-driven predictive maintenance, and digital-twin process control, with ROI tied to energy efficiency, uptime, and lifecycle cost. Procurement specs must stay unambiguous and reference concrete standards rathe
Transformer manufacturing quality is governed by stacked standards: IEC, IEEE/CSA, and ANSI for design and test; ISO 9001 for QMS; and IOGP S-720Q (JIP33) for oil & gas procurement with three CAS levels. Buyers should match standard + CAS level + test scope in the RFQ, not just brand.

OEM and ODM for IGBT power modules differ on three decision axes — design ownership, IP, and NRE cost — and the right path depends on whether the buyer is sourcing a standard inverter topology or a differentiated 750–1700 V SiC/IGBT stack.
IGBT manufacturing cost is driven primarily by wafer substrate (40-55%), front-end fab (20-25%), and packaging/assembly (15-20%) of bill-of-materials plus conversion, with 8-inch Si wafer sourcing and module housing grade moving the final price 1.4-2.0x across 2026 SKU tiers. Total-cost-of-ownership

IGBT production capacity planning is a multi-stage, multi-product scheduling problem where fabs must balance wafer-out targets, diffusion-furnace hours, and packaging-line throughput against order priority. The decision points are short-cycle MPS, long-cycle back-end balance, and equipment-bottlenec

OEM vs ODM for power semiconductor converters splits along three variables: design IP ownership, NPI tooling cost, and post-sale firmware control. Pick OEM when volume exceeds 50k units/year and the buyer owns the datasheet; pick ODM for sub-10k lots needing converter reference designs and faster ti

Power semiconductor production line design in 2026 centers on SiC/GaN-ready fabs integrating wafer inspection, laser-assisted bonding, and discrete power-component testing. Build cost is dominated by cleanroom grade, vision metrology, and packaging.

Power semiconductor manufacturing cost is dominated by wafer fab, packaging, and test — three line items that swing 60–80% of total spend depending on device class, with SiC and GaN wide-bandgap parts carrying premium substrate and dicing overhead.

Power-semiconductor fabs running Industry 4.0 stacks report 30–50% direct-labour productivity gains, 10–15% OEE uplift, and 1–3% yield improvement, with wide-bandgap SiC and GaN devices anchoring the smart-fab power chain by 2030.

Power semiconductor quality hinges on FIT-rate screening, reverse-current stability under biased stress, and 100% machine-vision inspection at wafer, die, and packaging stages. Specs worth tracking in 2026: CXP-12/GigE line-scan defect capture, AI-based golden-pose alignment, and SEM/FIB failure ana

NGK will scale AMB substrate output for power semiconductor modules by ~2.5× by FY2026, while global power semis are projected to grow from $48.9B (2022) to $79.9B (2032) at 4.9% CAGR, reshaping capacity planning.

Power semiconductor manufacturing equipment is governed by SEMI S2 (safety), S8 (ergonomics), S14 (risk), S23 (energy/material efficiency), and SEMI F47 (voltage sag immunity), with buyers now writing these into contracts. Selection pivots on three process pillars: wafer handling & inspection, preci

MEMS sensor programs split cleanly between OEM and ODM tracks: pick OEM when you own the mask set and ASIC and need tight process control; pick ODM when you need a packaged, calibrated module on an accelerated schedule. Cost, IP control, lead time, and qualification depth differ enough that the wron
MEMS sensor production lines are designed around silicon-foundry process flow — wafer fab, dicing, die-bond, wire-bond, hermetic package, calibration and test — with MEMS pressure ranges of -100 kPa to 1600 kPa and LGA/DFN footprints driving PCB layout, ground-plane and stencil choices.
MEMS sensor manufacturing cost breaks down into wafer fabrication, MEMS-specific process modules, wafer-level packaging, and final test. Wafer and back-end packaging dominate unit cost, while node choice, process steps, and certification scope move the final bill of materials.

MEMS sensors are the dominant data-acquisition edge device for Industry 4.0 retrofits, pairing sub-mW motion/pressure dies with on-die DSP and IO-Link/WirelessHART backhaul to feed AI/ML process-control loops. Adoption is gated by foundries' ability to deliver near-real-time predictive quality, not

MEMS sensors now anchor 3 mm × 3 mm industrial environmental nodes that fuse pressure, humidity, temperature and gas-channel readouts on one die, while CISCON 2020 proceedings codify MEMS performance attributes for process-control and supervisory loops.
MEMS sensor production capacity planning hinges on three structural realities: a single wafer run takes 12-24 months of qualification for automotive/medical grades, the Bosch-style process flow exceeds three months of fab time over several hundred steps, and individual die-level trimming is mandator
OEM and ODM PCB services differ in design ownership, IP control, and NRE cost, and the right choice depends on whether the buyer holds a finished design or needs the factory's engineering. Guangdong-based factories dominate both models, with ISO 9001:2015 and ISO 14001 the baseline certifications to

PCB cost in 2026 is driven by layer count, board thickness, copper weight, surface finish, and volume tier. A 4-layer 1.6 mm FR-4 prototype lot of 5-50 pieces prices on Chinese instant-quote platforms against parameter choices like ENIG vs OSP finish, with EMS lead times of 15-30 days.

In industrial control, "PCB" most often means a printed circuit board that hosts sensors, transmitters, relays, and signal-conditioning stages inside the instrument enclosure; over 4,800 control-system and instrumentation part families are catalogued on alldatasheet as of 2024-12-19.

PCB manufacturing quality standards in 2026 are driven by IPC-A-600/IPC-6012 acceptance classes, UL94 V-0 FR-4 substrate flammability, and IPC-6013 for flex — with most China OEM shops audited to ISO 9001:2015 and ISO 14001.

PCB production capacity planning requires matching available work-center hours against MPS/MRP demand, modeled on three Oracle-defined tiers: RRP, RCCP, and CRP, with line layers, hole counts, and tolerance stack-up driving the critical bottleneck.

PCB manufacturing equipment selection hinges on matching imaging, etching, plating, and AOI stations to substrate type, layer count, and volume. Prototype shops prioritise direct imaging and quick-turn lines; high-mix facilities layer in ENIG and HASL lines plus automated optical inspection. Equipme

OEM silicon wafer manufacturing builds a buyer-owned design to a buyer's spec, while ODM delivers the foundry's pre-engineered wafer/dummy-wafer/dark wafer platform under the buyer's brand; the two models differ on IP, NRE, lead time, and MOQ, and the right pick depends on process-node maturity vers

Silicon wafer production line design combines ingot heat treatment, multi-wire slicing, lapping, CMP polishing, and cleanroom cleaning, with 8-inch and 12-inch lines now targeting 300,000 wafers/month in new Chinese fabs.

Silicon wafer manufacturing cost is driven primarily by node geometry, mask count, wafer diameter, and packaging tier; budget MPW runs on GF180MCU ship 1,000 dies for $2-$7 per die, while advanced-node wafers carry the bulk of the per-die cost in the fab process, not the silicon substrate.

Industry 4.0 in 300 mm silicon wafer fabs is anchored on GEM300, FOUP-level RFID, AI-driven etch tuning, and predictive maintenance, with the automation segment holding ~15.7% of 300 mm wafer demand in 2025 and growing at a 6.8% CAGR through 2034.
Global silicon-wafer nameplate capacity reached about 974.2 GW by end-2023 (+46.7% YoY), with Chinese mainland holding roughly 97.9% of that base. Planning in 2026 centers on wafer-thinning, large-format 182/210 mm dominance, and Western 200 mm MEMS/power fab expansion.

OEM copper manufacturing builds to a buyer's drawings and brand, while ODM delivers a ready-designed copper product the buyer rebrands. Chinese factories now offer both, with MOQ often 500 kg for copper alloy welding wire and R&D capacity for OEM/ODM. Choose by IP control, tooling cost, and time-to-
Copper manufacturing cost is driven by five layered components: cathode/rod feedstock, energy for smelting and electrolytic refining, labor and overhead, equipment depreciation, and grade-specific compliance. Price tier shifts primarily with LME copper cathode and processing fees, not labor.

Copper producers are deploying Industry 4.0 stacks — autonomous trucks, conveyor CMES, digital twins and AI ore-grade control — to cut freshwater draw and CO2e intensity, with measurable results documented since 2021. Adoption barriers remain cultural and skills-based rather than technical, making c
Copper process control and instrumentation centers on tinned-copper instrumentation cable (No. 18 AWG, twisted pair, 100% Al/polyester shield, 300 V) plus 24 VDC field devices and fiber-to-VFD architectures, with PLC panels grounded on 25 mm × 6 mm copper flats.

Copper manufacturing equipment in 2026 spans tube/pipe production lines, brass plumbing fittings, copper-bearing heat-exchanger fin tubes, and supporting metal-fabrication machinery. Selection is driven by material grade, tonnage class, tube OD/wall tolerance, and IEC/UL standards for downstream ele

Aluminum product cost in 2026 is driven primarily by alloy grade, forming process, and order volume, with finished-fabrication premiums of 2–6× over raw billet commonly observed across North American shops. Die casting, extrusion, and roll-formed fabrication each carry distinct cost structures tied
Aluminum producers are deploying Industry 4.0 stacks—IIoT sensors, CPS, and digital twins—across smelting and extrusion lines, with IndustryARC tracking double-digit CAGR for industrial-IoT spend through 2030. Adoption is gated by cybersecurity, OT/IT integration, and capex, not by technology r
Aluminum manufacturing quality is governed by alloy-temper designations, ISO 9001-based QMS, casting-method-specific defect controls, and process traceability from melt to finished extrusion or casting. This 2026-07-31 spec map shows how extruders, foundries, and custom fabricators apply those stand

Aluminum production capacity planning ties electrolysis cell count, potline amperage, and downstream casting/die-casting throughput to a master production schedule. For 2026, capacity planning blends smelter restart programs (e.g., 430,000 t/y at Yingkou Zhongwang) with downstream OEM ramp-ups acros

Aluminum manufacturing equipment spans extrusion presses (580-2750 US ton), regenerative melting furnaces, degassing units, and downstream CNC/melting gear. Selection hinges on billet diameter, alloy, annual tonnage, and the tolerances your downstream CNC process can actually hit.

OEM builds to the buyer's drawing and brand; ODM builds on the supplier's own design and IP. For steel buyers the decision turns on who owns the tooling, who funds NRE, and how much design latitude the mill can absorb.
Steel production line design in 2026 hinges on matching capacity, energy source, and downstream coil grade. Reference points include C/Z purlin roll forming lines at US$12,500/set, 100-10,000 t/month galvanized strip supply, and induction furnace setups from 100 Set/year capacity.

Steel manufacturing cost is dominated by raw material (~60-70% of conversion cost) plus energy and fixed cost, with iron ore, coking coal, and scrap as the swing drivers. Route choice — BOF vs EAF — and downstream processing (alloying, rolling, coating) set the final $/ton band.
Steel mills adopting Industry 4.0 build AI/ML metamodels, IoT sensor meshes, and digital twins, but barriers — cost, skills, data silos, and decarbonisation pressure — still gate rollouts. A 2023 self-assessment framework ranks these barriers and case-tests them on BF-BOF and EAF producers. For
Steel process control relies on a four-variable backbone (pressure, level, flow, temperature) wired through ISA-S5.1 symbology and copper-clad-steel instrumentation cable, with SIL3 safety PLCs per IEC 61508 on hazardous gas lines. Sensor selection hinges on pressure range and media.

Steel manufactured for structural, pressure, and architectural service must meet ISO, ASTM, ASME, and EN grade specifications, with quality verified by XRF/OES composition checks, mechanical testing, and dimensional inspection under ISO 9001 systems. Mills like Orrcon Steel (Australia) and Karachi S

Steel manufacturing equipment selection hinges on route, capacity, and alloy specification: EAF shops rely on XRF/LIBS analyzers and non-contact thickness gauges, while integrated mills (BOF + continuous caster + hot strip) layer emissions CEMS over the same QA stack. Match equipment to the steel gr

OEM and ODM are distinct B2B manufacturing models: OEM builds to the buyer's spec, ODM designs and sells an existing product the buyer rebrands. For rare-earth sourcing, the OEM route fits buyers holding proprietary alloy or magnet IP, while ODM suits distributors needing fast SKU turnover.
Rare earth Industry 4.0 adoption centers on digitalising solvent-extraction separation lines with PLC, flow-meter, and pressure-sensor loops; RETi's single-pass column chemistry and McKinsey's SIR assessment frame are the concrete 2026 reference points.
Rare-earth processing plants use solvent-extraction trains and selective crystallizers where pH, ORP, conductivity, flow, and level instrumentation must hold tight bounds because neighbouring lanthanides differ by only ~0.01 Å in ionic radius, making online measurement the rate-limiting step in sepa
Rare earth manufacturing quality hinges on assay-grade purity bands (99.5%–99.999% REO), ICP-OES/XRF verification, and ISO 9001-anchored QMS for oxides, metals, and NdFeB magnets. Buyers should fix the grade (3N–5N), the test method, and the standard before pricing.
Rare-earth manufacturing equipment spans CIP presses, vacuum induction furnaces, sintering lines, and solvent-extraction cells sized for oxide throughput of 10–600 t/day per plant. Selection is driven by feedstock form (oxide vs metal), purity target (3N–5N), and downstream use case.

PEM fuel cell stack cost is dominated by the MEA and Pt catalyst (~40-50% of stack cost), with bipolar plates and BOP adding the remainder; total system manufacturing cost is targeted below $50/kW at high volume per the U.S. DOE 2030 milestone.

PEM and SOFC hydrogen fuel cell stacks require tight control of stack temperature (60-80 C PEM), cathode/anode pressure differential below 30 mbar to protect the membrane, dew-point air humidification, and hydrogen purity verification. The dominant instrumentation on the loop is mass-flow, different
Hydrogen fuel cell manufacturing quality is governed by ISO 14687 for fuel purity, with ISO 14687-2:2012 withdrawn and consolidated into ISO 14687:2019 for PEM road vehicles, plus stack-level controls on MEA, bipolar plates, and BOP leak/integrity testing for 2026 line builds.

PEM fuel cell stacks are moving from pilot to gigawatt-scale line planning, with stack output now in the 40-60% net-efficiency band versus ~20% for internal combustion. Capacity planners must lock in air-filtration, membrane, catalyst, and BOP supply against the DOE/FCEV roadmap and Chinese OEM roll

Hydrogen fuel cell manufacturing equipment spans stack-assembly, MEA coating, and balance-of-plant component production; this guide maps the 2026 process flow with the process, materials, and tolerances engineers specify at each stage.

OEM builds to a buyer's design while ODM ships an existing manufacturer-owned design that the buyer rebrands; the choice depends on who owns the IP, who funds NRE tooling, and how fast the part must reach a target market, with additive manufacturing reshaping both models.
Additive manufacturing part cost is dominated by material (30-60%), machine time (15-30%), and post-processing/labor (20-40%); the largest swing factors in 2026 are powder/feedstock grade, build volume utilization, and post-process certification rather than printer depreciation.

Additive manufacturing process control relies on in-situ thermal, optical, and melt-pool sensors, closed-loop PLCs, and digital-twin simulation to hold part density and dimensional tolerance within spec on metal and polymer AM lines.
Additive manufacturing quality control in 2026 hinges on three converging practices: in-process melt-pool monitoring via MWIR coaxial imaging, post-build CT-based non-destructive evaluation, and qualification to ASTM/ISO AM process standards. Adoption is concentrated in aerospace and nuclear compone

Additive manufacturing capacity planning now hinges on digital-twin simulation, demand variability, and supply-chain resilience metrics, with discrete-event models linking build-volume utilization to lead-time and inventory risk. Practitioners should treat AM capacity as a flexible-buffer asset, not
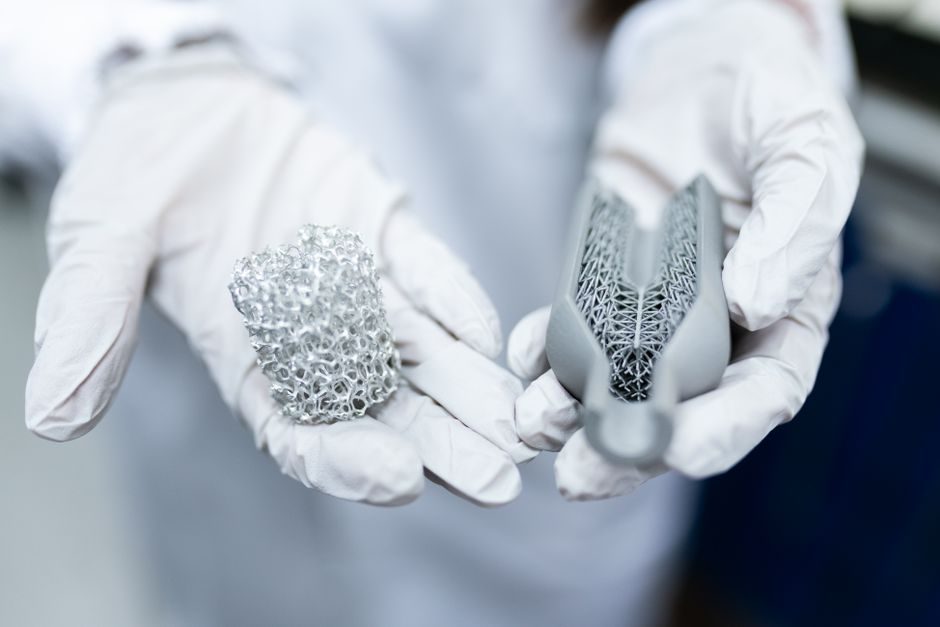
Additive manufacturing (AM) equipment spans seven process families — powder bed fusion, directed energy deposition, material extrusion, vat photopolymerization, binder jetting, sheet lamination, and material jetting — with build volumes from 50 mm prototype cubes to multi-meter WAAM structures, gove
OEM vs ODM in 3D printing comes down to who owns the design file: OEM factories build to the buyer's spec, ODM factories contribute their own design and ship under the buyer's brand. Spec-driven buyers should default to OEM; brand-builders with no in-house CAD should default to ODM. Total cost, IP,

3D printing production line design in 2026 hinges on slicing-software-driven workflow choice, on-premises vs cloud slicing stack, and FDM/FFF polymer process selection before hardware layout decisions. Spec-driven designers weigh STL/OBJ pipeline, material handling, and per-part throughput before co
Industrial 3D printing part cost is driven by build volume, material choice, accuracy tier, and certification; service networks quote in real time, with FDM prototypes from 1 business day, SLS/MJF from 3 days, and dimensional tolerances between ±0.3% and ±0.5%. Material is the largest variable

3D printing adoption inside Industry 4.0 frameworks is being pulled by MOSFET-controlled digital material printers, high-performance-polymer systems, and SME supply-chain financing pilots. The decisive selection variables are connectivity layer, pilot-to-rollout conversion rate, and post-processing

3D printing capacity planning selects printer models and quantities against projected demand, balancing fill density, batch due dates, and printer-specific fit. A two-stage Shapeways case shows automated batching raises printer throughput by roughly 10% versus manual planning.
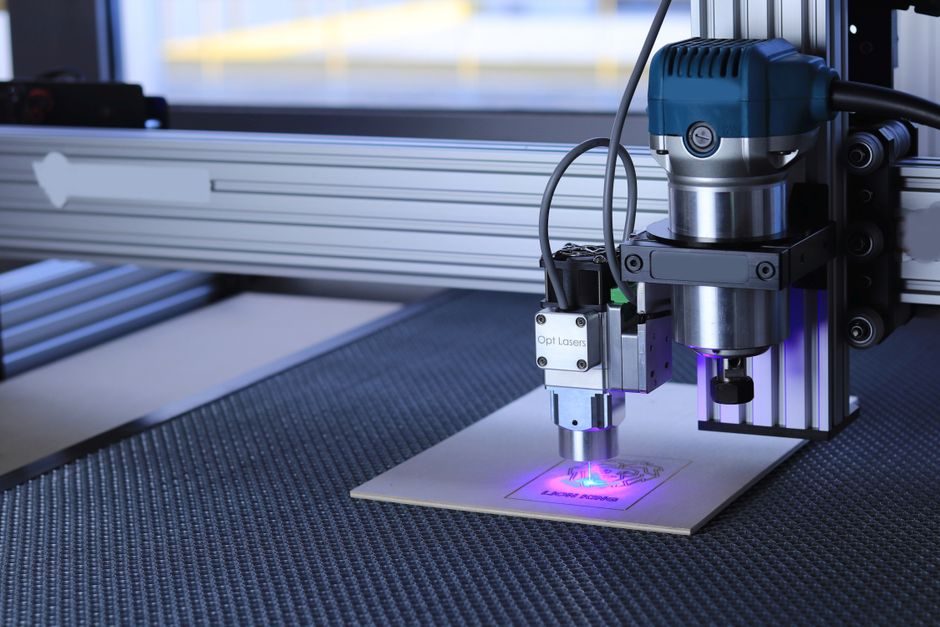
Industrial 3D printing manufacturing equipment spans FDM, SLA, SLS, MJF, DLP and metal AM platforms, with process choice driven by part size, tolerance, material and annual volume rather than printer brand.
Industrial robot buyers in 2026-07 choose OEM when they own the design, BOM and brand, and ODM when they need a Guangdong-tier supplier to deliver a ready-engineered 6-axis or cobot cell under the buyer's label. On Made-in-China.com, OEM/ODM dual-capable robot factories cluster in Guangdong, with en
Industrial robot production line design is governed by ISO 8373 subsystems, IPC Class 3 electronics, and a six-stage workflow that pairs process analysis with ERP/MES integration before cell layout. Robotic cells beat fixed automation on repeatability and ergonomic safety but require ROI modelling a
Industrial robot costs are driven by the mechanical structure (body, joints, RV reducers), the servo drive and motion-control stack, the controller electronics, and the end-effector package; on Made-in-China, factory-direct welding/palletizing units list US$208,000–286,000 per set MOQ 1, while ARK I
ISO 9283 governs industrial robot performance testing, while ISO 10218-1/10218-2 and ISO/TS 15066 define safety and collaborative-operation thresholds. Repeatability ±0.02 mm and pose accuracy are the headline metrics buyers compare on a spec sheet, with cycle-time verification under defined payload

China's industrial robot installed base now exceeds 50% of the global total, with 2022 output above 443,000 units and 1.5 million robots operating in factories, reshaping capacity-planning math for integrators and end users. (2024-07) (2026-07)

Industrial robot cells for 2026 spec-driven buyers pair a 6-axis arm in the 6-20 kg payload class with Italian-style modular wiring and dual safety circuits; selection hinges on reach, repeatability, and standards mapping rather than brand alone.

A spec-driven robotic production line in 2026 pairs a 4-DoF SCARA with a 5-DoF pick-and-place module and validates it offline in RobotStudio before any steel is cut; cycle time, payload, reach, and DoF budget, not hype, decide the build.
Industrial robot cell cost is driven by manipulator hardware, integration engineering, and end-of-life remanufacturing, not sticker price alone. ABB's 12,000-unit remanufacture base across six global centres proves the spare-parts and rebuild channel is a real cost lever for 2026 procurement.
Robotics-led Industry 4.0 adoption pairs industrial robots with IIoT, AI, and cyber-physical systems on the shop floor; China leads installed base under Made in China 2025, while Europe and the US push collaborative and predictive-maintenance rollouts. Spec-first selection now hinges on safety class

Robotics manufacturing quality standards remain fragmented, with industry experts as of 2024 calling for unified industrial regulations after a service robot injured a bystander in Shenzhen. Cobots, ISO-aligned safety functions, and end-of-arm tooling tolerance define the practical spec envelope buy

Robotics production capacity planning applies three-layer capacity logic — RRP, RCCP, CRP — to robot cell build-out, with Master Production Schedule input and 12-36 month horizons. Critical inputs: cycle-time variance below 15% and validated work-center hours per.
OEM vs ODM for server hardware defines who owns the design, the BOM, and the firmware stack: OEM builds to the buyer's spec, ODM provides a reference platform the buyer re-brands. For 1–1000-site enterprise rollouts, OEM suits regulated workloads; ODM fits price-driven hyperscale racks.
Server hardware production line design ties rack-density, power/cooling, validation, and BoM traceability together. Engineering gates include identical-node hardware, 32 MB JRE disk minimum, 1-2 GB evaluation RAM, and 400 MB binary footprint, with an 8 GB local-disk buffer for 250,000-entry director

Server hardware manufacturing cost breaks into CPU/SoC silicon, DRAM/NAND memory, PCB + chassis fabrication, power-conversion hardware, and assembly/test, with bill-of-materials driven by tier, certification load, and volume. Microsoft's April 2025 documentation of Windows Server 2025 boot/reset fau

Server hardware in process control and instrumentation must meet IEC 60079 hazardous-area, redundancy, and HART diagnostics rules. Specs converge on industrial PCs, 1:1 redundant controllers, failsafe alarm contacts, and Windows Server 2012/2019 OS support per 2026 utility and OEM guidance.

Server hardware manufacturing quality standards in 2026 hinge on ISO 9001 QMS, 80 PLUS / ENERGY STAR power-supply efficiency tiers, and documented component-level validation. Enterprise sizing rules pair RAM, RAID, and NIC tiers to site counts from 1 to 1000, with ECC memory and hardware RAID contro

Server hardware capacity planning in 2026-07 vendor docs treats it as non-exact science, requiring prototype load tests at CPU saturation, with IOWAIT and cache hit-rate thresholds per Sun Java Directory Server (target response 10 ms, IOWAIT under 10 ms).

Data center manufacturing cost is driven by five blocks: server compute (CPU/GPU/HBM/PCB), networking fabric, mechanical and electrical infrastructure, embodied carbon amortisation, and software-orchestration overhead. The biggest single lever is whole-system embodied cost — peripherals like mainboa
Data center Industry 4.0 adoption now converges on digital-twin commissioning loops, AI/ML-driven process control, and green-finance-linked retrofit programs, with the constraint that 2026 builds must tie IIoT instrumentation back to live PUE and water-use telemetry.
Data center manufacturing quality standards now anchor on closed-loop MES/QMS stacks: Siemens Opcenter MOM ties statistical process control to traceability, Oracle Process Manufacturing Quality Command Center runs sample, deviation and instrument-calibration dashboards against Oracle EBS,
Data center production capacity planning maps six disciplines — power, cooling, facilities, networks, storage, and sustainability — to rack, row, and room-level budgets, with TIA/BICSI/Uptime recommendations and DCIM tooling. Alibaba's Apsara Stack shows the model scales from a single hall to hundre
Data center manufacturing equipment spans the full build-to-decommission stack: from semiconductor fab tools sized at USD 166.35 B in 2025, to UPS/PDU/generator removal under EPA-certified disposal rules. This guide maps the equipment classes, AI/OT data ingestion paths, and selection gates for 2026

OEM and ODM are distinct wind-turbine sourcing routes: OEM = buyer-owned design, contract-built; ODM = factory-owned design rebadged or lightly customised. Choose OEM when IP control and certification ownership matter; choose ODM when speed-to-market and lower NRE cost outweigh brand differentiation
Wind turbine production line design in 2026 centers on modular 10-20 MW platforms, Bladed/Ansys-simulated load cases, and floating offshore sub-assembly flow, with CRRC's 20 MW Qi hang setting the scale benchmark from October 2024.

Wind turbine Industry 4.0 adoption in 2026 centers on the IEC 61400-25 communication standard and the RAMI 4.0 Asset Administration Shell for digital twins, with offshore wind leading real-time SCADA, predictive maintenance, and full lifecycle data interoperability deployments across new plant build

Wind turbine process control and instrumentation centers on a PLC/PAC main controller supervising pitch, yaw, torque, and grid-sync loops, with SCADA, condition monitoring, and IEC 61400-25 / 61850 communications across the turbine and park. Hot-failure components remain gearbox, blades, pitch and y
Wind turbine production capacity planning rests on the capacity factor formula CF = (Annual Energy Yield / (Rated Capacity × 8760)) × 100, combined with spatial zoning to size installed MW for a given land area. Engineers should select HAWT or VAWT architectures against a 30–50% onshore capacity-fac
Wind turbine manufacturing equipment selection splits into utility-grade HAWT platforms (Vestas, Goldwind) and small/medium HAWT+VAWT suppliers from Guangdong and Jiangsu. Spec gates are rotor diameter, rated power, IEC 61400-1 design class, and tower type. Steel-concrete hybrid towers from Goldwind
Photovoltaic OEM builds modules to a buyer's locked spec; ODM supplies a pre-engineered reference design the buyer rebrands. The right pick depends on who owns the BOM, the IEC 61215 / UL 61730 certification, and the encapsulation stack, not headline price alone.

Crystalline-silicon module cost is still dominated by silicon wafer production, with ingot crystallization, wafer slicing, and high-temperature diffusion firing the three largest cost drivers. Electrodeposition of solar-grade silicon from SiO2 has demonstrated 3.1% cell efficiency and 40-50% of

Photovoltaic Industry 4.0 adoption centers on AI vision inspection, laser cutting, and automated EVA layup lines replacing manual cell and module handling. Specifications are converging on sub-millimeter crack detection, robotic layup tolerance under 0.5 mm, and dark-light EL defect classifiers. The

IEC 62941 remains the defining quality-system standard for terrestrial PV module manufacturing, with DIN EN IEC 62941:2021 active in EU procurement and downstream IEC/UL/IECQ product standards still binding cell and module inspection routines. A spec-first 2026 PV line ties PERC, HJT, TOPCon and per

PV capacity planning now hinges on integrated energy system (IES) sizing with multi-criteria optimization, where reinforcement learning (RL) and metaheuristic algorithms (SSA) size PV–wind–biomass–hydrogen–battery stacks for industrial parks and microgrids. Global module production capacity
PV module manufacturing equipment in 2026 spans ALD film-guide automation, machine-vision defect detection, wireless pneumatic subsystems, and IEC-driven PV test chambers, with selection driven by 25–30-year field life targets and standards like IEC 61215 and IEC 61730.
Solar panel production line design now spans turnkey 5 MW to 600 MW layouts from Chinese OEMs covering stringer-layup, lamination, framing, and IV/EL test, with ISO 9001:2015, CE, and IEC 61215/61730 compliance as the dominant specification baseline for 2026 export builds.
Crystalline-silicon PV modules cost roughly $0.10-$0.30/W at the BOM level in 2026, with silicon wafers, cells, glass, aluminum frame and EVA encapsulant as the five cost drivers, scaled by tier-1 capacity and TOPCon/PERC process choice. A 20-30 panel residential installed system runs $24,000-$36,00

Solar panel makers applying Industry 4.0 are layering AI/ML metamodels, ICME, and IIoT telemetry onto cell-string-module lines, with IEC 61215 and IEC 61730 still gating the product side and ISO 9001 the process side.

PV cell-to-module process control relies on pyranometer-calibrated irradiance monitoring, inline EL imaging, and HART/IO-Link thermocouple loops to hold cell efficiency within ±0.3% across string soldering and lamination stages. The full instrument stack — pyrheliometer, EL tester, reflow profiler,
Solar panel quality rests on IEC 61215, IEC 61730, UL 61730, and ISO 9001 with TOPCon and HJT modules now dominant in ENF's 91,900-panel directory and bifacial share above 3,300 entries.
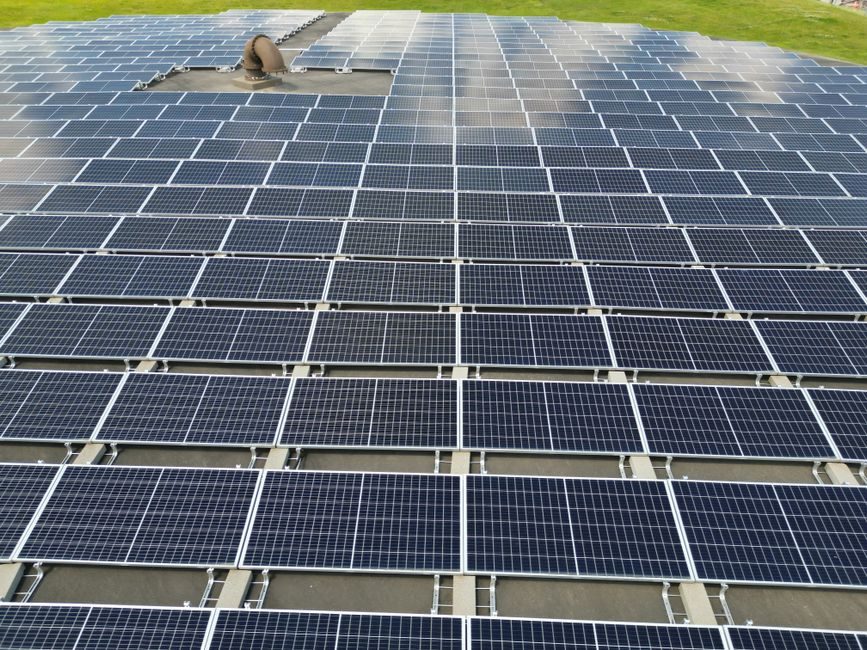
Turnkey solar PV module lines now ship in 5MW-1GW annual tiers, with N-type TOPCon half-cell lines rated 610-750W per panel at FOB $0.073-$0.087/W. Capacity planning must balance cell technology shift, MW-tiered line CAPEX, and grid-certification lead time.

A solar panel manufacturing line is a sequence of tabber-stringer, layup, laminator, EL tester, framing and junction-box welding stations, with line layouts now covering 166/182/210 half-cut cells up to 800 W shingled modules. Turnkey suppliers such as Horad and Zenith Solar ship the full stack, whi

OEM vs ODM in EV manufacturing splits on who owns the platform: branded OEMs control architecture, IP, and homologation, while ODM/OBM suppliers in Jiangsu, Hainan, Guizhou and Hong Kong deliver turnkey chassis, BMS, and motor-controller kits at MOQs from 1 to 100 pieces.
A modern EV production line combines stamping, welding, painting and final assembly at >95% welding automation, with 350+ AGV/AMR units on a 400,000 m² site targeting VOC below 4.4 g/m². Digital twin and HIL simulation front-load the design phase.

EV process control and instrumentation now hinges on regenerative battery cyclers, CAN-based vehicle instrumentation, and EVSE test platforms aligned to SAE J1772 and GB/T 18487.1, with Chroma and Curtis China as active suppliers. Selection turns on test coverage from cell to pack, CAN-programmable
EV manufacturing quality in 2026 is converging around digital-twin driven process control, with Siemens positioning comprehensive twin-of-production as the primary lever for ramp-up speed and cost. Kennametal's 2026 EV/HEV tooling program targets aluminum alloys, quenched-and-tempered steel, an

EV production capacity planning hinges on three coupled forecasts: new-vehicle demand, end-of-life battery returns, and the build-out rate of charging infrastructure, each with a 3-7 year decision horizon.

EV manufacturing equipment spans cell stacking, module/pack assembly, EVSE test, and PPE; spec by cell format, ISO 15118 conformance, ATEX/IECEx zone, and IEC 62196 connector type, not by brand.
EV battery programs split into two procurement lanes: OEM production (build-to-print, brand owns the pack design and cell spec) and ODM service (factory-led cell-format and module-pack layout under the buyer's badge). For 2026 sourcing, OEM fits buyers with a locked BoM and validated supply chain; O
EV battery production line design in 2026 separates prismatic, cylindrical, and pouch cell formats across dedicated module-pack lines, with cell-to-pack welding, AGV/RGV material flow, and EOL testing as the dominant process nodes.

Lithium-ion cathodes are the single largest cost driver in EV cells, followed by separators, electrolyte, and anode materials, with the global EV battery market sized at USD 103.04 billion in 2026. Material chemistry, form factor, and capacity tier set the spec-engineering boundaries that govern lin

EVE Energy released Open-Source Battery 4.0 AI Battery on 2026-05-09 in Huizhou, defining the product around full-perception, deep-thought, and self-evolution capabilities. The 815 Ah LM815 cell integrates pressure, temperature, and EIS sensing, with -30°C energy retention above 90% and SOC error be
EV battery cell-making quality hinges on electrode coating uniformity, moisture control under 100 ppm in dry rooms, and traceability at every step, with a 2025 bankruptcy auction of $82 million of Northvolt equipment underscoring capital risk. The defensible spec map pairs laser-based electrode insp

EV battery production capacity planning hinges on three dials: gigawatt-hour line scale, lithium-ion cell form factor mix, and the share of localised gigafactory output. MarketsandMarkets sizes the global EV battery market at USD 103.04 billion in 2026, expanding to USD 168.95 billion by 2035 at 5.6
Lithium battery production line design in 2026 spans cell-format-specific electrode preparation, automated module/PACK assembly, and laser welding, with turnkey vendors offering cylindrical 18650/21700/4680, pouch, and prismatic lines up to 587Ah. Key choices include cell format, throughput
Lithium battery manufacturing cost is dominated by cathode material (typically 30-45% of cell cost) and cell format choice, with prismatic LFP cells generally delivering the lowest cost per kWh at pack level. Total cost-of-ownership swings sharply with chemistry (LFP vs NMC), format (cylindrical 186
Lithium battery Industry 4.0 adoption centers on continuous-wave laser welding for tab, valve, and shell seams at 1.5 mm or narrower pole-strip widths, paired with PLC-driven multi-axis lines delivering 20 GWh-class annual throughput. Vendor footprint spans Jiangxi LiFePO4 cell plants to Jiangsu 130

Lithium battery cell and pack manufacturing relies on tight moisture, electrode-coating, and electrolyte-filling control to keep defect rates in the low single digits. Process control and instrumentation for Li-ion lines now routinely combines dew-point meters below -40 °C, PLC-based electrode coati
Lithium battery cell and pack production in 2026-07 is governed by a layered quality stack: IEC 62133, UN 38.3, UL 1973, GB/T 36276, IATF 16949 for EV packs, and process-vacuum moisture limits below 1 ppm for dry rooms.

Lithium battery manufacturing equipment covers electrode coating, slitting, winding, electrolyte filling, formation, and vacuum drying stages, with Chinese suppliers such as Tianyong and Wuhan Great leading the one-stop turnkey segment. Buyers should match equipment class to cell format, throughput

OEM builds to the buyer's exact spec, ODM ships a pre-engineered reference design the buyer rebrands; for AI chips, the OEM/ODM split is dominated by TSMC-style foundry, CoWoS packaging, and HBM stacking, with the two paths scoring differently on NRE cost, IP control, and time-to-tape-out.

AI chip total cost is driven by wafer fabrication, advanced packaging (CoWoS/2.5D), HBM stack, and substrate; mask set, yield, and node choice move unit price more than design fees. Reference cost ranges are scarce, so this article ranks the cost drivers qualitatively and uses process-engineering ru

AI chip demand is now the dominant capital driver for Industry 4.0 retrofits in 2026, with edge inference hardware, industrial GPUs, and AI/ML metamodel software pulling foundries, casting lines, and semiconductor fabs toward data-centric control. Plants that pair AI silicon with sensor-rich retrofi
AI chip manufacturing equipment spans nine front-end and back-end stations — from immersion lithography to wafer-level packaging — and the dominant 2026 build pattern pairs EUV-class steppers, hybrid bonding tools, and AI-driven EDA on a single design-to-tape-out flow.

Semiconductor OEM vs ODM manufacturing hinges on who owns the design: OEM builds to buyer-supplied specs, while ODM leverages the factory's own platform IP and reference design. For fab-adjacent buyers, OEM is the default when process know-how is proprietary, and ODM wins on time-to-market for commo

A semiconductor production line is a multi-stage complex manufacturing system combining laser processing, wafer inspection, and automated handling, with scheduling and dispatching strategy directly controlling queue length, waiting time, and overall OEE.

Semiconductor manufacturing cost is dominated by wafer fabrication, photomask sets, packaging, and test, with leading-edge nodes (3 nm/2 nm) pushing mask sets above $50M and single-wafer processing past $20,000. Cost drivers include node geometry, EUV/High-NA lithography, yield, packaging complexity

Semiconductor Industry 4.0 adoption in 2026 centers on GEM 300 cybersecurity upgrades, gRPC/TLS pilots, and E192 equipment-adoption ballots from SEMI's Information & Control Committee, paired with smarter fab-side controls and supply-chain pressure on small manufacturers.

Semiconductor fab quality rests on three layered standards: 40 CFR Part 63 Subpart BBBBB (NESHAP) for emissions, SEMI F47 for voltage-sag ride-through, and SEMI EDA/inspection specs for sub-micron defect control. A 2026 spec map with material, tolerance, and audit criteria is below.

Semiconductor production capacity planning is a multi-stage stochastic decision problem that balances 29+ technology categories across multiple fabs, with wafer-fab cycle times of 100-500 operation steps driving the lot-release logic. Vendor platforms such as Oracle JD Edwards EnterpriseOne implemen
Edge computing gateways now anchor smart-manufacturing data planes, with sub-512 MB open-source stacks challenging commercial units that consume 1-4 GB and cost ¥5,000-50,000. EdgeLite Gateway supports 22 protocols out of the box and cuts acquisition-system build cost by over 50% per the May 2026 fi

Edge computing gateways consolidate 20+ industrial protocols — Siemens S7, Modbus TCP/RTU, OPC UA, IEC 104, DL/T 645, PROFINET, EtherNet/IP — into one Linux box, cutting acquisition cost over 50% and alarm response from hours to seconds, per 2026-05 EdgeLite Gateway field data. Manufacturing ed

5G industrial modules now underpin smart manufacturing by enabling URLLC, mMTC, and eMBB on a single cellular layer, with private 5G networks cited as the dominant factory deployment pattern. Adoption is anchored in 3GPP Release 16/17 features, with target URLLC air-interface latency below 1 ms, and
Industrial Ethernet/IP hardware captured 74.1% of segment revenue in 2020 and the wider market was sized at $9.20B that year, growing at a 10.1% CAGR through 2026-2031 per IndustryARC. North America held 37% of 2020 share, while Schneider's Modicon M580 bridges EtherNet/IP and Modbus TCP on a single
DirectIndustry's 2026 industrial measuring-instrument index lists 549 manufacturers and 1,471 products, with Rockwell's 11th State of Smart Manufacturing report and Toshiba metal-industry gauges framing 2026 spec priorities for connected, autonomy-ready plants.
Industrial measuring-instrument manufacturing spans sensor element fabrication, electronics assembly, calibration, and enclosure integration under ISO 9001 quality systems, with BPMN used to model production flow across 10+ discrete operations per instrument.

Abrasives smart manufacturing pivots from standalone CNC grinders to fully connected lines: IoT-linked wheel dressers, real-time spindle load monitoring, and closed-loop force/vibration control cut scrap rates and energy per part. The 2026 deployment pattern combines MES/QMS software, vision-based s
Bonded abrasive manufacturing combines a chosen abrasive grain (Al₂O₃, SiC, zirconia alumina, or ceramic) with a paper, cloth, or fibre backing and a resin or glue bond. Electrostatic grain coating at 50–100% coverage defines open- vs closed-coat performance, and the final size coat plus curing sets

Smart manufacturing and automation in industrial coatings plants now hinges on AI-driven process control, cobot/6-axis integration, and IIoT data platforms, with Rockwell, Allied Automation, and Applied SmartFactory publishing integration playbooks dated June–July 2026. Adoption centers on PLC + HMI
Industrial coatings manufacturing combines resin synthesis, pigment dispersion, let-down blending, and quality-controlled filling to deliver protective and decorative films. The process spans raw material weighing, high-speed dispersion, let-down thinning, filtration, and packaging under ASTM-tested

Smart manufacturing in specialty chemicals now centers on recipe-integrated process control, with the global market projected at USD 953.9 billion by 2027 and a 5.0% CAGR through that horizon, driving tighter sensor, valve, and metering specifications across batch and continuous plants.

Activated carbon is manufactured in two main routes — steam activation of charcoal at 800-1000°C and chemical activation with ZnCl2, H3PO4 or KOH at 400-700°C — yielding powdered, granular, and pelletized grades for water, air, gold-recovery, and energy-storage use.

Polyamide thin-film composite RO membranes dominate smart-manufactured desalination lines, with 50,000 m² automated workshops, IoT-integrated robotics, and AIQC reducing chlorine intolerance and pH-window failure modes at scale.
Reverse osmosis (RO) membranes are thin-film composite polyamide structures, typically 0.1-0.3 µm dense skin over a 100-300 µm polysulfone support, operating at 100-800 PSI feed pressure depending on salinity. TFC aromatic polyamide dominates over cellulose acetate due to higher rejection and biolog

Smart water treatment membrane manufacturing in 2026 combines automated RO, UF and nanofiltration production with PLC/SCADA-driven plant automation, delivering energy savings and closed-loop chemical recovery across industrial process lines.

Membrane-based water filtration spans microfiltration, ultrafiltration, nanofiltration, and reverse osmosis, each defined by a nominal pore size band and a target rejection class. Manufacturing flow centers on phase inversion of polymeric cast films, with polysulfone, polyethersulfone, polyamide thi

Pharmaceutical equipment smart manufacturing in 2026 centers on GMP-compliant water treatment, pure-steam generation, aseptic filling, and Track & Trace lines specified against cGMP, FDA 21 CFR Part 11, and GAMP 5. Selection is driven by batch-record integrity, isolator-grade containment, and OEE ta

Smart food processing lines in 2026 stack ABB-class DCS, PLC and drives over hygienic stainless equipment to automate sorting, washing and packaging under FDA/USDA and FSMA rules, with optical sorters, UV-C disinfection and robotic handling driving throughput.

Food processing equipment manufacturing spans stainless-steel fabrication, hygienic open-frame design, dry-ingredient handling, and custom further-processing lines. Selection is driven by material grade, CIP capability, and food-contact compliance, with specialist OEMs covering dairy, bakery, and po

Packaging machinery is shifting to integrated smart lines where automated filling, sealing, coding, palletizing and inspection run on one MES/SCADA stack, with the 33rd Sino-Pack (3-6 March 2027, Guangzhou) organising its 2026-2027 floor plan around that "Smart Packaging Total Solution" theme. Buyer

Packaging machinery manufacturing spans VFFS bagging, shrink wrapping, palletizing, and end-of-line integration, with Chinese OEMs covering HL3000-class shrink lines at HL2000 NC stacking speeds. Selection hinges on form-fill-seal format, throughput, film spec, and CE/ISO 9001 compliance, not market

Cold chain equipment makers are absorbing smart-manufacturing patterns from the IC fab line—AI-driven process control, ultrasonic non-invasive sensors and equipment-intelligence stacks—to automate IQF freezers, spiral tunnels and vaccine carriers across 50+ export markets.

Cold chain equipment manufacturing spans five integrated process blocks — insulated enclosure fabrication, refrigeration circuit assembly, IQF/spiral freezing lines, transport cold-box build-up, and biomedical-grade temperature control — with throughput bands from 200 kg/day to 30 T/day and certifie
Industrial refrigeration spans 10 kW-10 MW systems cooling at -50°C to +20°C, with compressors (piston, screw, scroll), heat exchangers, and ammonia or CO2 refrigerants driving chemical, food, and gas-processing plants.

Compressed air systems are built around four process blocks: compression, treatment, storage, and distribution, with screw, reciprocating, and centrifugal machines split across plant pressure tiers. Selection hinges on required pressure, duty cycle, air quality class, and total cost of ownership rat
Smart manufacturing and automation are reshaping industrial filter production and integration, with 2026 platforms like Renishaw Central and Rockwell's FactoryTalk closing the loop from media cartridge build to inline ΔP monitoring. Plants pair on-machine metrology with IIoT pressure sensors to pred
Industrial filter manufacturing combines five standard process steps — media selection, pleating/corrugation, cartridge assembly, housing machining, and integrity testing — anchored by micron ratings, ISO-class cleanroom assembly, and differential-pressure validation across pharmaceutical, chemical,
Smart pneumatic actuators now ship as quarter-turn and linear modules with on-board position feedback, HART/IO-Link diagnostics, and SIL ratings, cutting valve automation wiring time on new plants. Bettis, ABB, Bimba, and Wuxi suppliers cover the 0.125-120 in stroke and 8,000-piece/month tiers.
Pneumatic actuator manufacturing centers on three families — rack-and-pinion, scotch-yoke, and linear/straight-stroke — built from CNC-machined aluminum extrusions, die-cast end caps, and injected polymer seals. Chinese OEM lines now publish 8,000-piece monthly capacity with CE certification as the
Smart hydraulic cylinder manufacturing in mid-2026 centers on integrating embedded linear position sensors, electro-hydraulic closed-loop control, and IoT-enabled condition monitoring into standard and custom cylinder production, with predictive-maintenance diagnostics and remanufacturing automation
Hydraulic cylinders are manufactured through tube honing, piston-rod hard-chrome plating, precision boring of barrels, seal-groove machining, sub-assembly and pressure testing, with material selection driven by pressure class, stroke and duty cycle. The global market for hydraulic-cylinder manufactu

Taiwan's EASYLINK Industrial is building a 40,000 m² fastener plant in North Kaohsiung Industrial Park for 2027 start-up, deploying ASRS warehousing with 6,000 storage locations, 52 optical sorters, and cloud-based AI process monitoring as a benchmark for smart fastener manufacturing automation.
Industrial fastener manufacturing pairs hot forging, cold forming, heat treatment, thread rolling and surface finishing in a fixed sequence; end-use segments include oil & gas, wind power, rail, heavy truck and aerospace, with material grade and NDT scope driving the spec.
Automated furnace systems are now adopted across more than 28% of integrated ferrochrome producers, with smart-furnace retrofits cutting maintenance downtime 6% and lifting smelting efficiency 16% in 2025. The smart-manufacturing push is being driven by stainless-steel offtake (75% of FeCr demand) a

Ferrosilicon (FeSi) is made by carbothermic reduction of silica in a submerged arc furnace above 2000 °C, using coke, steel scrap, and quartz. Common grades FeSi 45, 65, 75 carry 45–80% Si and serve as steel deoxidizers, cast-iron inoculants, and Mg-reduction reductants. About 3–5 kg of FeSi75 is co
Vanadium smart manufacturing in mid-2026 is anchored by three real signals: a Luverne, Minnesota turnkey robotic integrator (Backdraft, est. Luverne MN), a global vendor stack from Rockwell Automation (PlantPAx, FactoryTalk), and the established China-Europe track record on AI/cloud/NEV automation.
Molybdenum manufacturing spans powder metallurgy for rods, sheets and tubes, additive manufacturing for complex near-net shapes, and warm flow forming for defence-grade liners. Process route selection hinges on purity (99.95% Mo), density target, operating temperature, and finished-form geometry, wi

Tungsten and tungsten-carbide manufacturing in mid-2026 spans powder metallurgy, FAST field-assisted sintering, and precision grinding, with ISO 9001:2015 carbide shops holding ±0.0001 in OD on centerless lines and FAST densification emerging for fusion first-wall mock-ups.
Zinc ingot smart manufacturing pairs continuous-casting and induction melting lines with IIoT sensors, machine-vision quality gates, and energy dashboards, lifting OEE by roughly 6 percent in documented Industry 4.0 retrofits. Selection gates focus on molten-metal thermocouple coverage, fume-ex

Copper cathode smart manufacturing pairs ISA-95/ISO smart-manufacturing frameworks with electrorefining process control, with ISO's 2021 Smart Manufacturing white paper providing the coordination roadmap that cathode producers and OEM/ODM cathode-anode factories are now aligning against.

Aluminum ingot smart manufacturing in 2026 ties molten-metal casting to AI vision, automated billet handling, and digital twin process control; key selection criteria are alloy family, traceability, and OPC UA / MQTT data interfaces for downstream extrusion and rolling lines.

Aluminum ingot manufacturing moves from batched raw inputs through smelting, degassing and deep-well casting into round billets, with downstream extrusion and anodizing defining the alloy's final mechanical and surface spec envelope.

Stainless steel coil smart manufacturing in mid-2026 centres on integrating cold-rolling mills, slitting lines and surface-finish cells under MES/IIoT control, with 304/316/2B stock kept by TianJin Teda Ganghua and Bozhong feeding Asian, European and North American OEM chains.

Stainless steel coil production flows through five canonical stages — melting/casting, hot rolling, cold rolling, annealing and pickling, plus finishing — with 304/316 austenitic and 201/430 ferritic grades dominating the China-export channel that lists widths from 0.3 mm to 1.0 mm and surfaces 2B,

Fluoropolymer smart manufacturing pairs PTFE/PFA/FEP processing with IoT, AI vision and MES layers to control sintering temperature bands of 360-380°C, cut scrap and meet FDA/USP Class VI traceability.
Fluoropolymer manufacturing in mid-2026 centres on aqueous emulsion/suspension polymerisation of tetrafluoroethylene and copolymer feeds, followed by melt-processing into PFA, FEP, PVDF, ETFE and PCTFE parts. Injection moulding, stretch blow moulding, fusion welding and CNC machining form the four w

Silicone rubber manufacturing splits into two industrial families — high-consistency (HTV/HCR) and liquid (LSR/LIMS) — each with distinct cure chemistries, moulding routes, and tolerance windows shaping buyer spec gates.

ABS (Acrylonitrile Butadiene Styrene) is a 1.05 g/cm³, 0.4-0.7% shrink thermoplastic with a polybutadiene-dispersed-in-SAN sea-island morphology, processed chiefly by injection moulding and extrusion across appliances, construction, automotive and helmet lines.

Polypropylene (PP) smart manufacturing is pivoting to MES-controlled batch lines, additive manufacturing parameter optimisation and FDM/SLS process standardisation, with a Thailand resin market projected to reach USD 2 billion by 2030 at a 2% CAGR.

Polyethylene resin plants are pairing in-line rheometry, FT-NIR melt-index sensors and machine-vision bubble/stack gauging on the extrusion line, cutting grade-change scrap by documented double-digit percentages in 2026 retrofits.
Polyethylene (PE) resin is the most-produced thermoplastic, made by polymerising ethylene monomer — LDPE via free-radical high-pressure routes, HDPE/LLDPE via low-pressure catalytic routes — then pelletised with additives for downstream conversion.

Chinese PVC resin processors are deploying MES-linked SCADA, inline viscosity sensing and robotic palletizing across S-PVC and rigid compound lines, with OEM/ODM plants in Zhejiang, Anhui and Guangdong now offering ISO 9001-certified smart-production runs for cable sleeve, profile and coving grades.

Epoxy resin manufacture pairs a bisphenol A + epichlorohydrin condensation with a catalyst or hardener cure, typically at 3:1–10:1 resin:hardener ratios and catalyst loadings under 1 wt%, producing a step-growth, void-free thermoset. Cure may be room-temp, elevated, or UV-initiated.

Aramid fiber smart manufacturing in mid-2026 pairs wet-spun/ dry-jet para-aramid lines with closed-loop quality, machine-vision inspection, and end-to-end MES visibility, and Suzhou Nuomis is shipping Kevlar-class filament yarn at FOB US$19–20.3/kg with a 30 kg MOQ as of 30 June 2026.

Aramid fiber manufacturing converts aromatic polyamides — with ≥85% of amide bonds bonded to two aromatic rings — into high-modulus filaments via polymerization, spinning, drawing and heat treatment, yielding grades like Kevlar-29 (2.9 GPa tensile, 72 GPa modulus) and Kevlar-49 (2.8 GPa, 130 GPa).
Continuous filament glass fiber is made by direct-melt drawing molten silicate glass through multi-hole bushings at 14–24 μm diameter, then sized, gathered, and converted into rovings, mats, and fabrics for FRP composites.
Carbon fiber smart manufacturing in mid-2026 pairs six-axis robotics, vision-guided creels, LT/HT/3000 °C furnaces, AS9100:D composites lines and FDM of recycled carbon fiber to cut scrap and compress cycle time on aerospace, medical and EV-tier parts.
PAN-based carbon fiber dominates aerospace-grade production, manufactured through precursor spinning, oxidative stabilization at 200-300°C, low- and high-temperature carbonization up to ~1500°C, and surface sizing. Process selection between prepreg-autoclave, resin infusion, and short-fiber compress

Magnesium ingot producers in China are layering MES, robotics and SF6-free cover-gas control into electrolytic and semi-continuous casting lines, while global OEMs report only 23% full MES integration despite 93% adoption.
Titanium sponge is produced industrially only by the Kroll magnesiothermic route: TiCl4 feed is reduced by liquid magnesium near 900 °C under argon, followed by vacuum distillation to separate residual Mg and MgCl2. Process optimization of TiCl4 feed rate, distillation temperature, system pressure a

Phosphate-rock smart manufacturing now pairs cloud MES (e.g. Plex 99.5% uptime SLA) and AI-driven batch control (Polaris Chordata Batch) with phosphate-specific unit operations — flotation, calcination, granulation — to lift P2O5 recovery and cut energy per ton.
Phosphate rock is mined, beneficiated to +30% P2O5 concentrate, then acidulated with sulfuric acid to make wet-process phosphoric acid; 90% of US output feeds SSP/DAP/MAP fertilizer chains via the single-superphosphate, triple-superphosphate and ammonium-phosphate routes.

Manganese ore processing plants in 2026 are adopting MES-anchored smart manufacturing stacks — IIoT ore-grade analyzers, ISA-95 batch logic, and AI-driven dense-media separation control — to lift Mn recovery, cut energy, and harden traceability for battery and steel-grade output.
Manganese ore is a continuous-process raw material whose downstream value (lumps, MnO2 powder, battery-grade EMD) is set by Fe/Mn ratio, sizing and impurity limits; primary flowsheet stays crushing → washing → jigging → roasting, with EMD taking an electrolytic branch.

Cobalt sulfate smart manufacturing now centers on digital twin process control, AI-driven crystallizer optimization and ISA-95/SCADA integration across the battery-grade CoSO4·7H2O line, with APAC producers leading the installed base.

Cobalt sulfate heptahydrate (CoSO4·7H2O, CAS 10026-24-1, MW 281.10) is the battery-grade cobalt salt most often made by reacting cobalt(II) oxide with dilute sulfuric acid, followed by purification, evaporation and cooling crystallization; alternate routes start from cobalt metal, cobalt hydroxide o
Nickel sulfate smart manufacturing ties crystallizer pH/redox control, DCS-SCADA integration and S95 batch ISA-88 architecture to battery-grade NiSO4·6H2O output above 22% Ni, with cobalt below 0.05% and Cu below 5 ppm, driven by China-EU automation transfers seen 2024-2026.
Battery-grade nickel sulfate hexahydrate (NiSO4·6H2O, CAS 10101-97-0) is industrially produced by hydrometallurgical leaching of nickel matte or sulfide concentrates, followed by impurity removal and crystallization, with a minimum 22.0% Ni content and strict Co, Cu, Fe, Zn limits per 2025 hydrometa

Battery-grade lithium hydroxide (LiOH·H2O, CAS 1310-66-3; anhydrous LiOH, CAS 1310-65-2) is moving from batch-precipitation lines to integrated smart plants, with Industry 4.0 sensors, model-predictive crystalliser control and battery-customer traceability now driving build-out decisions in 2026.

Battery-grade lithium hydroxide monohydrate (LiOH·H2O, CAS 1310-66-3, MW 41.96) is produced commercially via two routes: lithium carbonate causticisation with lime, and direct lithium sulphate electrolysis/bipolar-membrane conversion, with salt-lake brine electrodialysis now scaling to 20,000 t/y pl
Lithium carbonate (Li₂CO₃, CAS 554-13-2) is industrially refined from spodumene hard rock or continental brines, with battery-grade specs now demanding ≥99.5% Li₂CO₃ and SO₄²⁻ below 800 ppm; Metso launched a single-pass spodumene-to-Li₂CO₃ process on 2026-05 to cut sodium-sulfate by-product load [S4

Chinese UHP graphite electrode plants reached 15,883 yuan/ton average market price in October 2025, while smart-factory retrofits target energy-per-ton reduction in baking and graphitization furnaces.

Polysilicon manufacture spans four industrial routes — Siemens-process trichlorosilane (TCS) chemical vapor deposition, fluidized-bed reactor (FBR) silane, upgraded metallurgical-grade (UMG) silicon, and emerging silicon-micromotor MEMS deposition — with solar-grade output dominated by Siemens TCS r

Industrial laser manufacturing covers welding, cutting, additive manufacturing (L-PBF, L-DED), and micro-processing, with laser sources chosen by wavelength, power density, and material absorption. Selection hinges on workpiece thickness, thermal conductivity, and required melt-pool size for the tar

Welding-robot smart manufacturing in 2026 is dominated by Chinese system integrators offering 6-axis articulated cells from US$3,400 to US$23,000 per unit, with collaborative robotics and Industry 5.0 human-skill modeling reshaping the buyer shortlist.
Welding robot manufacturing ties articulated 6-axis arms to CMT/MIG or pulsed-GMAW torches, IoT multi-agent sensing stacks, and automatic multi-goal path planning. Cold Metal Transfer is the dominant low-heat process for thin-gauge aluminum and dissimilar joints in body-in-white and structural fabri
Industrial laser cutting machines are built from seven sub-systems — laser source, beam delivery, CNC motion, cutting head, worktable, gas and cooling utilities, and fume extraction — and the source choice (fiber vs CO2) dictates 90% of the downstream architecture and the materials the machine can c
CNC controllers are now the command hub fusing motion, servo, robot and machine vision into one smart-manufacturing cell, with retrofit and COBOT integration the fastest 2026 deployment paths.

A CNC controller (Machine Control Unit) is the digital subsystem that reads G-code/M-code, drives spindle and feed motors through closed-loop amplifiers, and is built as either a PC-based or PLC-based architecture. Mainstream commercial stacks — FANUC 30i/31i/32i/35i-B, Siemens Sinumerik, Mitsubishi

An industrial gearbox on a smart-factory line now pairs a servo motor, an absolute encoder, and an IIoT gateway that streams vibration RMS, oil temperature, and torque to a SCADA node over OPC UA, with condition-monitoring data feeding a digital twin for predictive maintenance. WIA-PA remains the do
An industrial gearbox is built through six linked stages — forging or casting the blank, rough and finish machining of gears and housings, hobbing or grinding the teeth, heat treatment, precision assembly, and final no-load and loaded testing — governed by AGMA quality grades (4–15) and DIN 3962 cla

Ball screws in 2026 are being specified as precision-class IT 1/IT 3/IT 5 components paired with servo drives, thermal compensation, and integrated position feedback; smart manufacturing deployments centre on micron-class linear modules and 0.1 µm encoder-resolved stages.

Ball screw manufacturing spans thread rolling for commercial grades and thread grinding for precision classes, with nut assembly, ball-loading and preload setting controlling final accuracy and life.

Linear guide rails built into gantry stages, cross-roller MONORAIL profile guideways, and aluminum/ball-bearing light rails form the spine of 2026 smart-manufacturing cells, with rail spans from 100 mm to 3,000 mm and ISO 9001:2008 / HRC58-62 quality gates.
RV reducers anchor industrial robot joints and demand sub-arc-minute backlash, pushing Chinese suppliers like Wuhan Jinghua and Hengfengtai to layer ISO 9001/14001/OHSAS 18001-certified smart lines onto cycloidal gear production as Rockwell Automation and SME report digital transformation is now a m

RV reducer manufacturing centers on cycloidal-pin meshing with ±2 m/s² vibration acceptance, gear-grinding and heat-treatment discipline, and a five-stage assembly flow ending in time-domain factory qualification.
Harmonic reducers (50:1–160:1 ratios) anchor smart-manufacturing robotics joints, with Chinese vendors like Picea Motion, Harmontronics (SH:688022) and Haitian Smart Solutions driving 2026 integration of strain-wave gears, vision, and IoT.

Harmonic reducers (strain-wave gears) are built around three core parts — wave generator, flexspline, circular spline — and the manufacturing flow hinges on thin-wall flexspline forming, heat treatment, and precision tooth profile control. Commercial units deliver 50–160:1 ratios, ≤3–5 arc-min backl
A modern industrial servo drive is built from a defined bill of materials (IGBT power stack, MCU/DSP control board, EMC filter, encoder feedback interface) on a staged surface-mount line, with safety functions defined by IEC 61800-5-2 and STO as the entry-level requirement.

Warehouse robotics in mid-2026 is dominated by AMR fleets, modular robotic cells, and edge-AI orchestration, with vendors reporting 99.99% pick accuracy, 2-4x throughput gains, and full WMS/WES integration across brownfield and greenfield sites.

Collaborative robots (cobots) now anchor flexible smart-manufacturing cells, with deployments spanning automotive, 3C electronics, semiconductors, and SMT lines, governed by ISO 10218-series and ISO/TS 15066 safety thresholds and an emerging human-centered design discipline.
Collaborative robot (cobot) manufacturing covers articulated 6-axis and 7-axis arms, joint torque sensors, ISO 10218-1/ISO TS 15066 safety-rated controllers, and shared-workspace assembly cells deployed in coexistence, cooperation, and collaboration modes across automotive, electronics, and small-ba
2D LiDAR sensors now cover 0.1–40 m at 1–10,000 Hz for under 2 W, while 3D units reach 350 m with 128 channels at 10.4 M points/s; the 2026 LiDAR stack pairs TOF ranging, native-color silicon fusion, and ASIL-B/SIL-2 functional safety for AGV, AMR and smart-factory deployment.

Machine vision systems pair 2D/3D cameras, industrial PCs and SCADA/AR software stacks to drive smart-manufacturing cells, with documented gains such as a 6% OEE lift on a snack-factory line and a six-month, 64-module AR/VR workforce program at a national fertilizer plant (2026-07-10).

Precision air conditioning for smart manufacturing requires ±0.1°C temperature and ±2% RH stability, driving integration of cleanroom-grade air controllers, ISO 9001/AS 9100 shops, and six-million-unit air-conditioner plants.

Precision air conditioning (PAC) units for data centers and labs are manufactured to ±0.5°C temperature and ±3.0% RH control, using inverter compressors, EC fans and 10-year design lives. Build flow follows five process bands.
An industrial-grade double-conversion UPS is the standard power-protection block for smart-manufacturing cells: a 1U online lithium unit rated for DIN-rail or panel mounting, LiFePO₄ cells, and 15-year service life, sized to ride out the gap between mains failure and generator take-over while PLCs,
An industrial UPS is a power-electronics assembly combining a rectifier, battery bank, inverter and static bypass, manufactured under ISO 9001 and ISO 14001 frameworks, with kVA-rated models spanning 5–20 kVA single/three-phase for control, signal and protection loads.
Immersion cooling is scaling into smart manufacturing: the global market is projected to reach USD 2.61 B by 2032 at a 24.2% CAGR, with single-phase tanks, synthetic dielectric fluids, and 80 Plus Titanium CRPS PSUs now specified alongside PLC-driven fluid loops.

Single-phase immersion cooling dominates 2026 IT deployments using dielectric fluorocarbons or hydrocarbons in a sealed tank with a pumped coolant-to-water heat exchanger loop; two-phase boiling with Novec 649-type fluids remains a DoD and HPC niche because of IT-equipment reliability risk.

Liquid cooling in 2026 H1 is being reshaped by AI-server cold plates, digital-twin moulding lines, and additive coolers, with multi-source factories scaling vacuum-brazed plate production for hyperscale data centers.

Data center cooling automation in mid-2026 is converging on closed-loop chilled/condenser water control, two-loop thermal modelling and shop-floor data platforms that bridge IT loads with plant-floor assets.
Data center cooling manufacturing in 2026 pivots on liquid-loop CDU skids (100 kW class, ASHRAE W17–W45 secondary), rack-scale immersion, and hybrid rear-door / in-row units. AI and HPC workloads have pushed Wiwynn–Showa Denko to co-validate full-stack server liquid cooling for hyperscale cloud buye

Agentic and visual-AI platforms are landing on the shop floor as embedded quality, predictive-maintenance and line-expert systems, targeting >99.99% inspection accuracy, 2x OEE and 75% downtime reduction, with industrial PC, smart-camera and smart-meter lines acting as the closest reference architec
An AI server is built through a six-level EMS assembly chain ending in a Level 6 motherboard integration stage, with AI-specific hardware complexity (multi-GPU, NVLink, liquid-cooled backplanes) adding integration and test depth versus general-purpose servers. Taiwan EMS firms — Quanta, Wistron
NAND flash fabs are rebuilding around 300 mm wafer lines, 3D TLC/QLC stacking past 200 layers, and AI-driven OPC/etch control; reference platform prices for industrial 8GB eMMC 5.1 sit at US$8.99-14.9/piece on Shenzhen trading-channel listings published 2026-01-06.
NAND flash is built on a Block→Page hierarchy where Page is the program/read unit (typically 2 KB + 64 B spare or 512 B + 16 B spare) and Block is the erase unit, with factory-marked bad blocks managed at the spare-area level from day one.
DRAM smart-factory builds in 2026 converge on lot-level MES, in-line e-test SPC and AMR handoff between back-end test and JEDEC tray pack. Stack-to-pack automation raises throughput and trims human-handling ESD events, with supplier directories in Anhui, Guangdong and Beijing dominating OEM/ODM DRAM

DRAM cell fabrication runs a 6+ step front-end flow: STI active-area definition, buried wordline, bitline/contact, storage node contact, capacitor mesh etch and plate formation, each held to sub-10 nm CD control. HBM stacks built on this DRAM base feed AI accelerator bandwidth, while TEM/EDS metrolo

HBM (High Bandwidth Memory) is the gating component for AI accelerators in 2026, with global market projected at $54.6–58B and 50–60% supply gap; smart-manufacturing automation now pivots around TSV stacking, CoWoS advanced packaging, and MR-MUF thermal control.

Smart packaging lines now pair robotic end-of-arm tooling with HMI-embedded training and virtual-design digital twins, hitting 1:5 operator-to-machine ratios on a 126.8 ft² footprint, per Aagard and Springer (2026-07-09).
Chip packaging smart manufacturing now leans on closed-loop vision, AOI-spired inspection, and robot-integrated backend lines; 2026 OEM guidance pushes AI vision, EtherNet/IP and digital-twin calibration as the new baseline.

Wafer fab equipment smart manufacturing in mid-2026 is shifting from pilot AI projects to a structured SEMI-backed automation maturity framework, with humanoid pilots now visible on 200mm/300mm lines, while the broader WFE market tracks toward a USD 34.7 B 2024-2029 expansion at 6.2% CAGR.

Lithography equipment smart manufacturing is shifting from isolated tool automation to data-fused fab lines, with the global market tracked at US$ 22.1 Bn in 2022 and projected at 7.2% CAGR through 2031 across mask aligner, projection, laser direct imaging and laser ablation platforms.

Smart electric meter manufacturing pairs SMT PCBA for metrology/MCU with PTH for power/voltage-divider stages, polycarbonate IP-rated casings, ASIC-based metrology chips and DLMS/COSEM or HAN protocol stacks; tier-1 OEM lines run 6-8W total per node with 0.5-2W on the voltage circuit.
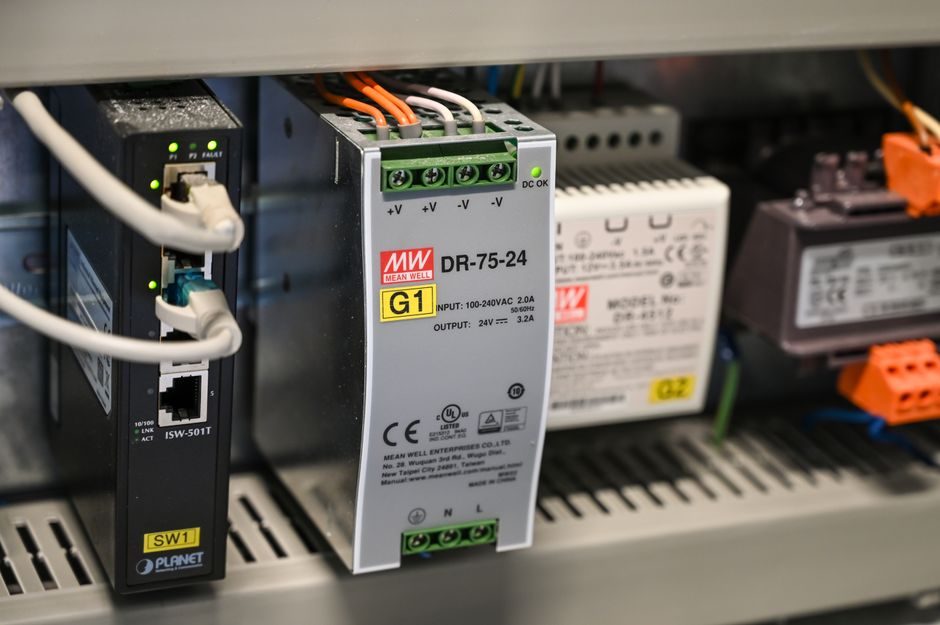
DC fast charger manufacturing now centers on automated power-module assembly, isolated DC-DC converter integration, and OCPP 2.0.1 / ISO 15118 software backbones spanning 30 kW to 5 MW output classes.

A DC fast charger is built around an AC/DC power stage that rectifies three-phase grid power to ≈800 V DC, an isolated high-frequency DC/DC stage that regulates charging current to the EV pack, plus communications and a mechanical enclosure. Real lines pair SiC power modules with automated end-of-li
EV charger OEM/ODM lines in China now ship OCPP 1.6/2.0.1-ready AC and liquid-cooled DC units at scale, with MarketsandMarkets sizing the global EVSE market at USD 38.55B in 2026 toward USD 120.85B by 2033.

E-axle manufacturing consolidates e-motor, SiC inverter and high-speed gearbox into one housing; AISIN's cell-and-line hybrid system runs multiple eAxle variants on one line, while half shafts use 40Cr/42CrMo with quench-and-temper heat treatment.

EV traction motor smart manufacturing is pivoting from pilot cobot cells to integrated lighthouse lines, with the 7th Smart Manufacturing for Automotive Summit in Detroit (10 Sept 2026) drawing 180+ experts and 76% senior decision makers to address AI, digital twins, and 3D printing in motor product
Offshore wind foundation fabrication is shifting toward robotic welding, automated NDT and MES-linked line control as monopile diameters exceed 10 m and jacket nodes grow more complex; Pemamek's PEMA offshore cell covers tower sections, monopiles, transition pieces, jackets and floating foundation w
Offshore wind foundation manufacturing centers on serial fabrication of steel monopiles, jackets, and floating substructures using plates up to 4.3 m wide, 15 m long, 15+ cm thick and 40 t per plate, on coastal parcels needing 8 m+ deep-water berths. Process logic, tolerances and standards diverge s
Wind turbine main-gearbox smart manufacturing centers on 1.5 MW closed-loop test stands, SCADA-driven condition monitoring, and OEM-led intelligent quality lines. Goldwind reports 3,000+ R&D staff, 7,300+ patents, and 2.8 B CNY R&D spend (2024) backing its smart-wind programme.
Wind turbine blade smart manufacturing in 2026 centres on automating the full composite lay-up, resin infusion and trimming chain for blades now exceeding 100 m, with Goldwind scaling intelligent turbine production in China and MATLAB/Simulink BEM optimisation tools lifting modelled power from 4.3 M

Wind turbine blades are large hollow composite shells, 40-126 m, produced in matched male-female molds via resin infusion of glass/carbon fabrics and epoxy/vinyl-ester, with FMCW radar and focus-SVDD AI used to catch cure defects before demold.
Grid-scale battery storage capacity may need a 35× uplift to nearly 1 TWh by 2030, pushing cell, module and BESS line builders toward AI-driven MES, inline machine vision and digital-twin commissioning. Five vendor moves from Jul 2026 show where the automation stack is consolidating.

Grid-scale battery storage manufacturing lines in 2026 centre on LFP prismatic or VDA-format Li-ion cells stacked into 1–6 MWh DC containerised blocks, with dry-room dewpoints at ≤−40 °C, formation cycling in the 0.05–0.5 C band, and PCS tied to 1500 V DC bus architectures. Cycle life targeting is 6

TOPCon (Tunnel Oxide Passivated Contact) cells layer a 1–2 nm tunnel oxide and doped polysilicon film on the rear of an n-type c-Si wafer, and the 2023-11 to 2025-08 Xi'an outdoor test on 9 TOPCon, 4 BC and 4 HJT modules records first-year TOPCon degradation between 0.52% and 1.48%, versus 2.27%–2.3
Solar glass is a low-iron, high-transmission soda-lime flat glass (≈83.7% AM1.5 baseline) made by float or patterned-rolling lines, then tempered to 120 MPa and AR-coated for PV modules, thin-film substrates, and BIPV laminates.

Crystalline-silicon cell smart manufacturing has shifted from inspection-only to closed-loop diagnose-and-repair, with EL imaging + Gabor/PCA/Random-Forest pipelines hitting above 90% accuracy on crack and area-defect classification and a follow-on laser isolation/cut station. Tier-1 module makers h

Crystalline silicon IBC cells hit 21.3% efficiency with rear-side emitter architecture, while bulk-heterojunction polymer cells cross 5% PCE and aim above 10% via solution roll-to-roll processing; new bath-salt-based absorbers cut manufacturing environmental load.
A solar inverter manufacturing line in 2026 typically runs SMT PCB assembly, power-stage integration (IGBT or full-SiC modules), enclosure potting, firmware flashing, and full-load burn-in aging tests, with residential units shipping in the 1–24 kW band and C&I PCS reaching 125–500 kW.

Electrolyzer smart manufacturing converges PEM/AEM/SOEC stack assembly, ±0.1 mm bipolar-plate placement, and ISA-95 MES-SCADA stacks; LEAD Intelligent's 1 s/pcs at ±0.1 mm fuel-cell cycle sets the benchmark hydrogen stack lines now copy for electrolyzer production (2026-07-11).
Green hydrogen smart manufacturing in mid-2026 is anchored by PEM electrolyser stack automation, with Hystar targeting 150% higher output per unit energy, OEM line builders like Comau and Semcon delivering fuel-cell-style mass-production cells, and digital twins (MATLAB/Simulink) modelling solar+BES
Green hydrogen is produced by water electrolysis powered exclusively by renewable electricity — wind, solar, hydro, or nuclear — yielding H2 with near-zero operational CO2. Industrial-scale output runs through alkaline, PEM, or solid-oxide electrolyzer stacks, each with distinct temperature, catalys
Fuel cell stack smart manufacturing now automates MEA, bipolar-plate, and stack-up stages with vision-guided torque, leak testing, and EV-rated clamping of 8–14 N·m; integration gap remains between cell assembly and end-of-line HIL test.
A PEM fuel cell stack is built from a repeating MEA/bipolar-plate unit where membrane hydration, ~80°C isothermal operation, and sub-model coupling (voltage, anode/cathode flow, hydration) define the assembly and test envelope; FEV operates five 200 kW benches across -40°C to +120°C, 10-98% RH[
Simscape Battery BMS blocks (state estimators, balancers, protection, cyclers) are now production-ready for real-time HIL on Speedgoat and dSPACE SCALEXIO targets at 50 µs step size, anchoring 2026 cell-to-pack automation workflows.

Lithium-ion electrolyte manufacturing sits between electrode coating and dry-room cell assembly, with water content specified below 20 ppm for high-nickel Li-ion cells; the process chain covers LiPF6 salt synthesis, solvent mixing (EC/EMC/DMC), additive dosing (VC, FEC), and inline moisture/acid tit
Battery-separator smart-manufacturing programs in 2026 are converging on inline thickness/gurley vision, AI vision inspection, and full MES traceability, with Rockwell's 11th annual State of Smart Manufacturing report flagging the segment as a top investment pocket for digital strategies.

Lithium-ion battery separators are thin porous polyolefin membranes (PE/PP) made by wet or dry extrusion, with 10-25 °C sub-melt annealing and biaxial stretching, then ceramic-coated for thermal stability.

SOFC anode manufacturing hinges on Ni-YSZ cermet powder routes—Ni must exceed ~40 vol% for 100 S/cm conductivity yet stay under 60 vol% to control TEC mismatch, with porosity and TPB stability set by sintering atmosphere and temperature profile.

Cathode active material (CAM) accounts for roughly 35% of total lithium-ion battery cost, and the dominant commercial route remains carbonate co-precipitation followed by high-temperature sintering; flame-spray pyrolysis (FSP) and dry mechanofusion coating are the two most credible alternative route

Solid-state battery smart manufacturing hinges on dry-electrode calendering, sulfide/oxide electrolyte handling, and AI-driven stacking lines; 2026 marks pilot-scale rollout, with energy density targets of 400-500 Wh/kg and costs still 4x liquid Li-ion.
Battery cell manufacturing in 2026 is a four-stage flow (electrode, cell assembly, formation, aging) governed by AI analytics stacks that cut data wrangling 80%, accelerate yield learning 50%, and reduce quality excursions 50% per Exensio Battery.
Nickel-product sourcing in 2026 splits into OEM (buyer-owned design, factory builds) and ODM (factory-proprietary design, buyer rebrands), with cupronickel coil and nickel mesh suppliers in Guangdong, Fujian and Henan offering both paths.

Rotary-kiln electric-furnace (RKEF) lines remain the dominant nickel-pyrometallurgy topology, with installed capacities near 28,000–56,000 t Ni/yr per 2–4 furnace train, while HPAL circuits target 67,000 t Ni/yr MHP intermediate.

Nickel value-chain firms face a 12–18 month Industry 4.0 maturity gap driven by IoT capex, scarce skilled labour and SME financing friction; 2024 Springer analysis frames a systems-theory route to close it.
Nickel-sulphate and nickel-cathode capacity is being added in 12-36 month waves tied to ternary cathode demand, with planning done via RRP, RCCP and CRP work-center methods inherited from JD Edwards EnterpriseOne.

Sodium-ion cells ride the same coating, drying, calendaring and formation line as Li-ion, with hard-carbon anode and Prussian-blue/oxide cathode as the dominant chemistry pair on pilot lines in 2026.
OEM cobalt-alloy production in 2026 hinges on drawing-to-shipment scope, ISO 9001/ISO 14001/ISO 45001 system stacks, and STP-grade chemistry, while pure ODM cobalt work is thin outside electronic-chemicals and consumer-formulation lines.
Battery pack smart manufacturing in mid-2026 is consolidating around ISO 9001/13485-certified cell-to-pack lines with CE-marked laser/spot welding, integrated PCM testers up to 100 V/120 A, and Simscape Battery virtual commissioning, as suppliers such as WinAck, Gushine, and Bosch Rexroth push modul

Automotive battery pack manufacturing combines cell-to-module series-parallel assembly, BMS integration, polymer/structural shell production, and end-of-line testing; cell form factors (pouch, can, compact/regular cylindrical) drive module topology, while manufacturing tolerances on cell Ahr rating

Jinchuan Group's 5,000-metric-ton cobalt line expansion entered Phase 2 trial production in June 2022, lifting the group's annual cobalt capacity to 18,000 t/y with 100% raw-material self-sufficiency for ternary precursors — a benchmark data point for any cobalt capacity-planning model in the lithiu

Lithium battery OEM and ODM are the two dominant sourcing models for branded energy-storage buyers in 2026: OEM builds to the buyer's drawings under UL/CE/UN38.3, while ODM delivers a factory-owned reference design that the buyer rebrands, cutting R&D time and tooling cost.
Battery-grade lithium chemical cost is dominated by cathode-active material and upstream brine/ore conversion, with lithium hydroxide and carbonate typically representing 30-50% of cell material cost in current NMC/LFP packs; refining steps, not raw resource extraction, drive the largest single shar

Industry 4.0 adoption in lithium processing now centres on IIoT, cloud analytics and AI-driven defect detection, with IBM Institute for Business Value data showing up to 50% defect-detection and 20% yield improvements in smart manufacturing deployments.

Lithium battery manufacturing quality in 2026 hinges on a tightly bounded QMS stack: ISO 9001 plus IATF 16949 for automotive cell suppliers, mandatory testing on every cell including helium leak, burst and pressure-cycle fixtures, and chemistry-specific cycle-life bands such as 4,000-cycle LiFePO4 f
Jiangsu Azure's 700-million-cell annual capacity and Chuneng New Energy's 150 GWh Yichang park anchor China's 2026 lithium production scaling, with lithium hydroxide output tracked monthly by CBCIE for downstream planning.

Lithium-ion cell production requires a defined chain of mixing, coating, calendaring, slitting, stacking/winding, electrolyte filling, formation and aging equipment; China's domestic equipment market grew ~31% YoY in 2014 to roughly RMB 3.8 billion, anchored by EV demand.
Robotics OEM vs ODM manufacturing: OEM builds to buyer spec, ODM ships a ready platform the buyer rebrands. For robotics, the split governs IP, NRE cost, lead time and PLC/vision integration depth.
CPU OEM and ODM differ by who owns the design: OEM builds the buyer's spec, ODM ships the factory's own design. In 2026 China-ODM/EMS hubs in Tianjin and Guangdong dominate PLC-CPU and 5G-CPU outsourcing.

CPU manufacturing quality is governed by a stack of OEM, ISO and JEDEC standards, with AMD-Xilinx, Intel and ODM suppliers aligning wafer, assembly and test processes to ISO 9001:2015 and a 180-day quality data load cycle.

GPU OEM vs ODM manufacturing splits along ownership of design and binning: OEMs license a brand SKU, ODMs absorb full board design. The RTX 3050 OEM SKU shipped 2,304 CUDA cores cut from GA106, vs 2,560 on the DIY card, illustrating the same-die, different-bin pattern repeated across every NVIDIA OE

GPU production line design links NVIDIA architecture milestones (Volta 2017 → Ampere 2020) to factory-side wafer, packaging and test tooling choices, while Positech's Production Line DLC at US$4.99 (released 2019-10-23) models the same slot-utilisation logic in software. Wuxi-based MetaX, founded 20
GPU bill-of-process cost decomposes into wafer fabrication, advanced packaging, and test/QA — with mask sets, HBM stacking, and CoWoS yield driving the variance. NVIDIA's AD102 die uses TSMC 4N process, anchoring fab cost baseline.

Industry 4.0 adoption in 2026 hinges on four pillars — cyber-physical systems, IoT, AI/ML-driven process control, and digital twins — with quantified AI/ML case studies now published for high-variance foundries. Foundry and discrete-assembly lines lead deployment, while brownfield PLC and sensor int
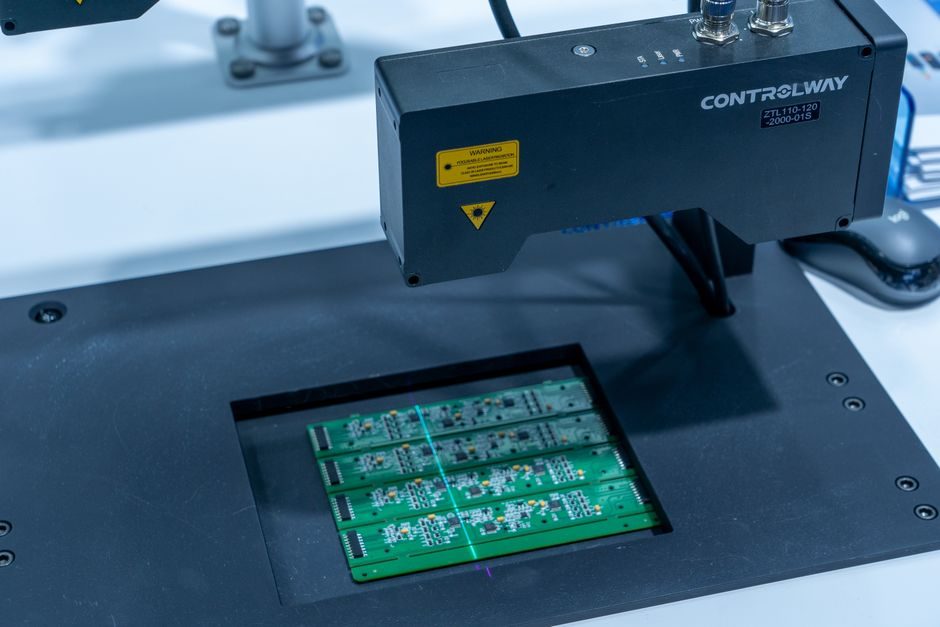
GPU manufacturing quality rests on a fabless-brand split: AMD/Xilinx and Nvidia source silicon from TSMC (and historically UMC), then add quality differentiation through board-bin selection, PCB design, VRM components and cooler sourcing. AMD's published Supplier Quality framework targets zero excur

GPU production capacity planning now spans MRP-linked RRP/RCCP/CRP flow control and discrete-event GPU scheduler test hardening; a 2026-06-26 Oracle E1 reference and a 2022-11 Bacalhau PR both expose the gap between shop-floor logic and accelerator-aware jobs.
Photovoltaic production spans crystalline-silicon ingot growth, CIGS and perovskite thin-film deposition, cell finishing, and module lamination, with break-even module economics near $3.2/Wp for building-integrated systems and rising toward $4.5/Wp under weaker insolation conditions.
Centrifugal, positive-displacement and submersible pumps share a common manufacturing backbone: ISO 9001:2015 quality systems, investment-cast or CNC-machined stainless and duplex casings, dynamic balancing to G6.3, and hydrostatic test beds rated 1.5× design pressure.
Modern GPUs are fabricated on 5 nm to 3 nm FinFET process nodes at TSMC, integrate 24 GB to 80 GB of HBM2e/HBM3 stack memory on a 2.5-D silicon interposer, and pair 100+ streaming multiprocessors per die with up to ~1 TB/s NVLink host bandwidth for AI training workloads.
Offshore wind production rests on three mechanical systems — the rotor/nacelle, the support structure (monopile, jacket, or floating platform), and the subsea cable network — all tied together by SCADA over fibre. Floating designs unlock sites beyond 60 m water depth; fixed-bottom remains the LCOE l
Connector production combines precision stamping, plating, injection molding and automated assembly, with low-frequency, PCB and RF families requiring distinct contact systems, dielectric materials and tolerance bands per the《电连接器选用手册》framework.

Industrial valve production covers casting/forging, CNC machining, assembly and pressure testing across gate, globe, ball, butterfly, check and solenoid types, with rupture-pin and self-aligning designs serving safety shutoff roles.
An industrial air compressor is a motor-driven machine that converts electrical or diesel energy into compressed air via positive-displacement (screw, piston, vane) or dynamic (centrifugal) compression, with oil-injected screw and VSD technology dominating the 7–250 kW factory-air segment in 2026.
Reverse osmosis (RO) and multi-stage flash (MSF) account for the bulk of installed desalination capacity; emerging routes — hydrate-based, electrodialysis, capacitive deionization, solar-driven evaporation — sit below 1% combined commercial share. This piece compares process boundaries, energy use a
LED production runs two separate manufacturing tracks — epitaxial wafer growth (GaN-on-sapphire, GaN-on-SiC, GaN-on-Si) and chip-level packaging — with die size, substrate choice and driver topology driving cost, lumen output and lifetime.
A modern utility-scale wind turbine is a 3-blade horizontal-axis machine, with the 2026 offshore class topping 8 MW and rotors over 236 m; production lines focus on blades, nacelle assembly, gearbox QC and tower manufacture.
Cable and wire production breaks into four process families — wire drawing, stranding, insulation extrusion and cable assembly — each with distinct equipment, standards and tolerance gates. Output runs from 0.05 mm ultrafine wire rod up to HV/EHV power cable, with UL, CSA, VDE, HAR and CE conformity
Mining equipment production technology in 2026 spans CNC-machined mill liners, ISO 9001:2008-grade wear parts, automated decline drills, and ATEX/IECEx-rated underground electronics, with EPCM turnkey supply now standard for complex ore bodies.
CPU smart manufacturing in 2026 means using industrial-grade compute, real-time deterministic controls, IIoT sensor layers, and AI-based optimization to turn a wafer-fab or PCB assembly line into a self-tuning system; the spec gates now sit at edge AI inference latency, OPC UA over TSN, and ISA-95/M

SEMI's Smart Manufacturing initiative, IEEE Spectrum's 2026 Imec roadmap coverage, and METTLER TOLEDO's "first-time-right" weighing webinar together signal that AI/IoT, GEM300 connectivity, and brownfield automation maturity are the three live levers in fab automation as of June 2026.
PCB smart manufacturing in 2026 centers on fully integrated SMT lines with AOI + flying-probe test, closed-loop MES/ERP data exchange, and IPC-A-610 Class 2/3 assembly. As of June 2026, EMS providers operate 18-year-tenured one-stop PCB+PCBA workflows (LST, 2008-2026) under ISO 9001:2015 quality sys
Aerospace production in 2026 spans design-to-test pipelines covering aircraft, rotorcraft, and space systems, with the field's flagship journal Aerospace Science and Technology (Elsevier, ISSN 1270-9638) reporting a 2024-2025 Impact Factor of 5.8 and CiteScore 10.30 in Q1 aerospace engineering.
Industrial pump manufacturing in 2026 is a multi-stage process chain: foundry casting or forging of the casing and impeller, CNC machining to ISO 9906 hydraulic tolerances, rotor balancing to ISO 1940 G2.5, and witnessed hydrostatic testing at 1.5× design pressure before API 610 / ISO 5199 shipment.
LFP prismatic cells dominate 2026 BESS manufacturing lines, with cell-to-pack lamination and 0.5C–80C charge/discharge envelope defining the spec envelope across Chinese OEM datasheets published within 60 days.
Aluminum smart manufacturing in 2026 ties foundry MES, robotic handling and PROFINET-based cell control into a single stack. CESMII-led programs, Rockwell's smart-manufacturing portfolio and IMTS 2024 (Sep 9-14) demos anchor the spec map. Aluminum extrusion and die-casting lines are the leading adop
Primary aluminum output is concentrated in a handful of countries led by China at 23,300 kt, with Russia, Canada, UAE, India, USA, Australia, Norway, Brazil, Bahrain and Iceland rounding out the top producers. Industrial process flow runs from alumina refining and cryolitic smelting through casting
Industrial robot manufacturing in 2026 centers on a six-axis articulated arm (typically 6 kg to 800 kg payload, 0.02–0.1 mm repeatability) assembled from body, electrical cabinet, and pipeline pack subassemblies, with off-line programming and energy-efficient scheduling now standard practice.
Machine tool production technology spans 3-to-5-axis CNC machining centers, EDM, lathes and drilling units, with spindle speed, repeatability and thermal stability as the headline 2026 spec levers on every quote.

Silicon wafer production runs through ingot growth, wire saw slicing, lapping, double-sided polishing, and wet/dry cleaning, with downstream solar and semiconductor applications demanding tighter surface and defect control in 2026.

Seagate's Smart Manufacturing AI platform, deployed across hard-drive wafer lines, uses machine-vision and time-series models to lift yield and throughput, mirroring smart-factory patterns now spreading to merchant silicon wafer fabs. (148 chars)
Copper cathode, wire-rod and alloy producers are moving from pilot to plant-wide smart-manufacturing stacks in 2026, driven by electrowinning current-efficiency tracking, continuous-cast breakout prediction, and ISA-95/MES integration that links smelter KPIs to ERP.
Crystalline silicon PV modules are made by stringing tabbed cells with a tabber-stringer, bussing strings, layup, EL test, lamination at ~140-160°C, framing and junction-box welding; turnkey lines from Reoo and Ooitech cover 5MW-600MW output.
LNG smart manufacturing in 2026 centres on ISA-95/ISA-88 modular automation, IIoT-gated LNG custody transfer, and cryogenic-compatible flow metering; the build-out hinges on NAMUR NE 107 diagnostics, Ethernet-APL wiring, and APC/soft-sensor gains measured in percent not hype.
Data-center smart manufacturing now fuses AIoT edge gateways, OPC UA over TSN, and additive-manufacturing tooling into a single digital thread, with platforms such as Vossic INDEX and Advantech iFactory deploying line-level process-control data in under one hour per cell as of 2026.
Cable and wire manufacturing is a multi-stage process chain: wire rod drawing, stranding, insulation extrusion, cabling, and jacketing. Selection hinges on conductor material, insulation polymer, shielding, and certifications such as UL/CSA/RoHS/REACH.
Chinese EV-charger OEM/ODM lines now combine SMT, in-line testing, and aging workshops under one roof, while PLC, SCADA, and robotic-welding retrofits hit mid-tier power-converter plants through 2026 Q2.
3D printing covers seven ASTM-recognised process families — Vat Photopolymerisation, Powder Bed Fusion, Material Extrusion, Material Jetting, Binder Jetting, Sheet Lamination, Directed Energy Deposition — with polymer FDM, SLA/DLP, SLS, MJF and metal LPBF dominating industrial share; in-house AM is
Air compressor smart manufacturing in 2026 centres on IIoT-ready rotary screw platforms in the 5.5–400 kW band, with variable speed drive, fixed-speed/direct-drive, and two-stage architectures dominating Chinese OEM output.
Battery energy storage production technology covers four cell-chemistry families (Li-ion/LiFePO4, lead-acid, sodium-based, flow), three mechanical formats (cylindrical, prismatic, pouch), and a power-conversion chain that pairs each battery with a PCS, BMS, transformer and switchgear. Process-engine
Data center production technology in 2026 stacks cooling, power, software-defined orchestration and ISO-grade facility build-out into a single industrial workflow, with liquid cooling, GPU-dense racks and SDDC automation dominating new build specs.
EV battery smart manufacturing stacks PLC/SCADA, ISA-95 MES, dry-room robotics, and AI vision into a single line; key spec gates are coating dry-room dew point below -40 °C, electrode coating tolerance ±1-2 %, cell formation current accuracy ±0.05 %, and inline CT/X-ray defect capture above 99 %.
Industrial robot shipments crossed 540,000 units in 2024 with automotive and electronics as the top adopters; 2026 deployments are pivoting toward AI-vision, 5G-APL, and human-collaborative cells. Spec-driven buyers should weigh payload, reach, repeatability, and integration protocol before committi
Rare earth element (REE) refining is dominated by solvent-extraction separation of oxide mixtures, with the dominant light/heavy split routed through bastnasite and monazite cracked to REO feedstocks. REE permanent-magnet alloys NdFeB and SmCo still anchor magnet demand, and 2026 process development
U.S. zero-emission nuclear power production credit under §45U, the BWRX-300 SMR, and Gen-III/IV reactor classes, U-fuel cycle, and small modular reactor economics.

Semiconductor production technology in 2026 spans wafer fab front-end lithography/etch/deposition, back-end dicing/packaging, and node-scale flows down to sub-3 nm, with EUV, 3D NAND stacking, and SiC/IGBT power devices driving the next spec cycle.
Bearing smart manufacturing in 2026 hinges on in-line vision, AI surface-defect CNNs, and ISA-95/MES-linked ring-forging cells; spec gains are measured in µm-grade roundness, ppm defect rates, and per-shift OEE.
Hydrogen fuel cell production combines membrane-electrode assembly, bipolar-plate machining and stack compression to convert H2 + O2 into electricity with water and heat as the only by-products, a stack architecture now powering everything from Antarctic stations to FCEV drivetrains.
Flat panel display production in mid-2026 is dominated by OLED, with glass-to-plastic flexible substrates and laser-based heterogeneous-material patterning replacing legacy LCD backplanes. Chinese panel makers are scaling OLED capacity for smartphone, automotive and wearable applications, and the sa
Aerospace manufacturing in 2026 spans five-axis titanium machining, autoclave-cured composites, laser additive repair, and friction-stir welding, with Invar 36, Ti-6Al-4V and NiCrBSi powder feeds defining material flow.
Electric motor smart manufacturing in 2026 is shaped by BLDC permanent-magnet platforms, IE3/IE4 efficiency classes, and integrated motor-drive-controller modules; sourcing benchmarks from China show 3 kW BLDC at US$269-378 and 5 kW at US$360-545.
Electric motor manufacturing in 2026 centres on six core process stages — stator/rotor lamination, winding, winding insertion, insulation/vacuum impregnation, rotor assembly, and final testing — with hairpin and BLDC winding lines scaling fastest among Asian OEM integrators.
CNC machining is an automated subtractive process driven by computer-numeric controllers and G-code toolpaths; mainstream shops run 2- to 5-axis milling plus turning, holding ±0.01–0.05 mm on aluminium, steel and engineering plastics for aerospace and industrial buyers.
A modern 3 MW+ horizontal-axis wind turbine contains roughly 8,000 parts, with the multi-megawatt drivetrain (main shaft, gearbox, generator, converter, tower, blades) driving both capex and embodied carbon. Sourcing hinges on gearbox metallurgy, blade composite layup, and tower-plate certification,
Crystalline silicon PV modules ship as a multi-stage chain — wafer texturing, diffusion, ARC, screen-printed metallization, co-firing, cell singulation, tabber-stringer lay-up, EVA/backsheet encapsulation, vacuum lamination at ~150 °C, framing and inline EL+AOI — with TOPCon lines now adding n-type
Aluminum manufacturing spans bauxite refining, smelting, alloying, casting, extrusion/rolling, and finishing, with 2026 turnkey line builders scaling 4,000 m² smart factories and integrated North American extruders shortening lead times.
Siemens NX Additive Manufacturing, Smart Manufacturing Experience 2024 at IMTS, and ML/digital-twin research converge on 2026 shop-floor reality: closed-loop AM tied into MES/IIoT, AI-driven parameter control, and T1-ranked Additive Manufacturing journal backing the science.
Smart manufacturing in mid-2026 centres on AI-driven robotics, IIoT sensor fusion and closed-loop control, with SCARA, delta and 6-axis arms now standard on lines running collaborative, vision-guided and digital-twin workflows.
MEMS-based sensors are now specified as the default sensing layer in IIoT smart manufacturing lines, with STAIM 2026 calling for sensor+automation papers on 2026-06-10 and Chinese smart-manufacturing deployments reaching Europe at scale since 2024.
Goldwind's offshore wind smart-manufacturing playbook combines intelligent quality management and a green supply chain across turbine equipment production, while EU monitoring reviews confirm automated environmental impact controls are now standard on 19 UK and 9 other EU offshore wind farm developm
Machine tool smart manufacturing in 2026 centers on IIoT-connected CNC workcells, China-cluster powertrain automation integrators, and December 2026 Southeast Asia sourcing shows. Spec priorities: closed-loop drives, HSK63/HSK100 tool interfaces, 5-axis pallet pools.
A hydrogen fuel cell is a sealed electrochemical stack that turns H2 + O2 into electricity, water and heat, with manufacturing centered on membrane-electrode assembly, bipolar plate fabrication, and stack assembly. Production volume in 2026 clusters around three build paths: metal plate, graphite/re
LNG is natural gas refrigerated to roughly -162°C, shrinking volume 600:1 for cryogenic tanker transport. Liquefaction capacity is dominated by three licensed processes: ConocoPhillips Optimized Cascade, Air Products AP-X, and Black & Veatch PRICO, each defining train capacity, driver selection, and
Drone production in 2026 hinges on five stacked layers — airframe composites, propulsion, flight-control electronics, payload/sensor integration, and docking/autonomy software — with GDU's P300/S400E and K-series docks exemplifying the modular industrial stack (GDU, 2026-06).
Battery Energy Storage System (BESS) smart manufacturing in 2026 hinges on integrating cell formation, pack assembly and rack integration under MES-driven traceability, with LiFePO4 chemistry dominating grid-scale racks above 3 GWh cumulative vendor capacity. Automation stacks target dry-room e
Heavy mining equipment manufacturing combines structural steel fabrication, mining-class powertrain integration, and controlled assembly of ore-dressing subsystems. Plasma cutting, ISO-aligned QA systems, and OEM rock-drill platforms are the dominant build pillars across 2026 supplier practice.
Electric motor production technology covers rotor and stator winding, lamination stacking, magnet insertion and final assembly. Three-phase AC induction and permanent-magnet synchronous units dominate industrial output, while 45% of global electricity passes through motors in service.
Pneumatic system manufacturing splits four sub-assemblies — actuators, control valves, FRL treatment, and auxiliaries — each passing distinct ISO cleanliness and pressure-cycle gates before final integration. Spec discipline, not marketing, separates a plant-quiet pneumatic line from a warranty-burn
Lithium battery smart manufacturing in 2026 centers on fully automated cell-to-pack lines, AI-driven electrode inspection, and MES/ERP integration; major Chinese integrators (ATW, LEAD) report multi-line orders as North American reshoring accelerates.
Nickel and nickel-alloy production is being pulled into the smart-manufacturing wave that IMTS 2024 and EMQ document: IoT, AI analytics, network sensors, and cloud MES layering on top of the melt shop, hot rolling, and pickling lines that already rely on Inconel 625, Monel 400 and Alloy 825 workhors
Heat pump manufacturing in 2026 spans consumer split units up to industrial 120°C output units, with compressor selection, refrigerant compatibility and brazed-plate heat exchanger welding as the three engineering gates that decide line layout.
Industrial robotics manufacturing now spans 6-axis articulated arms, SCARA, delta and collaborative cells, with global installed base exceeding 4.28 million units in 2024. Process gates run from forging and CNC tending to AI-vision inspection, each with quantified throughput and repeatability target
Additive manufacturing (AM) covers seven ISO/ASTM 52900 process families, splits into metal and polymer stacks, and is moving from prototyping to serial production via laser powder-bed fusion systems such as the Additive Industries MetalFab 420K. Selection pivots on part volume, alloy, tolerance, an
AS9100D-certified aerospace machining shops are layering AI vision, IIoT and customized automation cells into flight-critical part lines in 2026, with adoption tracked at 3 measurable inflection points: grinding accuracy, end-to-end digital traceability, and human-robot collaborative assembly.
A modern CPU is built as a multi-core die on a sub-7nm FinFET process, with 4-16 cores typical for desktop/embedded use and SMT/HT doubling the OS-visible thread count. Yield, binning, and chiplet packaging now decide the price band more than raw clock speed.
Copper manufacturing spans concentrate-to-cathode pyrometallurgy and electrowinning, foil rolling down to 6–9 µm for PCB and battery, plus OEM fabrication of plumbing and busbar stock; the 2026 spec gates are purity grade, oxygen content, and form-factor tolerance.
Air compressors are built around three core compression stages — reciprocating, rotary screw, and centrifugal — with cast-iron or aluminum housings, finned cylinder barrels, and ISO 8573-1 air-quality targets driving final assembly. Maintenance cost studies (2025-03) and current OEM controller relea
Heat pumps are vapour-compression refrigeration units run in reverse, delivering roughly 3 units of heat per unit of electricity consumed; 2025-2026 manufacturing centres on inverter-driven scroll compressors, R290/R32 refrigerants, EVI low-ambient operation down to -35 °C, and source variants (air,
Comau's MATE-XR family and dedicated electrolyzer/fuel-cell lines define the 2026 hydrogen smart-manufacturing playbook: high-payload robotics, 4.0 traceability and ISO TS 19880-1-aligned leak testing. Intelligent Energy and HyZero target 1-10 kW mobility stacks.
OLED panel fabs are adopting Industry 4.0 automation — vision-based Mura defect detection, AMOLED inline optical inspection, and Rockwell/Cisco-style IT/OT convergence now define greenfield Gen 8.6 lines. Smart-meter-grade data infrastructure underpins yield.
Power grid smart manufacturing merges digital-twin assembly lines, robotics, and grid-edge automation hardware; 2026 deployments are gated by IEC 61850 interoperability, OT/IT segmentation, and HVDC-ready production capacity.
Primary nickel is extracted from two fundamentally different ore types — sulfide ores processed by concentrator/smelter/matte-refining routes, and lateritic ores processed by pyrometallurgical ferronickel or hydrometallurgical high-pressure acid leaching (HPAL) — each with its own cost structure, en
Robotics production technology in 2026 rests on four interlocking layers — articulated manipulators with servo-driven joints, machine-vision guidance, end-effector tooling, and PLC-integrated cell control — engineered around ISO 10218 and ISO/TS 15066 safety thresholds for collaborative work.
Natural gas production spans conventional wellhead extraction, unconventional shale/shale-gas plays, and downstream synthesis-gas conversion; the U.S. EIA publishes dry-shale and total-dry production data on a rolling quarterly schedule (2Q 2026 released 6/30/2026) that engineers use to size plant f
Satellite smart manufacturing lines in China already deliver 240 sub-tonne small satellites per year with 40%+ efficiency gains, while global digital-twin and IIoT deployments scale small-sat production into 2026 industrial automation roadmaps.
Machine tool manufacturing covers the full flow from cast-iron bed, slide and spindle production through CNC assembly, geometric verification and end-milling condition monitoring; OEM catalogs in 2026-06 still group output into lathes, machining centres, EDM, drills and presses.
Lithium production in 2026 splits into three industrial routes — hard-rock spodumene mining, continental and geothermal brine evaporation, and adsorption-based Direct Lithium Extraction (DLE) — each delivering battery-grade Li2CO3 or LiOH·H2O at different cost, water and recovery profiles.
Display panel smart manufacturing pivots on LCD-to-OLED substrate transitions, laser patterning of heterogeneous films, and modular line architecture with cobot/AI control loops, per 2026 supplier and process-equipment data.
LED manufacturing spans epitaxial wafer growth on sapphire or SiC substrates, photolithography-defined mesa etching, thin-film metallisation, phosphor conversion for white light, and optical secondary lens moulding. Process windows sit in the 700-1100°C MOCVD range and 150-250°C packaging range.
Additive manufacturing joins material layer-by-layer from 3D model data, covering seven ISO/ASTM 52900 process families that drop scrap rates vs. subtractive methods. Process selection hinges on material, tolerance, lot size, and post-processing burden.
Nuclear-grade I&C vendors Framatome and ENSENMAX, plus the University of Manchester's £8m nuclear manufacturing lab, are pushing 2026 nuclear smart-manufacturing toward AI-driven sensing, in-house N-stamp fabrication, and electron-beam / powder-metallurgy cost control for high-integrity components.

Power semiconductor smart manufacturing in 2026 stacks OSAT-level AI vision, AMHS automation and WBG-aware process control onto 200/300 mm fabs; OSAT, R&D and supply-chain vendors now co-deliver turnkey Industry-4.0 retrofit packages rather than point tools.
Industrial display panels are flat-panel devices built through a multi-stage FPD process: TFT/LCD, OLED, and micro-LED lines share array→cell→module flows, with chemical etching, lithography, and laser lift-off defining yield, cost, and optical performance gates.
Petrochemical production technology converts crude oil, natural gas and NGL feedstocks into olefins, aromatics and polymers through cracking, reforming and separation units, with modern plants integrating DCS/APC control to manage 1,000+ tag counts and balance feedstock price volatility.
Smart-manufacturing server hardware in 2026 is sized around three workload classes — edge gateways, MES/IIoT aggregation, and on-prem AI inference — with CPU core counts, ECC RAM ratios, and OT/IT segmentation drives shaping procurement. Reference enterprise-sizing guidance for up to 1000 sites land
Cable and wire smart manufacturing in 2026-06 centres on non-backtwist stranding, AI-driven cable assembly lines, robotic wire-harness cells, and continuous-ink-jet coding — with Chinese strander, twisting and IDC harness suppliers leading the OEM equipment market.
Server hardware production technology covers the full chain from identical-node clustered builds, verified crypto coprocessor integration, and sizing rules for 1–1000 site enterprise management. Concrete thresholds like 300 MB disk, 256 MB RAM minimums, and Oracle RAC identical-node mandates define
Industrial pump smart manufacturing in 2026 centres on retrofit-friendly digital commissioning, condition monitoring, and PROFINET/PROFIBUS-based shop-floor control, with US custom builders such as Industrial Pump Manufacturing, Inc. and Tri-Rotor pairing decades-life rotary lobe hardware with IIoT-
AI chip manufacturing in 2026 is a multi-module flow: lithography, etch, deposition, CMP, implant, anneal, and advanced packaging, gated by EUV/High-NA exposure, FinFET or GAA transistor architecture, and Cu/Co/Ru interconnect stacks. Process windows are now defined at sub-3nm nodes with backside po
Crystalline-silicon PV cell manufacturing follows a 7-stage process flow from quartz feedstock to encapsulated module, with wet chemistry, plasma-enhanced CVD, and inline metrology gate every production node.
GPU-driven smart manufacturing fuses real-time shop-floor IoT telemetry, machine-vision inspection, and digital-twin simulation on a single compute stack, cutting defect rates and energy use versus PLC-only lines. Decision blueprint below.
Rare-earth smart manufacturing merges NdFeB/PrFeB magnet production with Industry 4.0 automation, IoT sensors, AI quality control and digital-twin process control. Mainstream deployments pair sintered NdFeB lines with automated sintering furnaces, robotic handling, vision-based grain-size inspection
Wind turbine smart manufacturing now combines digital-twin virtual factories, automated blade and nacelle lines, and AI-driven quality control; Goldwind, Vestas and Chinese OEM supply chains lead adoption as of June 2026.
Cobalt is recovered as a co-product of copper and nickel mining, with 2025 mine output near 290 kt and Democratic Republic of Congo supplying ~76% of supply. Hydrometallurgical SX-EW routes dominate oxide-ore feeds, while pyrometallurgical sulfation and chloride pathways treat alloys and black mass.
PV smart manufacturing in 2026 hinges on AI vision, fiber-laser cell processing and full-line MES integration, with c-Si driving scale and thin-film/II-VI expanding applications. Targets are sub-millimetre defect catch, 30%+ throughput lift and 99.5%+ line yield.
Smart manufacturing is reshaping industrial valve production in 2026: IIoT-connected assembly, in-line leak testing and digital-twin commissioning are compressing lead times while traceability moves to per-valve QR codes.
A standard multilayer PCB moves through roughly 10 to 14 discrete process steps, from inner-layer imaging and black-oxide treatment through lamination, drilling, electroless + electrolytic copper plating, outer-layer imaging, solder mask, surface finish, routing and final electrical test (per PCBWay
EV battery production is a dry-room, multi-stage flow: electrode coating → calendering → slitting → cell stacking (cylindrical / prismatic / pouch) → electrolyte injection → formation cycling → module/pack assembly, governed at the cell level by EU Regulation 2023/1542 carbon-footprint and recycled-
Petrochemical smart manufacturing in 2026 centers on tight integration of field instrumentation (smart valves, flow meters, pressure transmitters) with MES/APC layers to lift ethylene yield, cut energy intensity, and meet stricter safety and emissions rules. Reference plants now spec EtherNet/IP, PR
EV manufacturing in 2026 splits into four process families — body-in-white stamping/welding, paint, battery pack/module assembly, and final assembly — running on stamping presses, robotic welders, e-coat and top-coat lines, and torque-controlled EV battery pack assembly lines built around prismatic,
Modern power grids run on layered AC generation, HV transmission, and distribution automation, with 2026 standards pushing digital twins, IEC 61850 substation comms, and renewable integration for stability.
EV manufacturers in 2026 are scaling production through digital-twin-driven lines, machine-vision quality gates, and smart-meter energy loops; the bottleneck has shifted from cell availability to ramp-rate and line-right-first-time, with Siemens and Omron anchoring the reference stack.
Solar panel smart manufacturing on 2026-06-23 spans 50-800 MW turnkey assembly lines, EL/PL/UVF inline testers, and meter-mix potting systems; selection turns on throughput, line balance, and junction-box sealing yield, not brand.
Server hardware manufacturing spans sheet-metal fabrication, PCB assembly, and burn-in validation, with OEMs requiring identical nodes per Oracle RAC checklists and 400-day polling headroom on enterprise management systems.
Lithium battery production splits into electrode-fabrication, cell-assembly and pack-finishing lines, with LiFePO4, NMC and solid-state chemistries each demanding distinct dry-room dewpoints, formation protocols and aging gates through 2026.
Copper cathode at 99.97% purity is the global benchmark, produced by electro-refining of 97–99% blister anodes; pyrometallurgical smelting, slag dilution and signal-integrity active copper cabling each define a separate spec gate in the production chain.
Rolling-element bearing manufacturing runs forging → turning → heat treatment → grinding → assembly, with CNC grinding and ISO 9001 quality gates now standard across Chinese volume producers. Wuxi-based plants such as BC Bearing and Shenxi output GCr15 steel, double-row spherical and cylindrical rol
Lithium battery smart manufacturing in 2026 layers MES, AI vision, dry-room robotics and ISA-95 connectivity across electrode coating, calendaring and cell stacking; first-pass-yield gains of 5-15% are typical when the four cell-process sub-loops close on GEM300-style telemetry.
Connector smart manufacturing in 2026 hinges on PROFINET-based connected-enterprise rollouts from Rockwell, Renishaw data platforms, and IIoT edge gateways that bind sensor to cloud.
Steel smart manufacturing in 2026 stacks IoT sensors, AI vision, MES layers and robotics on top of legacy EAF/BOF mills, with Chinese mills and Tier-1 OEMs (Rockwell, Renishaw) shipping reference architectures for plate cutting, rolling and stamping cells that cut scrap and OEE losses.
AI-chip smart manufacturing now binds GEM300 SECS/GEM, Industrial Edge compute, and agentic AI vision into one stack; OT teams should anchor new fab builds to ISA-95/IEC 62443 controls and brownfield IO-Link bridges.
Smart manufacturing in natural gas systems means layering digital batch control, IIoT instrumentation, and automated inspection onto the gas-meter, valve, and engine production lines that already drive the sector. Vendors like Polaris Automation, SGS Manufacturing, and gas-meter OEMs are pushing MES
Additive manufacturing moved into factory-floor orchestration in 2026, with INTAMSYS releasing the INTAMSUITE platform on 2026-06-11 that fuses FFF 3D printing, MES hooks, and demand-to-delivery workflow for mixed additive/subtractive cells. The peer-reviewed 3D Printing and Additive Manufactur
Bosch is investing roughly EUR 100 million in heat-pump manufacturing, while Chinese OEMs scale IoT-driven smart lines for compressors, plate heat exchangers, and inverter drives. Smart-manufacturing stacks layer MES, IIoT sensors, and robotics onto traditional HVAC assembly.

Wafer fabrication splits into front-end (oxidation, lithography, etch, doping, CMP, deposition) and back-end (wafer test, dicing, packaging) per SEMI's published process overview. The fab process flow for a 300 mm logic device at Intel 18A-class nodes runs 1000+ sequential steps over 8-12 weeks
Drone smart manufacturing now couples AI-driven machine vision with MES-connected assembly lines, cutting cell cycle time by 30-50% across tier-1 Chinese OEMs while pushing flight-controller calibration into real-time closed-loop control.
Pneumatic actuation remains a dominant force in smart manufacturing, with smart pneumatic systems approaching electric and hydraulic in market share. Sensor-integrated cylinders, digital valve positioners and IIoT-linked FRLs are converting legacy compressed-air lines into Industry 4.0 nodes, though
Satellite production technology in 2026 spans a multi-stage build flow from payload integration and bus assembly through environmental testing, with Euroconsult's 28th "Satellites to Be Built & Launched" report tracking 2026-2027 manufacturing and launch output.

Power semiconductor manufacturing spans silicon ingot growth, epitaxy, lithography, etch, implant, metallisation, dicing and packaging, with Intel 18A, 3, and 16 nodes defining the leading-edge logic baseline as of March 2026.
Lithium manufacturing covers two distinct process chains: brine extraction plus conversion to battery-grade Li2CO3/LiOH·H2O, and hard-rock spodumene concentration plus acid/alkaline conversion. US capacity additions through 2026 focus on fully automated pack assembly with cell imports, while upstrea
Smart hydraulic manufacturing in 2026 centres on electro-hydraulic pumping units, IIoT-monitored manifolds, and digital-twin commissioning, with China-based integrators leading fixture and sensor deployments across mid-volume plants.
Larminie & Lowry's "Electric Vehicle Technology Explained" (2nd ed., Wiley 2012) remains the canonical academic reference covering BEV/HEV powertrain design, traction motor selection, battery sizing and energy management fundamentals taught across EV engineering programs.
Rare earth production spans mining, chemical cracking, solvent-extraction separation, metallothermic reduction, and electrorefining; molten-salt electrolysis dominates light REE (La, Ce, Pr, Nd) while Ca/Li reduction of fluorides produces Sm, Eu, Tm, Yb.

Silicon wafer manufacturing is a Czochralski- or Float-Zone-dominated ingot-to-wafer chain; commercial 300 mm wafers reach sub-nm surface roughness after CMP, with related SiC polishing cutting total time under 2 h per wafer.