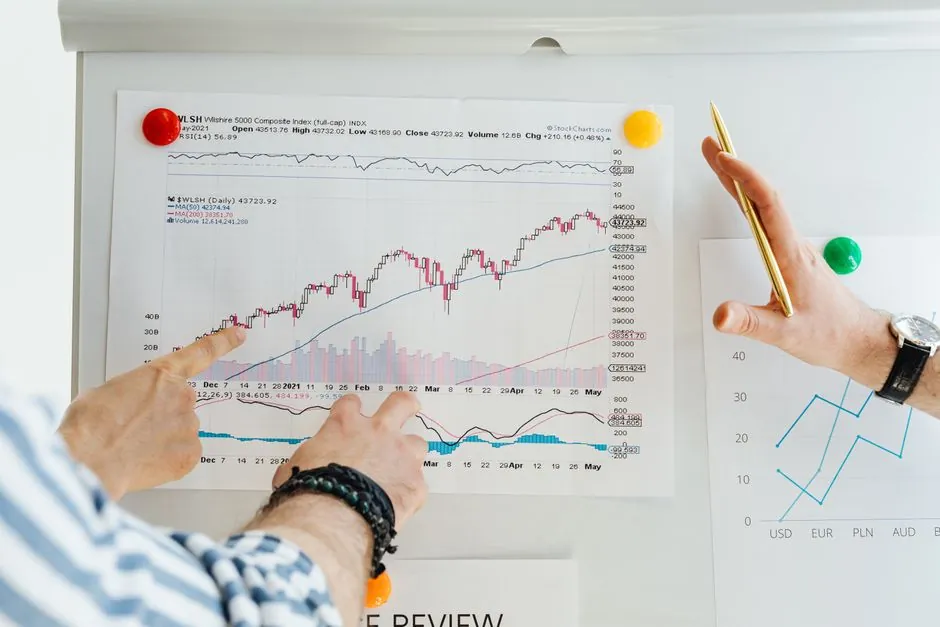
In September 2026, epoxy resin spot prices ranged from USD 1.97/kg in India to USD 4.68/kg in Europe, a 2.37x spread that maps almost directly onto each region's exposure to wind-turbine blade composite demand and electrical-laminate electronics output [S1].
Global market value was USD 12.17 billion in 2025 and is projected to reach USD 18.07 billion by 2033 at a 5.0% CAGR, with Asia Pacific holding 62.06% revenue share in 2025, anchored by Chinese capacity expansion at a 3.8% CAGR through 2033 [S4].
Regional Price Snapshot, March to September 2026
Northeast Asia moved from USD 2.13/kg in March 2026 to USD 2.21/kg in September 2026, a 3.8% lift driven by coatings, electrical laminate, and composite procurement against constrained domestic supply from scheduled turnarounds at key manufacturing facilities [S1]. Europe eased slightly from USD 4.63/kg in March to USD 4.68/kg in September, a net 1.1% move, with the protective coating, wind energy composite, and electrical laminate sectors providing only marginal procurement support [S1].
India ran the opposite direction, sliding from USD 2.25/kg in March 2026 to USD 1.97/kg by September, a 12.4% drop on weak coatings, construction adhesive, and electrical laminate demand, compounded by aggressive Chinese and Asian import offers that pushed the regional cost floor lower [S1]. The Middle East jumped 31.9% between December 2025 and March 2026 to USD 3.02/kg, then continued firming to USD 2.58/kg in September on construction and protective coating pull, though the month-on-month move varied with import parcel timing [S1]. North America saw the most dramatic single-quarter shift, with the Q1 2026 Epoxy Resin Price Index rising 22.55% quarter-over-quarter and an average delivered Gulf Coast price near USD 4,081/MT in the quarter ending June 2026 [S5].
Wind and Electronics as the Two Demand Pillars
Wind energy composite consumption is one of the three named demand pillars behind European price firmness, alongside protective coating and electrical laminate, and is explicitly cited as a buyer of available North American supply in the quarter ending June 2026 [S1][S5]. Blade manufacturers use epoxy as the matrix resin for glass and carbon fiber laminates, so a single 80-90 m offshore blade can consume several tonnes of formulated epoxy, which is why European spot prices remain the world's highest at USD 4.68/kg despite a softening eurozone construction PMI of 43.4 in September 2026 [S1][S2].
Electronics-grade electrical laminate demand is the second pillar and the more volume-sensitive of the two, since PCB substrate production reacts to consumer electronics and 5G base-station build cycles within a quarter. USA's Q2 2026 Epoxy Resin Price Index rose 22.55% quarter-over-quarter on tightened supply, as constrained imports and distributor drawdowns tightened spot availability regionally [S5]. For process engineers selecting matrix systems, synthetic resin grades and PEEK high-performance thermoplastic options are the two main reference families to compare against standard DGEBA epoxy on temperature, fatigue, and moisture uptake.
Feedstock Cost Drivers: BPA and Epichlorohydrin
Bisphenol A (BPA) and epichlorohydrin (ECH) are the two upstream feedstocks that set the variable cost floor for every grade on offer, and their movement is the single best leading indicator of where epoxy will trade two to three months out [S1]. In Northeast Asia through Q1 2026, rising BPA and ECH costs at regional production facilities elevated manufacturing expenses and provided consistent upward support to prevailing market rates, while in India, declining BPA and ECH costs eroded the cost floor and reinforced bearish conditions [S1].
For North American Q2 2026, the Epoxy Resin Production Cost Trend rose as energy and freight charges increased, even with weaker bisphenol-A, meaning transport and power, not just feedstock molecule price, now account for a measurable share of the delivered Gulf Coast premium over domestic replacement cost [S5]. When comparing offers, buyers should request the BPA:ECH ratio used in the specific grade, because high-purity electronics laminates often run a different stoichiometry than bulk wind-blade infusion systems, and that ratio drives both cured Tg and pot life in field conditions.
Volume Tier and Specification Cost Stack
Bulk unmodified liquid DGEBA epoxy sold into general-purpose coatings and construction adhesive channels trades in a tight band near the regional index and is the grade most exposed to BPA and ECH spot moves. Higher-value grades stack cost upward: low-chlorine electronics grades that meet PCB substrate purity limits, viscosity-controlled infusion systems for wind blade layup, and toughened or flexible variants such as those in the global flexible epoxy resin market valued at USD 1.2 billion in 2024 with a forecast 8.62% CAGR [S8].
For total-cost-of-ownership, three non-purchase line items matter as much as the headline price. Second, certification and traceability: wind-blade grade epoxy typically requires batch-level certificate of analysis, lot-traceability documentation, and sometimes customer-specific qualification that adds compliance overhead but reduces in-field failure risk. Third, energy and process yield: higher-viscosity or faster-cure systems can cut cure cycle time and oven energy, which is why some buyers accept a 5-10% resin premium in exchange for measurable throughput gains. For buyers navigating distribution and logistics friction across regions, distribution transformer lead times in 2026 offer a parallel read on how project schedules, not raw material cost alone, shape delivered equipment cost.
Logistics Risk: Drought, Freight, and Inventory Cycles
Non-feedstock logistics are a first-order cost driver in 2026, not a tail risk. In Brazil, the Rio Negro fell 5.21m in September 2026, down from 24.09m to 18.88m, with the steepest decline at 23cm/day between 19-25 September, and a severe scenario projecting 13-16m could cut vessel capacity by 55% and lift transport costs up to 195% [S2]. That matters for any buyer routing resin through the Manaus industrial hub, which handles roughly 60% of the free-trade zone's cargo by coastal shipping and is a key entry point for imported polymers serving Brazil's electronics, home appliance, and air-conditioner manufacturing base [S2].
Eurozone construction activity provides a second cross-check: the construction PMI printed 43.4 in September 2026, below 50, with input price inflation accelerating for the first time since April to its highest level since late 2022, meaning epoxy-linked construction adhesives, pipe, insulation, and coatings face weak volume offset by rising input cost [S2]. For buyers running parallel industrial MRO and project portfolios, steel strapping sizes from 12.7 to 31.75 mm and XPS grades for under-slab and inverted roofs are the kind of complementary commodity reads that confirm whether the construction slowdown is broad-based or isolated to specific sub-segments.
Application Stack Comparison: Coatings vs Wind vs Electronics
Coatings is the largest volume application and the most price-sensitive, growing at 5.9% CAGR through 2033 in the construction sub-segment, and it is the application that drags India pricing down when construction adhesives and protective coating demand weaken [S4][S1]. Wind energy composite is a smaller but more concentrated channel where single-project offtake can move regional spot, especially in Europe where blade makers compete for limited high-grade inventory. Electronics and electrical laminate is the highest-purity, most specification-driven channel, with Japanese and Korean producers often running tight export FOB discipline and capturing the Asia Pacific price premium [S5].
Volume in metric tons is forecast to grow from 3.27 million tons in 2025 to 3.36 million tons in 2026 and 3.99 million tons by the end of the outlook window, confirming that absolute consumption is rising even as regional price spreads widen [S7].
Who Pays the Premium and Who Should Walk Away
Buyers who should accept European or North American premium pricing in 2026 are those tied to wind-blade OEM qualifications, electronics-laminate purity specs, or just-in-time delivery into regulated aerospace and rail programs, because the cost of a failed batch outweighs the 10-20% resin premium. Buyers who should hedge or walk away are those running commodity coatings, construction adhesive, or general-purpose civil engineering applications in regions with active import competition from China and other Asian producers, since the India case in 2026 shows domestic premium cannot be sustained against import offers [S1].
For shop-floor context on how premium and commodity industrial inputs are routed through the same plants, sump pump cost drivers across HP and switch type and truck crane pallet fork attachment capacity derating are the kind of cross-category reference reads that anchor a 2026 procurement budget in real installed-cost terms rather than headline resin index. The strongest 2026 signal to track next is whether the North American Q3 2026 Price Index holds above the USD 4,081/MT Gulf Coast average or softens on restocking, and whether BPA-ECH feedstock costs in Northeast Asia break their Q1 2026 upward trend before the next blade-fabrication order book opens.
Spec-level background on the components involved: checking and testing apparatus.