Power semiconductor sourcing rests on three distinct material classes, each with its own purity spec, supplier map, and lead-time profile, so a procurement plan that treats them as a single category will misprice risk [S1][S2].
The foundation layer is 11N-purity (99.999999999%) electronic-grade polycrystalline silicon, grown into single-crystal ingots by the Czochralski process at about 1420 °C and sliced into 200 mm or 300 mm wafers; a 450 mm format remains in development [S1][S2]. The mid layer is wide-bandgap compounds (silicon carbide at ~3.26 eV and gallium nitride at ~3.4 eV) for EV power electronics, RF amplifiers, and renewable-energy inverters, with CAS-numbered precursors (SiC 409-21-2, GaN 25617-97-4, GaAs 1303-00-0, InP 22398-80-7) used in CVD/ALD deposition [S2]. The third layer is the critical-mineral feed: gallium, germanium, and high-purity quartz are sourced primarily from Chinese producers, with downstream concentration risk now baked into every RFQ [S4][S6].
Silicon wafers: 11N purity, Cz vs FZ, and 200/300 mm standardisation
Electronic-grade polysilicon is refined from metallurgical-grade silicon (98-99% purity) by reacting with chlorine and hydrogen to form volatile silicon tetrachloride (SiCl4) and trichlorosilane (SiHCl3), which are then decomposed by chemical vapor deposition to deposit ultra-high-purity polysilicon with impurity content in the parts-per-billion range or lower [S1].
Two single-crystal growth routes dominate: the Czochralski (Cz) process, which melts polysilicon at approximately 1420 °C in a quartz crucible and slowly pulls a seed crystal upward to form ingots exceeding 300 mm in diameter, and Float Zone (FZ) for higher-resistivity applications; doping with phosphorus or arsenic yields n-type wafers, while boron doping yields p-type [S1][S2]. The global silicon wafer market reached $13.6 billion in 2024, with 200 mm and 300 mm as industry-standard diameters and 450 mm still in development [S2]. For context on how wafer-level material decisions ripple into the broader MEMS and sensor sourcing chain, see this MEMS sensor raw material sourcing breakdown.
Wide-bandgap compounds: SiC and GaN properties, CAS numbers, and end-use fit
Wide-bandgap semiconductors outperform silicon in any application that demands high breakdown voltage, high switching frequency, or operation above ~200 °C junction temperature, with SiC at ~3.26 eV and GaN at ~3.4 eV the two workhorses for power and RF designs [S2].
SiC (CAS 409-21-2) is specified for EV traction inverters, renewable-energy power conversion, and high-temperature devices, but its crystal growth remains difficult and slow; GaN (CAS 25617-97-4) is used in RF power amplifiers, fast chargers, and LEDs, with gallium supply concentration flagged as a structural risk in the same source [S2]. Adjacent materials fill narrower niches: GaAs (CAS 1303-00-0) for optoelectronics and high-speed transistors, InP (CAS 22398-80-7) for fiber optics and high-frequency RF, and SiGe with its tunable bandgap for high-speed BiCMOS [S2]. A decision matrix on power-class devices usually hinges on four criteria: bandgap/breakdown voltage, thermal conductivity, switching frequency, and unit cost per ampere, and on those axes SiC wins for >1200 V traction while GaN wins for 100-650 V high-frequency DC-DC stages.
Process chemicals and precursors: ALD/CVD purity grades and CAS-tracked sources
Atomic Layer Deposition and Chemical Vapor Deposition require metal-organic and silicon precursors with purity specifications tight enough that trace metals must sit in the parts-per-billion range or below, so procurement specs should always carry a CAS number plus a maximum impurity budget [S2].
Common precursors line up cleanly by application: trimethylaluminum (TMA, CAS 75-24-1) as the Al source for Al2O3 high-k dielectrics, tetrakis(ethylmethylamino)hafnium (TEMAH, CAS 352535-01-4) for HfO2, tetraethylorthosilicate (TEOS, CAS 78-10-4) and silane (SiH4, CAS 7803-62-5) for SiO2, and bis(tertiary-butylamino)silane (BTBAS, CAS 186598-40-3) plus dichlorosilane (DCS, CAS 4109-96-0) for silicon nitride [S2]. The broader process-chemical basket, including photoresists, CMP slurries, wet-etch chemistries, and electronic specialty gases, accounts for the largest single sub-segment of the wafer-fab materials market, historically growing faster than packaging materials (12.7% vs 5.4% year-on-year in the 2017 SEMI tally) [S3].
Critical-mineral supply: gallium, germanium, and quartz concentration risk
Gallium, germanium, and high-purity quartz are the three feedstocks most exposed to single-country supply concentration, and a 2025 industry guide explicitly names China, Japan, and a small set of Western producers as the primary source geographies [S4][S6].
For GaN epitaxy, gallium supply concentration is the binding constraint on capacity expansion, and for SiGe and certain photonics grades, germanium availability follows a similar pattern [S2][S4]. High-purity quartz, the starting point for the crucibles and quartz-glassware used throughout ingot growth and furnace linings, sits upstream of every other material on this list, so a quartz disruption cascades into Cz-crucible supply within weeks [S1][S6]. Procurement teams that need to cross-check where this intersects with broader process-chemical sourcing dynamics can use this specialty chemicals 2026 market breakdown as a reference point.
Sourcing criteria: purity grade, CAS verification, dual-source, and lead time
A defensible raw-material specification for power semiconductors carries four non-negotiable items: a quantified purity target (for silicon, 11N polysilicon or 6N prime wafer minimum, expressed as a decimal plus the nines notation), a CAS number for every precursor and compound, a dual-source requirement for any single-country-concentrated mineral, and a documented lead time with a buffer calibrated to the wafer fab's safety stock policy [S1][S2].
The 2017-2018 SEMI data still cited in the industry shows global semiconductor material sales moved from $46.9 billion (2017) to $51.9 billion (2018), a 10.6% jump, with wafer-fab materials outgrowing packaging materials at 15.9% vs 3.0% in 2018, evidence that upstream material demand scales faster than downstream unit volume when fab capacity expands [S3]. The same source notes that 62 fabs came online globally from 2017 to 2020, with 26 of them in mainland China (about 42% of new capacity), and mainland China also hosts a large share of the back-end packaging-material supply base [S3]. For engineering teams sizing the instruments that validate these incoming materials, this signal calibrator sizing guide covers loop-level accuracy and class matching.
Who this sourcing model is for, and where it breaks down
This 11N-silicon plus wide-bandgap plus critical-mineral model fits any procurement function feeding wafer fabs, power-module assembly lines, or compound-semiconductor epitaxy, and it breaks down for legacy 150 mm fabs running older analog processes, for MEMS-only houses that need a different precursor mix, and for any buyer who treats GaAs or InP as interchangeable with GaN [S2].
Three failure modes to plan for: first, quoting a 6N prime wafer spec on an 11N project (or vice versa) drives yield loss that no downstream test catches; second, single-sourcing a gallium or germanium line without a documented second qualified vendor leaves the line exposed to export-control shocks that have already hit these minerals in the past two years [S4][S6]; third, treating packaging materials (lead frames, bonding wire, die-attach, ceramic substrates) as fungible with wafer-fab materials ignores the fact that packaging sub-segments grew only 3.0% in 2018 versus 15.9% for fab materials, and they have entirely different supplier sets [S3]. Engineers sourcing the metrology side of incoming-material inspection can cross-reference this data logger supplier map for traceability logging requirements.
Standards, traceability, and the verification chain
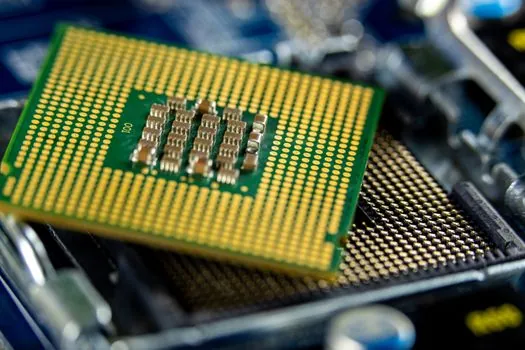
Material specifications in this domain are governed by SEMI international standards for wafer geometry and surface finish, by ASTM/ICP-MS methods for trace-metals assay, and by cas-number-level chemical identification for precursor compliance, with the bandgap figures (SiC ~3.26 eV, GaN ~3.4 eV) treated as material constants rather than user-settable parameters [S1][S2].
For power-module end use, the downstream standards stack (AEC-Q101 for automotive discrete semiconductors, JEDEC JESD22 for reliability stress tests, IEC 60747 for discrete device qualification) dictates what an incoming-material certificate must contain, so procurement specs should reference those standards explicitly rather than generic ISO 9001 language [S2]. The practical audit trail is: lot-traced polysilicon with assay certificate, CAS-numbered precursors with impurity certificates per shipment, dual-sourced critical minerals with country-of-origin documentation, and a calibration chain on the metrology that verifies it (covered in the power meter selection piece for power-generation sites and the reactive power compensation sizing guide for the grid-side interface).
Trackable next signal: the 450 mm wafer format remains in development and has not yet reached general commercial production, so any 2026 RFQ should still be sized to 200/300 mm [S2]. The other watch item is the gallium and germanium supply concentration, with China-listed as the primary source in 2025 industry guides and no second-source qualification track yet documented at scale [S4][S6].
Spec-level background on the components involved: linear guide, crossed roller guide, and power cable.