The US exports roughly 600,000 tons of copper scrap per year, a volume equal to about 5% of global mined copper output and the largest single national flow in the world [S1]. On August 1, 2025, a 50% Section 232 tariff landed on imported semi-finished copper and copper-intensive derivative products (pipes, wires, rods, sheets, tubes, cable, connectors), while copper ores, concentrates, mattes, cathodes, anodes, and scrap were excluded from the duty and from reciprocal tariffs [S2][S6].
ReMA (the Recyclers of Materials Association) successfully argued that the domestic copper recycling industry is "strong and robust" and that data did not warrant export curbs, so the White House did not adopt the Commerce Department's recommendation for an export licensing system on high-quality copper scrap [S3]. What survives is a directed review: the Commerce Secretary is authorized to take steps, including under the Defense Production Act, to assure that 25% of US-generated "high-quality copper scrap" is sold into the domestic market, with implementation guidance still pending [S2][S4].
Where US Scrap Flowed Before the 2025 Reset
China alone absorbed nearly 40% of US copper scrap exports before the policy debate, making it the most exposed single buyer to any curtailment [S1]. Malaysia's pull on US scrap rose 8.56% as Chinese and other Asian buyers hedged supply risk, illustrating how thin the secondary-feed market is when one node shifts [S1]. For context, OECD tracking shows critical raw materials face export restrictions on roughly 16% of global trade in 2022-2024, up from about 12% in 2009-2011, so even the removal of a US curb keeps the secondary market inside a tightening regulatory perimeter [S7].
The US shipped about 600,000 t/yr of copper scrap, dominated by No.1 and No.2 bare bright, copper-bearing radiators, and copper wire harness chops typical of what copper material processing lines grade at the source. A full export ban would have removed volume equivalent to 5% of global mined output, a shock Asian rod and brass mills could not have offset in a single quarter without rerouting European and Latin American parcels [S1].
What Survived: The 25% Domestic-Sales Mandate
Instead of a hard export licensing system, the proclamation authorizes the Commerce Secretary to consider "domestic sales mandates" for high-quality copper scrap when national defense needs are identified, with a stated 25% domestic-allocation target [S2][S3]. The White House did not define "high-quality scrap," a gap ReMA flagged immediately and plans to work through with Commerce on definitions, exemption thresholds, and reporting cadence [S3].
The decision triggered a 18% single-session drop on Comex as the LME-SHFE arbitrage unwound, with US copper giving back a multi-week premium to the London benchmark that had built up on shipment diversion expectations [S2]. For secondary refiners running checking and testing apparatus on inbound parcels, the practical signal is twofold: feedstock definitions will narrow around alloy content, ISRI grade codes, and radiation/contamination screening, and defense-pull clauses will sit above the standard 25% floor in a declared shortfall.
Refiner Feed Math: What Changes for Secondary Smelters
US domestic smelting infrastructure remains thin, with only three operational primary smelters handling the bulk of concentrate feed, so any marginal tonnage retained by the 25% mandate has to be absorbed by secondary refiners running fire-refining and electrorefining on Cu-rich scrap streams [S1]. Closed-loop recycling has been projected to eventually supply up to 40% of US copper needs, but that ceiling is contingent on new anode-casting and SX-EW capacity that has not been commissioned at the scale required to absorb a sudden 150,000 t/yr (25% of 600,000 t) mandate-driven floor [S1].
The tariff structure is the other side of the feed story: at 50% on semi-finished copper and copper-intensive derivatives, the effective landed cost of imported wire rod, cable, and pipe fittings has moved well above the Comex-LME spread, pushing downstream fabricators to source more cathode and scrap-based billet domestically [S2][S6]. A refiner running a typical 100,000 t/yr secondary line can therefore expect higher domestic scrap intake and tighter competition for No.1 bare bright and chops, while lower-grade No.2 and light copper keeps flowing to export at minimal premium compression.
Market Structure and the Trading Lens
The grand-view copper scrap market was sized at $39.6 billion in 2025 and is projected to reach $42.4 billion in 2026, with a 9.3% CAGR through 2033 and a $78.9 billion terminal value, so even a single percentage point of feed reroute has multi-billion-dollar downstream consequences [S8]. Comex-LME spread compression of 18% in one session is consistent with that scale: when physical arbitrage windows close, scrap price differentials between US and LME hubs typically fall inside a 5-15% band as alternative parcels from Europe and Latin America fill the gap [S1][S2].
Buyers hedging input cost on rod and wire rod contracts have already moved to basis-linked formulas that strip out the Comex premium, an approach covered in detail for cable procurement teams in Copper Price Hedging for Cable Buyers. For European and Asian rod mills, the immediate 2026-2027 question is not US export bans but US domestic-pull timing: if the Commerce Secretary invokes the mandate under a declared defense shortfall, parcel availability outside North America will tighten by 100,000-150,000 t/yr on a 600,000 t/yr base, a swing large enough to redraw freight lanes.
Comparison: Three Policy Paths and Refiner Exposure
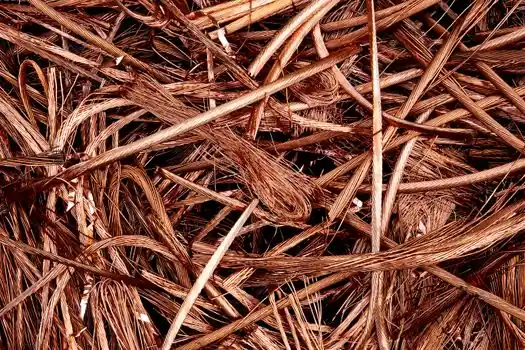
Three policy paths were live in July 2025 and resolved in early August. Path A, a hard export ban on all US copper scrap, would have removed 600,000 t/yr (5% of mined copper equivalent) from global markets and crushed Asian refiner feed, with China taking a 40% direct hit [S1]. Path B, an export licensing system on "high-quality scrap" recommended by Commerce, was the partial curb that would have channeled the cleanest, highest-Cu-content parcels to domestic secondary refiners while letting lower grades keep flowing abroad [S2]. Path C, the implemented path, drops export licensing entirely, leaves the 25% domestic-sales mandate as a directed review tool under the Defense Production Act, and exempts all copper scrap from the 50% Section 232 import tariff [S2][S3][S6].
On refiner feed risk, Path A scores worst for Asian rod and brass mills, Path B scores worst for Asian high-grade scrap buyers, and Path C is neutral-to-positive for global secondary refiners but leaves US domestic refiners waiting on a Commerce-defined "high-quality" boundary. On price spread, Path A would have widened the LME-Comex differential to the upper end of the 5-15% range, Path B would have narrowed it for high-grade parcels only, and Path C has already collapsed the Comex premium by 18% in a single session [S1][S2]. On regulatory certainty, Path C scores lowest because the 25% mandate and the "high-quality" definition are both unfilled rulemaking slots, while tariff and licensing lines are now clean and tradable [S3].
Limitations, Open Rules, and What to Track
Three constraints will define the next 12 months. First, the term "high-quality copper scrap" is undefined in the proclamation, and ReMA has explicitly committed to working with Commerce on the boundary; until that rule is published, the 25% mandate is a ceiling, not a binding allocation [S3]. Second, US primary smelter capacity is the bottleneck: three operating smelters cannot absorb a 25% mandate-driven 150,000 t/yr shift, so any defense-pull invocation effectively hands volume to secondary refiners running construction machinery and equipment-grade shredder and shear lines on demolition and end-of-life feed [S1]. Between 2022 and 2024, on average, approximately 16% of global trade in critical raw materials faced at least one export restriction, up from about 12% in 2009-2011, indicating that any easing of US scrap-export curbs does not reverse the broader tightening of material-flow controls elsewhere [S7].
Trackable signals for the next 60-90 days: Commerce's "high-quality scrap" definition and ISRI-grade mapping, the first 25% domestic-sales compliance report if and when defense-pull is invoked, and any LME-Comex spread re-widening as US inventories draw under the 50% semi-finished tariff. For procurement teams, the practical 2026-2027 watchlist is short: confirm cathode and scrap exemption status on every inbound PO, lock rod and wire rod basis formulas that neutralize Comex premium swings, and qualify at least one non-US secondary refiner as a parallel feed source for high-Cu chops and bare bright.